How State Interest Rate Caps Affect Short Term Loan Offers
State interest rate caps decide which short term loan offers can legally reach you. See why APRs vary by state and how to check your rules first.
By Mark Reynold
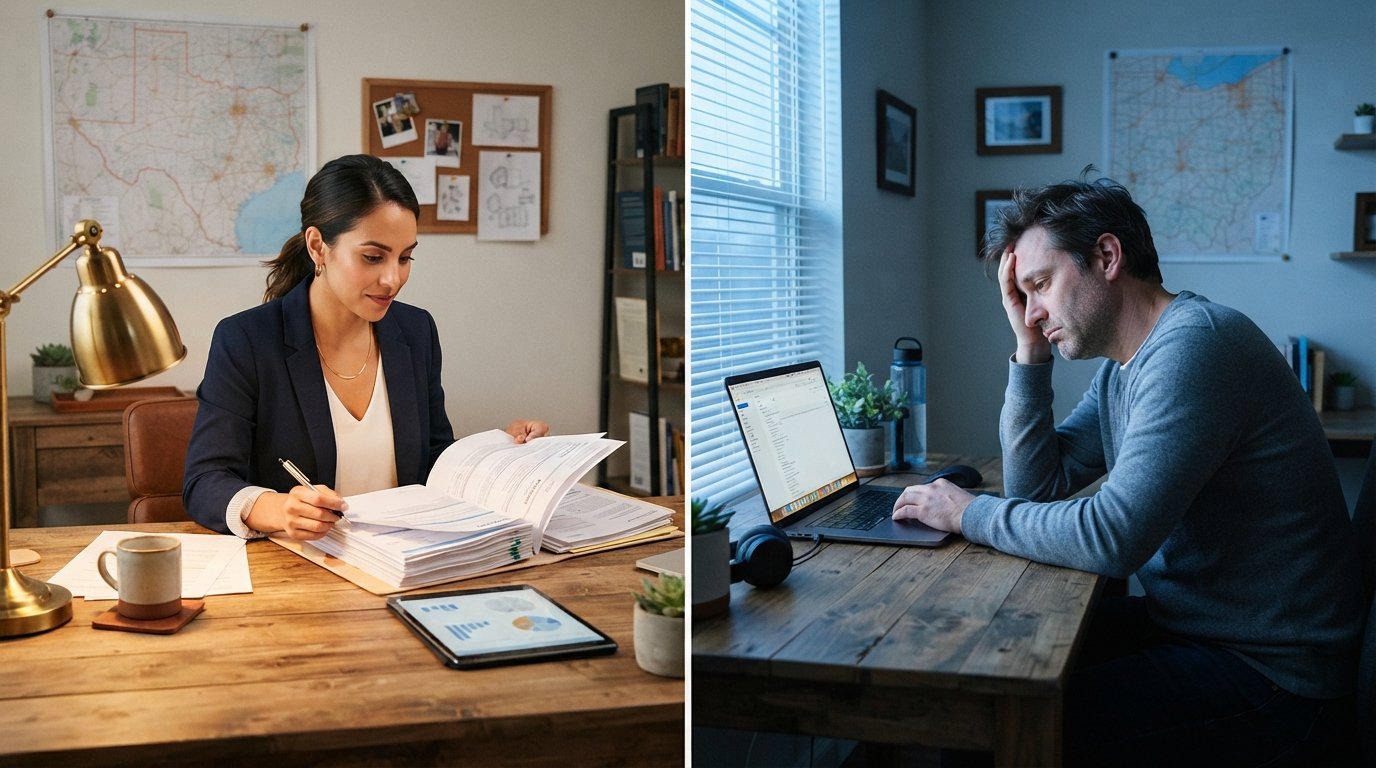
You fill out a loan request in Texas, and offers roll in. Your cousin in Ohio tries the same thing and gets nothing. Same income, same credit score, same urgency. The difference is not luck. It is state law. Every state sets its own ceiling on how much interest and fees a lender can charge, and those limits reshape which short term loan offers can legally reach you. Understanding how state interest rate caps affect short term loan offers can save you hours of frustration and help you plan around rules that are outside any lender's control.
The Legal Ceiling: How State Usury Limits and APR Caps Differ
The United States does not have a single national interest rate cap for consumer loans. Instead, each state writes its own usury laws, and those laws vary dramatically. Some states cap annual percentage rates (APRs) at or below 36 percent for certain loan sizes. Others allow much higher rates for short term products, and a few impose no explicit numeric cap at all, relying instead on other consumer protections. The result is a patchwork where the same borrower profile can produce wildly different offers depending on ZIP code.
The APR is the number that matters most because it bundles interest and most fees into one annualized figure. A payday-style loan that charges $15 per $100 borrowed for two weeks looks small at the counter, but annualized it works out to an APR near 400 percent. In a state with a 36 percent APR cap, that product cannot legally be offered. In a state with no cap, it can. This is the single biggest reason short term loan offers differ so much from one state to the next.
It also helps to know that caps often depend on loan size and loan type. A state might cap a $500 installment loan at one rate and a $3,000 loan at another. Some states treat payday loans, title loans, and installment loans under separate statutes, each with its own fee schedule. When you compare offers, read the APR and the fee breakdown together, because a low headline rate can hide a large origination fee that pushes the true cost much higher. For a worked example of how fees stack up, see this advance cash interest cost example that walks through the math step by step.
Why Some Products Are Simply Not Available in Certain States
When a rate cap makes a product unprofitable, lenders usually exit that market rather than absorb losses. That is why residents of some states see almost no payday loan offers while residents of neighboring states see dozens. The product did not disappear because of borrower demand. It disappeared because the legal ceiling left no room for the lender's cost of capital, risk, and operations.
This has a direct effect on how state interest rate caps affect short term loan offers: in tightly capped states, the offers you do receive tend to be larger, longer-term installment loans rather than small two-week advances. Lenders shift toward products that can spread costs over more payments while staying under the cap. In states with looser rules, small short term offers remain common. Neither outcome is inherently better for you. Each simply reflects what the law allows.
State licensing adds a second layer. A lender must generally be licensed in your state to offer you a loan there, and licensing rules often track the rate caps. If a lender is not licensed in your state, it cannot present you an offer no matter how strong your application looks. This is why a lender that advertises heavily nationwide may show up as unavailable the moment you enter your address.
Common ways states restrict short term products
Most state rules fall into a few recognizable patterns. Knowing them helps you predict what you will see when you request offers:
- Outright APR caps: a hard ceiling (often 36 percent) that rules out most short term products entirely.
- Fee-based limits: a maximum finance charge per $100 borrowed, which caps cost without stating an APR.
- Loan size and term limits: restrictions on how much you can borrow and how long the loan can run.
- Rollover and renewal bans: rules that prevent extending a loan repeatedly, which changes the effective cost.
- Cooling-off periods: mandatory waiting periods between loans that limit how often you can borrow.
These rules interact. A state with a generous fee limit but a strict rollover ban may still produce expensive offers, because the lender must recover costs within a single short term. A state with a low APR cap and no rollover ban may offer almost nothing at all. Reading your state's rules as a package, not as a single number, gives you a realistic picture before you apply.
How to Check Your State's Rules Before You Request a Loan
A few minutes of research can save you from submitting requests that were never going to produce offers. Start with your state's financial regulator, usually the department of financial institutions, the banking department, or the attorney general's consumer protection office. These agencies publish plain-language summaries of permitted loan types, maximum rates, and licensing requirements. Many also maintain a lookup tool so you can confirm whether a specific lender is licensed to do business in your state.
Next, read the disclosures on any offer you receive. Federal law requires lenders to show the APR, the finance charge, the payment schedule, and the total of payments. Compare those numbers against your state's limits. If an offer appears to exceed the cap, treat it as a red flag and verify the lender's license before signing anything.
A simple pre-application checklist keeps the process efficient:
- Confirm your state's APR or fee cap for the loan type you want.
- Check whether the product (payday, installment, personal loan) is permitted at your loan size.
- Verify the lender's license through your state regulator's lookup tool.
- Review the APR, finance charge, and total repayment on every offer before accepting.
If you are comparing several options at once, a structured approach helps. Our guide on finding short term loan options through a connection service explains how a single request can surface multiple lender offers, which makes it easier to compare APRs side by side within the limits your state allows.
Why a Connection Service Cannot Override State Eligibility Rules
It is tempting to assume that a loan connection service can somehow route around a state cap. It cannot, and it is important to understand why. A connection service is not a lender. It does not set rates, approve applications, or fund loans. It passes your request to third-party lenders in its network, and each of those lenders applies its own licensing and state eligibility rules before deciding whether to present an offer.
That means the service has no authority to waive a rate cap, relax a licensing requirement, or invent an offer that state law prohibits. When you submit a request, the lenders in the network check whether they can legally lend to you in your state at your requested amount. If the answer is no, no offer appears. The service is functioning correctly in that scenario, not failing you.
This is also why the offers you see can change from month to month. If a lender exits your state or adjusts its product lineup to comply with a new cap, the offers available through any connection service change with it. The underlying rule is simple: state law sets the boundaries, lenders decide whether to operate inside those boundaries, and a connection service can only show you what lenders are willing to offer.
When No Offers Are Available in Your State
Receiving no offers is disappointing, but it is useful information. It usually means one of three things: your state's cap rules out the product you requested, no licensed lender in the network currently serves your state for that product, or your application details did not meet a lender's criteria. You can often distinguish between these by trying a different loan type or amount before assuming the worst.
If caps are the obstacle, consider alternatives that fit inside your state's rules. A larger installment loan spread over more payments may be permitted where a small payday-style advance is not. A credit union or community bank in your state may offer a small personal loan under a different rate structure. Building a modest emergency fund, even slowly, reduces how often you need short term credit at all. None of these options is instant, but each can be more sustainable than forcing a product your state does not allow.
It also helps to set realistic expectations before you apply. Knowing your state's cap tells you in advance whether a $500 two-week advance is even a legal product where you live. If it is not, you can skip the request and go straight to alternatives, saving time and avoiding unnecessary inquiries on your record.
Putting It Together: Caps Shape Offers, Not Your Options Entirely
State interest rate caps are the quiet force behind nearly every short term loan offer you will ever see. They determine which products can exist in your state, which lenders can operate there, and what APRs are legally possible. When offers are plentiful, the caps are likely loose. When offers are scarce, the caps are likely tight or the licensing rules are strict. Neither situation says anything about you as a borrower.
The practical takeaway is to research your state's rules first, compare APRs and total repayment second, and treat any offer that seems to exceed state limits as a warning sign. If you understand the ceiling, you can evaluate every offer against it and borrow with far fewer surprises. State law draws the lines, and the best loan offers are the ones that fit inside them.