Do Short Term Loans Report to All Three Credit Bureaus?
Do short term loans report to all three credit bureaus? It depends on the lender. Learn how reporting works and how to check your credit reports.
By Emily Parker
You need cash quickly, and a short term loan seems like the answer. But before you sign, a question nags at you: will this show up on my credit report? The answer is not a simple yes or no. It depends entirely on the lender and the type of loan you choose. Some short term lenders report to all three major credit bureaus (Equifax, Experian, and TransUnion). Others report to only one. Many report to none at all. Understanding this variability is crucial because your payment behavior on these loans can either build your credit or damage it, and you need to know which outcome to expect. This guide breaks down exactly how reporting works, why it varies, and how to check your own reports to see what is actually being reported.
Why Reporting Varies by Lender and Loan Product
Not all short term loans are created equal, and neither are the lenders who offer them. The decision to report to credit bureaus is voluntary for most lenders, though some choose to report for strategic reasons. Traditional banks and credit unions that offer short term loans almost always report to all three bureaus because they have established data furnisher relationships. Online lenders and payday lenders, however, operate under different business models. Some see reporting as a way to encourage responsible borrowing and help customers build credit. Others avoid reporting because the administrative cost is not worth it, or because they prefer to keep their lending practices opaque.
The type of loan product also matters. Installment loans, which have fixed payments over a set period, are more likely to be reported than payday loans or cash advances. That is because installment loans resemble traditional credit products and lenders often use them as a stepping stone for customers with thin credit files. Payday loans, by contrast, are typically short term (two to four weeks) and many payday lenders do not report on-time payments to the bureaus. They may, however, report delinquencies or send accounts to collections, which then appear on your report. This asymmetry is important: a lender that does not report your good payments may still report your bad ones.
Credit unions and community banks that offer small short term loans often report to all three bureaus because they want to help members build credit. Online installment lenders may report to one or two bureaus, depending on their data sharing agreements. The key takeaway is that you cannot assume anything. You must ask the lender directly or check your credit reports after the loan is funded. For those exploring options, our guide on how to qualify for a short-term cash loan even with bad credit explains how different lenders view credit history and what to expect.
Which Bureaus Does a Given Lender Report To?
Even when a lender does report, they may not report to all three bureaus. Some report only to Experian, others only to TransUnion, and some to Equifax. The three bureaus are separate companies, and lenders must set up data furnisher accounts with each one individually. Smaller lenders may choose to report to just one bureau to reduce costs. This creates a fragmented picture of your credit history. A loan that appears on your Experian report might be invisible on your TransUnion report. That is why checking all three reports is essential if you want to know the full story.
Large banks and major online lenders typically report to all three bureaus because they have the infrastructure and volume to justify it. Fintech lenders and newer startups may report to one or two. Payday lenders and title lenders are the least likely to report to any bureau, though some do report to specialty consumer reporting agencies like Clarity Services or Teletrack. These specialty agencies track payday loan usage and are used by lenders to assess risk, but they are not the same as the three major credit bureaus. Your FICO score is not affected by specialty agency data, but lenders may still use it to deny you credit.
To find out which bureaus a specific lender reports to, you can ask the lender directly before applying. Look for a section on their website about credit reporting, or call customer service. If you already have the loan, you can check your three credit reports for free at AnnualCreditReport.com. If the loan appears on one report but not the others, you will know which bureau the lender uses. Keep in mind that reporting can change over time as lenders update their agreements.
How On-Time Payments Can Help a Thin Credit File
If you have a thin credit file (few or no accounts), a short term loan that reports to the bureaus can be a powerful tool for building credit. Payment history is the single largest factor in your FICO score, accounting for 35 percent of the calculation. When you make on-time payments on a reported loan, you are demonstrating responsible credit behavior. Over time, this can raise your score and make it easier to qualify for better loan terms in the future.
However, not all short term loans are equally helpful. Installment loans that report to all three bureaus are the most beneficial because they show a consistent payment pattern over several months. Payday loans that report on-time payments are less common, but when they do, they can still add positive marks. The key is to ensure the lender actually reports your good payments. Some lenders only report negative information, which means your on-time payments do nothing for your score while a single missed payment could hurt you. Always confirm reporting practices before you borrow.
For those with bad credit, a short term loan that reports to the bureaus can be a second chance. It allows you to rebuild your credit history step by step. But it requires discipline: you must make every payment on time. Missing a payment on a reported loan can set you back significantly. If you are considering this path, our guide on qualifying for a short-term cash loan even with bad credit offers practical tips for improving your approval odds while protecting your score.
How Missed Payments and Collections Can Hurt Scores
The flip side of credit reporting is the damage that missed payments can cause. If a lender reports to the bureaus, a late payment will appear on your credit report and can lower your score. Payment history is the biggest factor in your FICO score, so a single 30-day late payment can drop your score by 50 to 100 points, depending on your starting score. A collection account is even worse. If you default on a short term loan and the lender sends it to collections, that collection will appear on your report for up to seven years and can severely damage your credit.
Even lenders that do not report on-time payments may report delinquencies. This is a common practice among payday lenders. They may not bother to report your good payment behavior, but they will report when you default. That means you bear all the downside risk with none of the upside benefit. Before you take out any short term loan, ask the lender: do you report on-time payments? If the answer is no, you should be aware that the loan will not help your credit and could still hurt it if you fall behind.
Collections are particularly damaging because they signal to future lenders that you failed to repay a debt. Even if you pay the collection off later, it remains on your report for seven years from the date of first delinquency. The negative impact diminishes over time, but it does not disappear. That is why it is critical to repay short term loans on time. If you are struggling, contact the lender immediately to discuss options. Many lenders would rather work out a payment plan than send an account to collections.
Checking Your Reports to Confirm What Was Reported
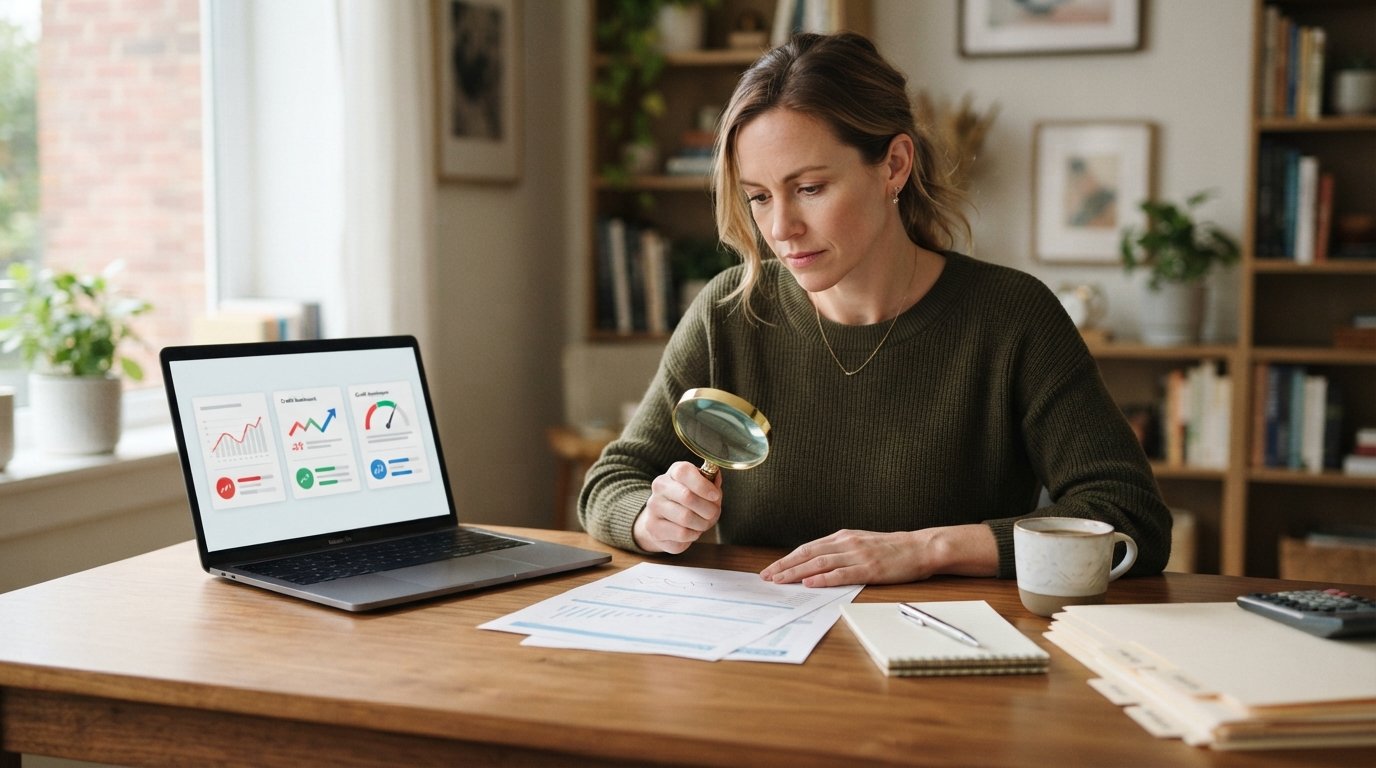
The only way to know for sure whether a short term loan is being reported is to check your credit reports. You can get free reports from all three bureaus at AnnualCreditReport.com. Review each report carefully for the name of the lender and the loan amount. If the loan appears, check the payment history to see if on-time payments are being recorded. If it does not appear, the lender either does not report or reports to a different bureau. You may need to check all three reports to find it.
It is also a good idea to check your reports before applying for a loan so you know where you stand. If you see errors, dispute them with the bureau. Errors can lower your score and cost you money in higher interest rates. Once you have the loan, set a reminder to check your reports again after a few months to confirm that payments are being reported correctly. If you see a late payment that you believe is an error, dispute it immediately.
For those who want to explore short term loan options from a network of lenders, StartPaydayLoan is a free online connection service that helps U.S. consumers find short-term and payday loan options. Visitors complete one simple request form and may be matched with third-party lenders in our network. StartPaydayLoan is not a lender and does not make credit decisions; any loan terms come directly from the lender. The site also publishes plain-language guides on borrowing, budgeting, and credit. Using a connection service can help you compare offers from multiple lenders, but you should still ask each lender about their credit reporting practices before you accept an offer.
Frequently Asked Questions
Do all short term lenders report to the credit bureaus?
No. Reporting is voluntary for most lenders. Some report to all three bureaus, some to one or two, and some to none. Payday lenders are less likely to report than installment lenders or banks. Always ask the lender directly.
Can a short term loan help me build credit?
Yes, if the lender reports on-time payments to the bureaus. An installment loan that reports to all three bureaus and that you repay on time can improve your payment history and raise your score. However, not all short term loans report positive information.
Will a short term loan show up on my credit report if I default?
It might. Even lenders that do not report on-time payments may report delinquencies or send your account to collections. A collection account can appear on your report for up to seven years and significantly damage your score.
How do I find out which bureaus a lender reports to?
Ask the lender before you apply. You can also check your free credit reports at AnnualCreditReport.com after you take out the loan. If the loan appears on one report but not others, you will know which bureau the lender uses.
What if my loan is not on any of my credit reports?
If the loan does not appear on any of your three reports, the lender likely does not report to the major bureaus. That means your on-time payments will not help your credit score, but a default could still be reported to a specialty agency or a collection bureau.
Understanding whether short term loans report to all three credit bureaus is essential for making informed borrowing decisions. Before you sign, ask the lender about their reporting practices. Check your credit reports regularly. And remember that responsible borrowing, including making every payment on time, is the best way to protect and build your credit, regardless of whether the lender reports or not.