How to Spot a Predatory Loan Offer in a Lender Network
Spot predatory loan offers in a lender network by checking APR, balloon payments, renewal fees, and pressure tactics before you sign.
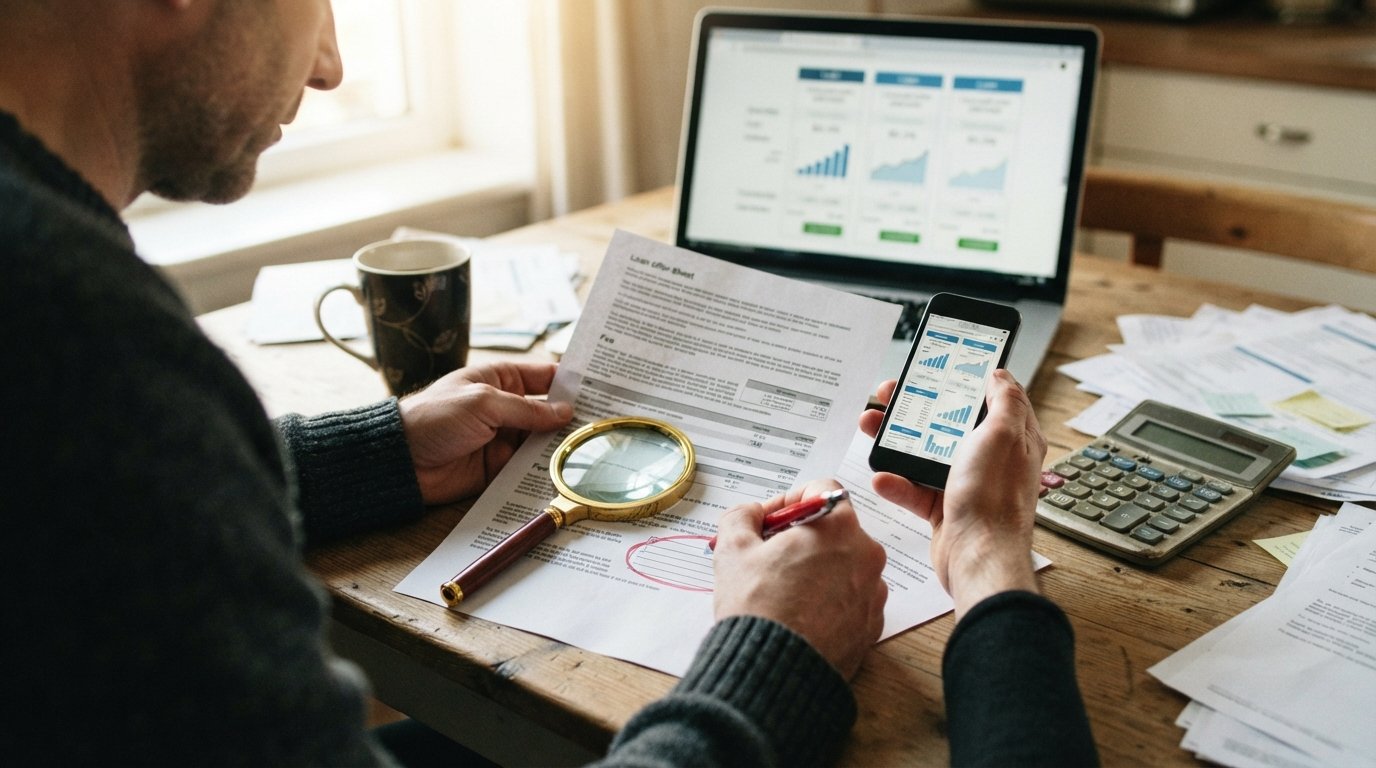
You submitted one request and now three lenders are competing for your business. That should feel like a win, but within those offers lurk terms that can turn a short-term fix into a long-term financial trap. Predatory lenders count on urgency and confusion, and a lender network can make it harder to compare because every offer arrives at once with different formats, fee structures, and fine print. Learning how to spot a predatory loan offer in a lender network is not about being cynical; it is about protecting yourself when you are already under pressure. This guide walks through the specific cost signals, contract clauses, pressure tactics, and questions that separate a fair offer from a dangerous one, so you can choose with your eyes open.
Why Predatory Offers Hide in Plain Sight Within Lender Networks
A lender network is a connection service, not a single bank. When you submit a request through a platform like express cash advance via lender networks, your information may be shared with multiple independent third-party lenders, each of which sets its own rates, fees, and repayment terms. That structure is convenient, but it also means no single entity is comparing offers for you. The network does not negotiate on your behalf, and it does not guarantee that every lender in the pool is offering a fair deal. Predatory actors know this and design their offers to look competitive at a glance while hiding the true cost in the details.
The first defense is understanding the incentive structure. Connection services are typically compensated when you submit your information, not when you get a good loan. That does not make them predatory by itself, but it does mean you are the only person in the transaction whose job is to read the terms carefully. A reputable service will be transparent about its role and will not pressure you to accept any specific offer. If a platform blurs the line between itself and the lender, or implies it can guarantee approval, treat that as a warning sign.
Predatory offers also thrive on information asymmetry. The lender knows exactly how the contract works; you are seeing it for the first time while you are stressed about rent, a car repair, or a medical bill. The tactics below are designed to exploit that gap. Recognizing them in advance turns a confusing pile of offers into a set of documents you can actually evaluate.
Cost Signals That Reveal a Predatory Loan
The clearest evidence of a predatory loan is in the numbers, but the numbers are often presented in ways that obscure the real cost. The annual percentage rate, or APR, is the single most useful figure because it standardizes interest and most fees into one annualized rate. A legitimate short-term loan will have a high APR compared with a mortgage, but a predatory offer pushes APR into territory that is wildly disproportionate to the amount borrowed and the time you have to repay. If an offer presents a flat fee or a per-$100 charge but never states the APR, that omission is itself a red flag.
Balloon payments are another classic signal. A balloon structure keeps monthly or biweekly payments low by deferring most of the principal to a single large payment at the end. If you cannot pay that balloon, you are forced to renew, and renewal is where predatory lenders make their money. Each renewal may add new fees, extend the debt, and reset the clock without reducing what you owe. A loan that can only be repaid by taking another loan is not a solution; it is a cycle.
Watch for these cost patterns when you compare offers:
- An APR that is dramatically higher than other offers for the same amount and term, with no explanation for the difference.
- Fees that are disclosed only in the fine print or only after you provide sensitive personal information.
- Repeated renewal or rollover fees that add to the balance without reducing principal.
- Prepayment penalties that punish you for paying the loan off early.
- Charges described as optional that are pre-checked or bundled into the total cost.
Any one of these signals deserves a closer look; two or more together should push you to walk away. The test is simple: can you state the total dollar cost of the loan, including every fee, before you sign? If the answer is no, the offer is not ready for your signature. A fair lender will put the total cost in writing and answer questions about it without hesitation.
Contract Terms That Limit Your Ability to Pay Early or Dispute Charges
Predatory contracts often look reasonable on the surface but contain clauses that quietly remove your leverage. Prepayment penalties are among the most damaging. A legitimate lender may charge interest for the time you borrowed, but a predatory contract can impose a fee for paying off the loan ahead of schedule, which removes the main way a borrower can reduce cost. If paying early costs more than paying on time, the contract is designed to keep you in debt.
Arbitration clauses and class-action waivers are subtler. These provisions can require you to resolve disputes through a private arbitrator rather than in court, and they can prevent you from joining other borrowers who were harmed by the same practice. Some contracts also include wage assignment or automatic withdrawal authorizations that are difficult to revoke. If a lender can take money from your paycheck or bank account without a clear, simple way for you to stop it, you have lost control of your cash flow.
Other clauses to examine closely include confession-of-judgment provisions, which allow a lender to obtain a judgment against you without a trial, and broad authorization to contact your employer or references. A fair contract will describe exactly what the lender can and cannot do, and it will give you a clear path to dispute a charge. If the dispute process is buried, one-sided, or requires you to waive basic rights, treat the offer as predatory regardless of how attractive the headline rate appears.
Pressure Tactics and Unclear Fee Disclosures
Predatory lenders manufacture urgency because urgency short-circuits comparison. You may receive a message saying the offer expires in minutes, that funds are reserved only if you act now, or that a limited number of borrowers qualify. A legitimate lender can tell you how long an offer stands without threatening you. Pressure to decide before you have read the terms is a tactic, not a courtesy, and it is one of the most reliable signs that the offer will not survive careful scrutiny.
Unclear fee disclosure often accompanies that pressure. The lender may quote a monthly payment that excludes origination fees, processing charges, or insurance products, so the amount you actually receive is smaller than the amount you repay. Some offers present a weekly or biweekly payment to make the cost feel smaller, knowing that borrowers compare the number to a monthly budget. Others disclose the APR only in a linked document that is easy to miss on a phone screen. The rule is straightforward: if the full cost is not visible on the offer itself, ask for it in writing before you proceed.
Pressure can also come through repeated contact. A lender that calls, texts, or emails repeatedly after you have asked for time to review is not respecting your decision-making process. You are never obligated to accept an offer, and a connection service that is transparent about its role will make that clear. For borrowers who want a straightforward way to compare options from independent lenders, services such as FundingCashLoans let you submit one request and review offers on your own timeline, with the reminder that terms always come from the lender and never from the connection platform.
Questions to Ask Before Accepting Any Offer
The most effective way to spot a predatory loan is to interrogate the offer before you accept it. A fair lender expects questions and answers them directly. A predatory lender deflects, rushes, or provides vague responses. Use the following questions as a checklist, and do not sign until you have clear answers in writing.
- What is the APR, and what is the total dollar cost of this loan including every fee?
- What is the exact repayment schedule, and is there any balloon payment at the end?
- Are there prepayment penalties, renewal fees, or charges for paying off the loan early?
- What happens if I miss a payment, and how does the lender contact me and my references?
- Can I dispute a charge, and does the contract limit my right to go to court?
Ask for the answers in writing, and compare them across every offer you received. If one lender cannot or will not answer a basic question about cost, that is your answer. You can also ask whether the lender reports to credit bureaus, which affects how the loan will influence your credit history, and whether there are any optional products bundled into the offer. A lender that is confident in its terms will welcome the questions; one that is not will try to move you past them.
It also helps to run the numbers yourself. Multiply the payment amount by the number of payments, add any fees paid upfront, and compare that total to the amount you actually receive. If the difference is larger than you expected, you have found the real cost. This simple calculation exposes offers that look cheap on a per-payment basis but are expensive overall, and it gives you a concrete basis for negotiating or walking away.
Where to Report a Lender You Believe Is Acting Unfairly
If you encounter a lender that uses deceptive disclosures, threatens you, or refuses to provide basic cost information, you have options. Start with your state attorney general's office and your state financial regulator, which license and oversee consumer lenders. The Consumer Financial Protection Bureau also accepts complaints about consumer financial products, including short-term loans, and can forward them to the company for a response. The Federal Trade Commission handles complaints about deceptive practices, and your state's licensing database can help you confirm whether a lender is authorized to do business where you live.
Keep records before you report: save the offer documents, screenshots of the disclosures, and notes on any phone calls, including dates and the names of representatives. These details make a complaint actionable. Reporting also protects other borrowers, because regulators track patterns across lenders and can act when complaints accumulate. If you believe you have been a victim of fraud, contact your bank immediately to discuss stopping automatic withdrawals, and consider placing a fraud alert or credit freeze with the major credit bureaus.
Finally, remember that walking away is a legitimate outcome. A lender network is a marketplace, not a mandate, and you are free to decline every offer and pursue alternatives such as a credit union loan, a payment plan with the original creditor, or help from a nonprofit credit counselor. The goal is not to find the fastest offer; it is to find an offer you can repay without damaging your finances further. When you know how to spot a predatory loan offer in a lender network, you keep the decision in your hands, where it belongs.