Emergency Cash When Payroll Error Delays Your Paycheck
Payroll error delayed your pay? Learn how to calculate your gap, compare fast funding options, and repay without starting a borrowing cycle.
By Mark Reynold
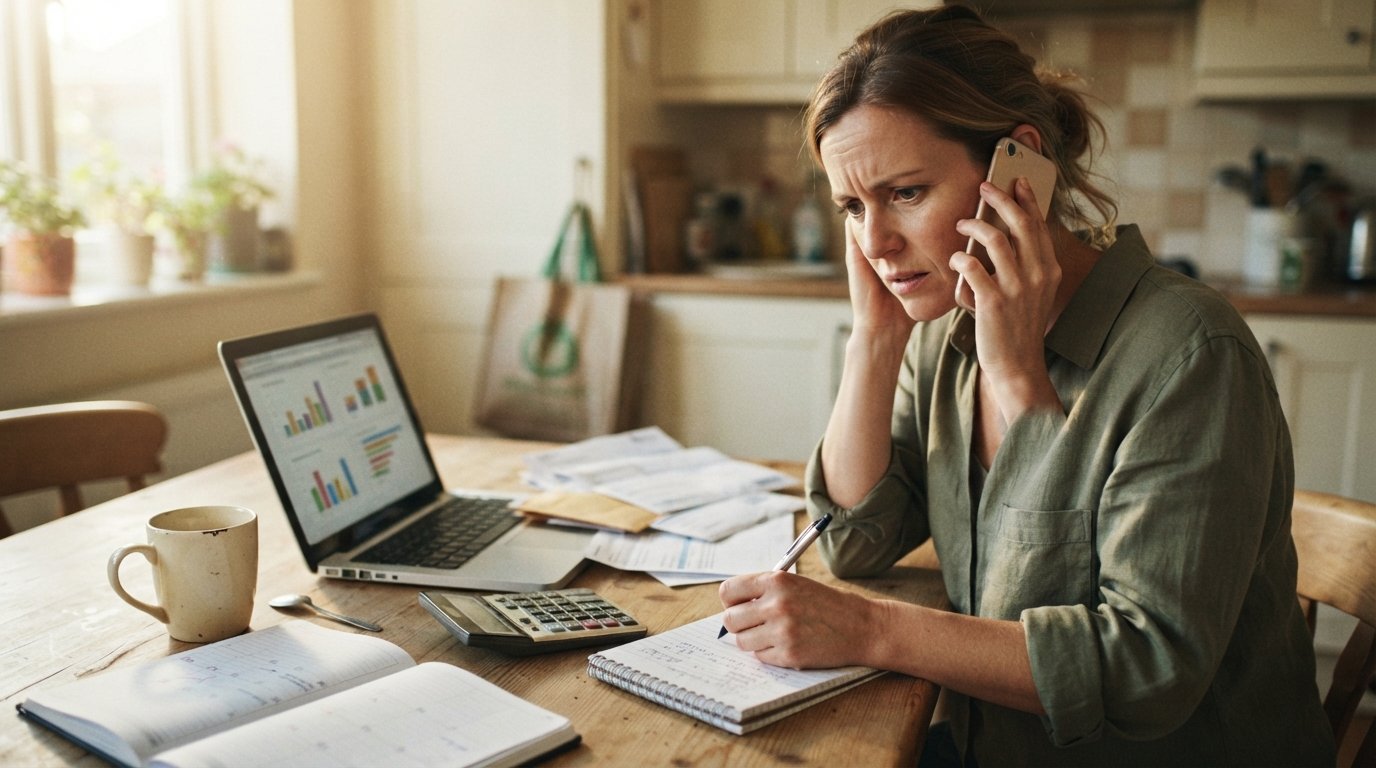
Your rent is due tomorrow, your electric bill is already past the grace period, and your checking account shows a balance that would not cover a tank of gas. Then you check your direct deposit and it is not there. The payroll department says a processing error delayed the run, and the money might arrive in three to five business days. You need emergency cash when your paycheck is delayed by payroll error, and you need it without creating a bigger financial problem next month. The good news is that you have more options than you think, and a clear sequence of steps can help you cover the gap safely.
The first rule is simple: do not panic-borrow. A delayed paycheck is a short-term cash flow problem, not a long-term income problem. Treat it that way by confirming exactly when the money will arrive, calculating the precise shortfall, and choosing the cheapest, fastest source of funds that you can realistically repay on your next payday. This guide walks you through that process, from the first call to HR to the moment you repay a short-term loan and close the loop.
Confirm the Delay and Get a Written Pay Date
Before you apply for any loan or cash advance, get the facts from payroll or human resources. Ask three specific questions: what caused the error, when will the corrected payment be issued, and will the payment be sent by direct deposit or paper check. A written confirmation, even an email, gives you a firm date to plan around and something to show a lender if you need to explain your situation. It also protects you if the delay stretches longer than promised.
While you are on the phone, ask whether the employer offers any kind of payroll advance or emergency assistance program. Some companies, especially larger employers, have a formal process for advancing earned wages when a payroll error occurs. This is usually the cheapest option because it involves no interest and no credit check. If your employer does not offer one, ask if the payroll team can expedite a manual check or a same-day wire. It never hurts to ask, and a written pay date from HR is valuable leverage when you talk to lenders.
Document everything in one place: the date of the error, the name of the person you spoke with, the promised pay date, and the exact amount you are owed. This record helps you verify the deposit when it arrives and gives you a clear timeline for repaying any short-term borrowing.
Calculate the Gap, Not the Whole Check
Most people over-borrow in a payroll delay because they think in terms of their missing paycheck instead of their actual shortfall. Your goal is to cover only the essential expenses that will bounce or incur late fees before the money arrives. That number is usually much smaller than a full paycheck.
List your obligations due before the confirmed pay date and separate them into must-pay and can-wait categories. Must-pay items typically include rent or mortgage, utilities at risk of shutoff, minimum debt payments, insurance premiums, and any medication or childcare costs. Can-wait items include subscription renewals, discretionary spending, and non-urgent home repairs. Add up only the must-pay total, then subtract any cash you already have available. The difference is your borrowing target.
For example, if your paycheck is delayed by four days and you have $180 in checking, you may only need $400 to cover rent and a utility bill, not the full $1,200 you expected to earn. Borrowing $400 instead of $1,200 cuts your fees and makes repayment far easier when the paycheck lands. Keep a small buffer of $50 to $100 if your budget allows, because delays sometimes stretch by a day or two.
Ask for Grace Periods Before You Borrow
Before you take on any debt, make a few quick calls to the companies you owe. Many landlords, utilities, and credit card issuers will grant a short grace period or waive a late fee if you explain that a payroll error delayed your pay and give them a specific date. This step costs nothing and can reduce or eliminate your need to borrow at all.
Be direct and specific: say that your employer confirmed a payroll error, give the corrected pay date, and ask for a few extra days or a fee waiver. Ask for the accommodation in writing if possible. Even if only one or two bills can be pushed, you reduce the amount you need to borrow and the fees you pay. If you do need a loan, having already reduced your gap means you can request a smaller amount and repay it faster.
Compare Fast Funding Options for a Short Gap
Once you know your gap and have asked for grace periods, compare the realistic options for emergency cash when your paycheck is delayed by payroll error. Speed matters, but cost and repayment terms matter more. The table below summarizes the trade-offs.
- Employer payroll advance: Usually free or low cost, but not all employers offer it and approval can take a day or two.
- Credit union small-dollar loan: Lower rates than payday products, but membership and approval may take longer than you have.
- Credit card cash advance: Fast if you have available credit, but fees and high interest apply immediately.
- Online lender network: Fast requests and potential next-business-day funding, but terms vary by lender and should be reviewed carefully.
- Friends or family: Often the cheapest option, but it requires a clear written repayment plan to protect the relationship.
For many workers facing a payroll error, an online lender network is the most practical route because it can present multiple offers from third-party lenders after a single request. If you want to understand how these products work before you apply, our guide on emergency cash advances explains when they make sense and how to use them safely. The key is to request only your calculated gap and to review the repayment schedule before you accept any offer.
How Fast Can You Actually Get Funds?
Speed is the main reason people search for emergency cash when their paycheck is delayed by payroll error, so it helps to understand the realistic timeline. An online request through a connection service can take a few minutes to complete, and lender offers may be presented within minutes depending on the network and your information. If you accept an offer, funding speed depends on the lender, your bank, and the time of day. Some lenders can fund as soon as the next business day, while others take longer.
To move quickly, have your basic information ready: government-issued ID, proof of income, a checking account in your name, and your contact details. Apply earlier in the day and on a business day when possible, because bank processing slows on evenings and weekends. Avoid applying with multiple direct lenders at once, which can create duplicate inquiries and confusion. A single request through a reputable connection service is usually the cleaner path.
If you decide to explore this route, you can request short-term loan options through a free connection service that matches U.S. consumers with third-party lenders. Remember that any connection service is not a lender, does not make credit decisions, and cannot guarantee approval. All terms, rates, and fees come from the lender you choose.
Choose the Shortest Affordable Repayment Term
The most common mistake in a payroll delay is choosing the longest repayment term because the payments look smaller. A longer term means more interest and more chances to fall behind. Since your paycheck is expected within days, choose the shortest term you can comfortably afford based on your confirmed pay date.
Before you accept an offer, calculate the total repayment amount, not just the payment. Compare the total cost of a one-payment option versus a multi-payment option, and check whether early repayment is allowed without a penalty. If your paycheck arrives on Friday and the loan is due the following Friday, a single-payment product may be the cheapest choice, provided you are confident the deposit will arrive. If there is any chance the pay date slips, choose a term that gives you a small cushion rather than the absolute shortest option.
Set a reminder to repay the loan the day your paycheck lands. Paying early, or at least on time, protects your credit and keeps the loan from becoming a recurring expense. If the lender offers automatic repayment, confirm the date and make sure your account will have the funds.
Avoid a Repeat Borrowing Cycle When Payday Arrives
The real risk in a payroll delay is not the first loan, it is the second one. When your paycheck finally arrives, it may feel smaller than expected because you are repaying the loan plus fees. If you have not planned for that, you may borrow again before the next payday and start a cycle that is hard to break.
Prevent this by building the repayment into your budget before the money arrives. When the deposit hits, repay the loan first, then cover your essential bills, and only then consider discretionary spending. If your budget is tight, ask the lender about a repayment plan before you miss a payment rather than after. Most lenders would rather work with you than send the account to collections.
After the crisis passes, take two steps to protect yourself from the next payroll error. First, build a small emergency fund, even $500, so a few days of delayed pay does not force you to borrow. Second, keep a written record of your payroll contacts and pay dates so you can act quickly if it happens again. A payroll error is usually a one-time event, but the financial habits you build during the recovery can last much longer.
Finally, if you are comparing options and want to understand the full range of short-term products, use educational resources and read the lender's terms line by line. The right choice for emergency cash when your paycheck is delayed by payroll error is the one that covers your gap, fits your confirmed pay date, and leaves you in a better position when the money finally arrives.