Saving Money for Taxes When You Are Self Employed
Build a tax reserve from every payment and avoid surprise IRS bills. Call (833)-501-3363 for guidance on saving money for taxes when you are self employed.
By Tessa Caldwell
Your best month as a freelancer can turn into your worst quarter if you spend every dollar that lands in your account. Self-employment income arrives without withholding, so the tax burden that employees never see is entirely your responsibility. The fix is not complicated: build a repeatable system that moves a slice of every payment into a dedicated tax account before you touch the rest. Do that, and a tax bill stops being a crisis and becomes a routine expense you already planned for.
Why Saving Money for Taxes When You Are Self Employed Feels So Hard
When you work for an employer, federal income tax, Social Security, and Medicare come out of each paycheck automatically. When you work for yourself, none of that happens. You receive the full amount, and the full amount feels like yours. That psychological gap is the root of most self-employment tax pain. The money you owe was never really yours, but nothing in the payment process reminds you of that.
Self-employed workers also carry the full 15.3 percent self-employment tax on net earnings, covering both the employee and employer halves of Social Security and Medicare. On top of that sits federal income tax, and depending on your state, state income tax as well. A freelancer netting $60,000 might owe $12,000 to $18,000 across those obligations. If that number is not set aside incrementally, it arrives as a lump sum that can feel like an emergency.
The solution is behavioral more than mathematical. You need a system that treats tax money as untouchable the moment it hits your account, plus a calendar that tells you exactly when the IRS expects payments. The rest of this guide walks through both.
Set Aside a Percentage of Every Payment You Receive
The single most effective habit for saving money for taxes when you are self employed is percentage-based setting aside. Instead of calculating what you owe at year end, you skim a fixed share off every payment as it arrives. The percentage does not need to be perfect. It needs to be automatic and slightly conservative.
A common starting point is 25 to 30 percent of gross receipts. That range covers the 15.3 percent self-employment tax plus a reasonable federal income tax estimate for many middle-income filers. If you live in a state with income tax, add another 4 to 6 percent. If your income is high enough to push you into a higher federal bracket, increase the percentage accordingly. The goal is to over-save slightly, because a small surplus at filing time is far easier to handle than a shortfall.
Here is a simple workflow that works for most freelancers and gig workers:
- Open a separate savings account labeled clearly as a tax account, ideally at a different bank than your checking account.
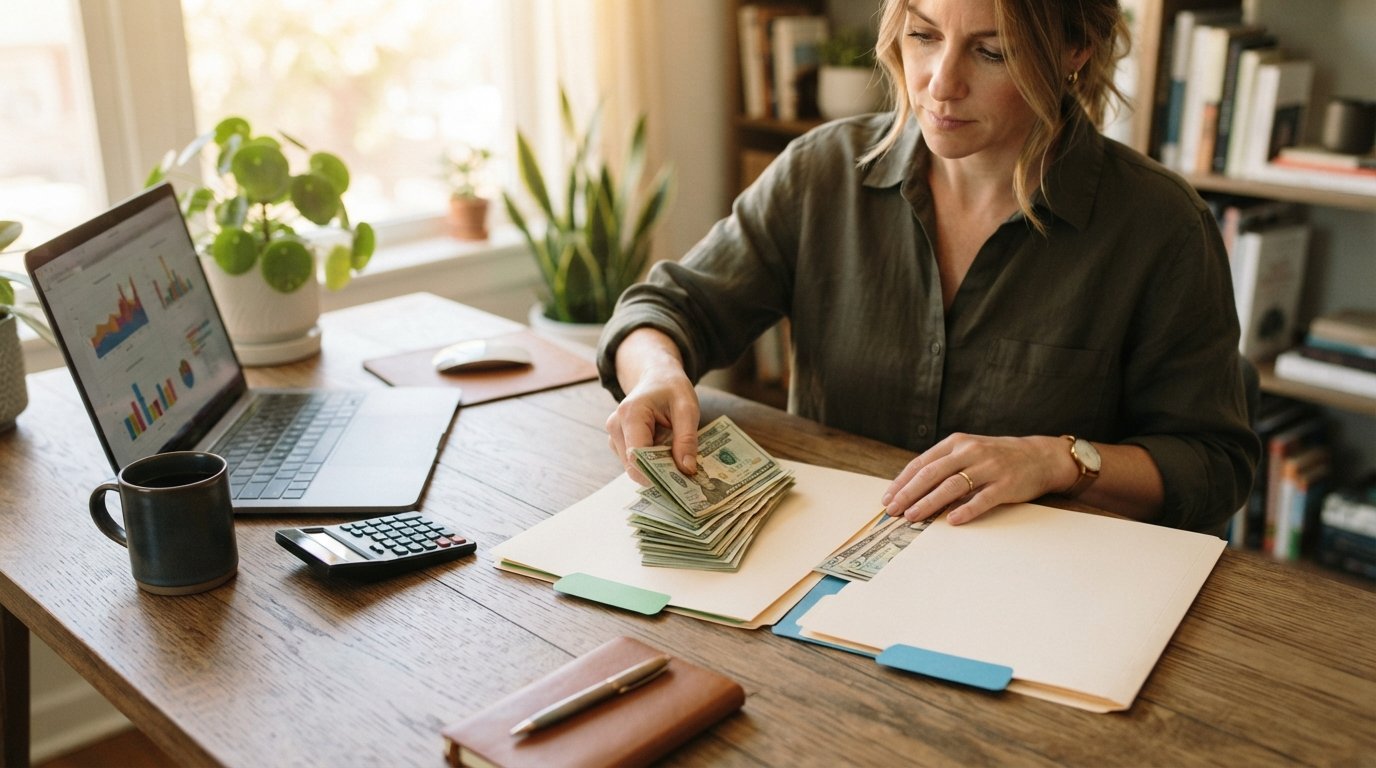
- When a client payment arrives, immediately transfer your chosen percentage into the tax account before paying any other bill.
- Log the transfer in a simple spreadsheet or accounting app so you can see your running tax reserve at a glance.
- Review the percentage every quarter and adjust it if your income or deductions change significantly.
The separate account matters more than it sounds. Money that sits in your everyday checking account gets spent, because it looks available. Money in a labeled tax account creates a mental barrier that protects it. Many freelancers also set up automatic transfers through their bank so the percentage moves the same day a payment clears, removing willpower from the equation entirely.
Plan Around Quarterly Estimated Tax Deadlines
The U.S. tax system is pay-as-you-go, and self-employed workers satisfy that requirement through quarterly estimated payments. Missing these deadlines can trigger underpayment penalties even if you pay your full balance in April. Knowing the schedule in advance lets you time your saving and avoid surprises.
Estimated payments are generally due on April 15, June 15, September 15, and January 15 of the following year. Each payment covers income earned during a specific period, so the January payment covers the final quarter of the prior year. If a deadline falls on a weekend or holiday, it moves to the next business day.
You have two ways to calculate each payment. The safe harbor method lets you pay 100 percent of last year's tax liability (110 percent if your adjusted gross income exceeded $150,000) in equal installments, which protects you from penalties regardless of how much you earn this year. The annualized income method calculates each payment based on actual earnings for that quarter, which suits freelancers with lumpy income. Whichever method you choose, mark all four dates on your calendar now and set reminders two weeks ahead so transfers from your tax account happen on time.
If your self-employment income is unpredictable, consider pairing your tax reserve with a short-term borrowing backup for the months when a client pays late and a quarterly deadline still arrives. Services like advance cash options for self-employed workers can bridge a timing gap, but they should never replace the reserve itself, only cover a temporary mismatch between when cash arrives and when the IRS expects it.
Keep Tax Savings Separate From Your Emergency Fund
Blending tax money with emergency savings is one of the most common mistakes self-employed workers make. The two pools serve different purposes and follow different rules. Your tax reserve is a liability you already owe; your emergency fund is protection against events you cannot predict. When they share an account, a car repair can quietly consume money that belonged to the IRS, and the shortfall surfaces months later with penalties attached.
Treat them as three distinct buckets: operating cash for business expenses, a tax reserve, and a personal emergency fund. Fund the tax reserve first on every payment, because the obligation is certain. Then direct a smaller percentage, often 5 to 10 percent, into the emergency fund until you have three to six months of essential expenses saved. What remains is yours to spend or reinvest.
Labeling each account clearly and reviewing balances monthly keeps the boundaries intact. If you ever need to borrow from the tax reserve, record it as a loan to yourself and repay it before the next quarterly deadline. That discipline protects you from the scenario where a tax bill becomes an emergency loan request.
What to Do When a Tax Bill Arrives Before Savings Exist
Many self-employed workers discover their tax obligation only when the return is filed, and by then the balance is due. If that happens, do not panic and do not ignore the notice. The IRS offers payment plans, called installment agreements, that let you pay over time with modest fees and interest. Applying online takes minutes, and setting up a plan stops the clock on aggressive collection while you rebuild.
Before agreeing to any plan, file your return on time even if you cannot pay in full. The failure-to-file penalty is far steeper than the failure-to-pay penalty, so filing protects you from the worst of the damage. Pay whatever you can with the return, then request a plan for the remainder.
If the balance is large and you have no reserve at all, a short-term loan can cover the gap while you restructure your saving system, but only if you can repay it within a few months. Platforms that connect borrowers with short-term lenders, such as 4Payday, exist for exactly this kind of timing crunch. Use them as a bridge, not a habit, and only after you have confirmed the total cost of borrowing against the penalty and interest the IRS would charge. In most cases the IRS plan is cheaper, so compare both before deciding.
Rebuilding Your Buffer After Covering a Tax Shortfall
Once the immediate bill is handled, the real work begins: rebuilding the reserve so the same shortfall does not repeat next year. Start by raising your set-aside percentage temporarily, perhaps to 35 percent, until the reserve reaches at least one quarter of your expected annual tax liability. Treat that rebuilt reserve as a floor you never spend below.
Next, tighten the feedback loop between income and saving. Review your profit and loss statement monthly, not annually, so you notice when income rises and your percentage needs to climb. If you use accounting software, set up a rule that automatically tags every client deposit and calculates the suggested transfer. Automating the decision removes the moment where you might talk yourself out of saving.
Finally, build a small cushion beyond the tax reserve itself, enough to cover one quarterly payment if a client pays late. That cushion is what separates a stressful April from a routine one. Self-employed workers who maintain both a tax reserve and a modest buffer rarely need emergency borrowing for taxes at all, and when they do, the amounts are small and short-lived.
Saving money for taxes when you are self employed comes down to three habits: skim a percentage off every payment, respect the quarterly calendar, and keep tax money physically separate from everything else. Start with the next payment you receive, even if the percentage is modest at first. The system compounds, and after two or three quarters the tax bill stops feeling like a threat and starts feeling like a bill you already paid.