How to Lower a Short Term Loan Payment When Income Drops
Income dropped and your loan payment is due? Learn how to lower a short term loan payment when income drops with lender negotiation and restructuring tips.
By Emily Parker
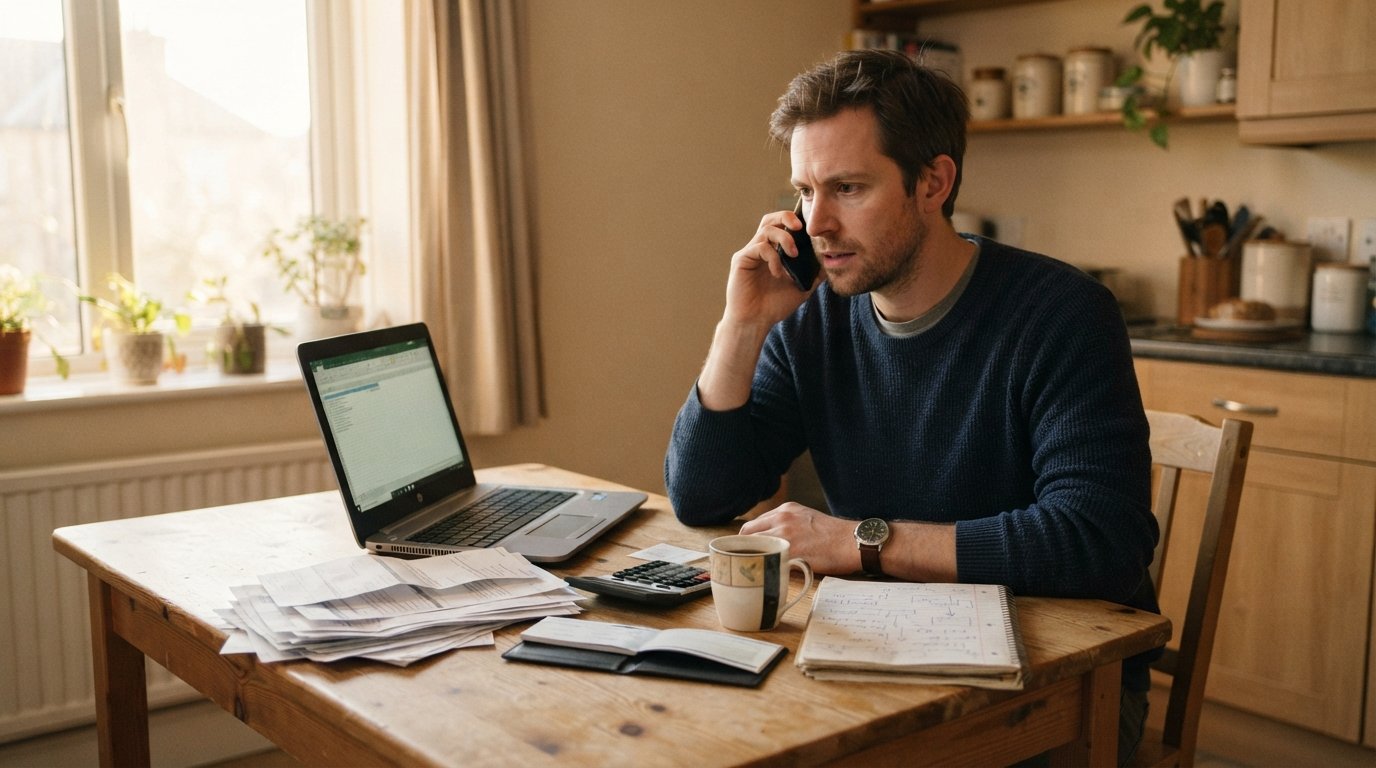
Your paycheck shrinks, your hours get cut, or a job disappears, and suddenly that short term loan payment that felt manageable now looks impossible. The worst move is to ignore it and hope the problem resolves itself. The best move is to act before the due date, talk to your lender, and explore every legitimate option for reducing what you owe each month. This guide walks you through practical, proven steps for how to lower a short term loan payment when income drops, including how to negotiate, what to say, and when restructuring makes more sense than borrowing again.
Why Contacting Your Lender Early Beats Waiting
The single most important thing you can do when your income falls is to call your lender before you miss a payment. Lenders have heard this story before, and many have formal hardship programs or at least some flexibility built into their collections process. But that flexibility tends to shrink once you are already delinquent. A borrower who calls two weeks before the due date and explains a temporary income disruption is in a far stronger position than one who goes silent for 30 days and then calls after a missed payment has been reported.
Early contact also protects your credit score. Payment history is the largest factor in most credit scoring models, and a single 30-day late payment can drop a good score by 50 to 100 points. By reaching out before the due date, you give yourself a chance to arrange a modified payment, a deferment, or a partial payment plan that keeps the account current. Even if the lender cannot reduce the total amount owed, they may be able to shift the due date or split the payment into smaller pieces, which keeps your record clean.
There is also a psychological benefit. Avoidance breeds anxiety, and anxiety leads to poor decisions like taking out a second loan at a worse rate to cover the first. Making the call puts you back in control. Prepare a short script: state your name and account number, explain that your income has dropped, give a brief reason (reduced hours, medical issue, layoff), and ask directly what options are available to lower your payment temporarily. Specificity helps. Saying "I can pay $75 every two weeks starting next Friday" is far more persuasive than "I cannot pay."
Repayment Options Lenders May Offer and How to Ask for Them
Not every lender advertises hardship options, but many have them. The key is knowing what to ask for and framing your request around your ability to pay something rather than nothing. Below are the most common arrangements that short term lenders, installment loan servicers, and payday lenders may offer to borrowers facing a temporary income drop.
- Payment extension or deferment: The lender pushes your due date back by two to four weeks, often for a fee. This buys time without a missed payment appearing on your credit report.
- Interest-only payment: You pay just the finance charge for one or two cycles, keeping the principal balance steady while your income recovers.
- Partial payment plan: You make a smaller payment now and the remaining balance is rescheduled, sometimes with a small extension fee.
- Installment conversion: If you have a lump-sum payday loan, the lender may convert it into a series of smaller installments, which lowers each individual payment.
- Fee waiver or reduction: Some lenders will waive a late fee or extension fee if you ask politely and explain your situation before the due date.
When you ask, be direct and collaborative. Try something like: "I want to pay this loan, but my income dropped unexpectedly. Can we set up a partial payment plan or extend the due date so I can catch up when my hours return?" Avoid demanding language. Lenders respond better to borrowers who present a realistic plan. If the first representative says no, ask politely to speak with a supervisor or hardship department. Policies vary by agent, and escalation often unlocks options that front-line staff cannot authorize.
Get every agreement in writing, even if it is just a confirmation email. Verbal promises are difficult to enforce, and you want a record of the new due date, the reduced amount, and any fees. If the lender offers a plan that still feels unaffordable, say so. A plan you cannot sustain is worse than no plan because it leads to another missed payment and possibly a canceled hardship arrangement.
Partial Payment vs. Missed Payment: How Each Affects Your Credit
Many borrowers wonder whether making a partial payment is better than skipping the payment entirely. The answer depends on how the lender reports to the credit bureaus, but in most cases a partial payment is better than nothing. A missed payment, meaning the full amount due is not received by the due date, is typically reported as late. A partial payment may still be reported as late, but it demonstrates good faith and often prevents the account from being sent to collections immediately.
Here is the practical breakdown. If your payment is $200 and you can only afford $80, call the lender first and ask if they will accept $80 as a partial payment under a documented arrangement. If they agree, that arrangement may protect your credit because the lender has agreed to modified terms. If you simply send $80 without calling, the lender may apply it to fees or interest and still report the full payment as missed. The phone call is what changes the credit outcome.
Missed payments have cascading consequences. After 30 days late, most lenders report to the credit bureaus. After 60 to 90 days, the account may be charged off or sent to a collection agency, which damages your score further and can lead to lawsuits or wage garnishment in some states. A partial payment plan, even one that lasts only two or three months, keeps the account in good standing and gives you breathing room to stabilize your income.
One more consideration: some lenders report only whether the payment was made on time, not the amount. In those cases, a partial payment that is accepted under a formal arrangement counts as on time. Always ask the lender how they will report the arrangement to the credit bureaus. If they cannot confirm, assume the worst and prioritize keeping the account current through whatever means you can afford.
When to Restructure Versus Request a New Loan
When income drops, two paths emerge: restructure the existing loan or take out a new one. Restructuring is almost always the better first move. It preserves your credit, avoids new fees, and keeps you from digging a deeper hole. But there are situations where a new request, through a connector like StartPaydayLoan, may make sense, particularly if you can replace a high-fee payday loan with a lower-cost installment loan. The key is to compare the total cost of each option, not just the monthly payment.
Restructuring works best when your income drop is temporary and you expect to recover within one to three months. In that scenario, a deferment, extension, or partial payment plan bridges the gap without adding new debt. Restructuring also works when the lender is willing to convert a lump-sum loan into installments, which can cut your monthly obligation significantly. Ask specifically: "Can you convert this to an installment plan with smaller payments?" Some lenders will, especially if you have a history of on-time payments.
A new loan request may be appropriate when the existing loan has terms that are fundamentally unaffordable even after a modification, or when you can qualify for a significantly lower interest rate. For example, replacing a two-week payday loan with a six-month installment loan can reduce the monthly payment even if the total cost is similar. However, be cautious: taking a new loan to pay an old one is refinancing, and it only helps if the new terms are genuinely better. If you are simply moving debt around and adding fees, you are worsening your situation.
Before requesting a new loan, calculate the total repayment cost of both options. Add up all fees, interest, and charges. Compare that total to what you would pay under a restructuring plan. If the new loan costs more in total but lowers your monthly payment enough to avoid default, it may still be worth it, but go in with eyes open. Also consider whether a new loan request will trigger a hard credit inquiry, which can temporarily lower your score. If you are already struggling, protecting your credit score matters.
If you decide to explore new options, use a connector that lets you compare offers from multiple lenders rather than applying to several directly. Each direct application may trigger a separate credit inquiry. A single request through a matching service can streamline the process and reduce the impact on your credit. AdvanceCash.com operates as a loan-connecting service, not a lender, and can match you with third-party lenders who may offer installment loans or other products with lower monthly payments. Remember that all loan terms, rates, and fees are set by the individual lenders, and approval is never guaranteed.
How AdvanceCash Fits as a Connector, Not a Servicer
Understanding the role of a loan connector is important when you are trying to lower a payment. AdvanceCash.com is not a lender and does not service loans. It does not set your payment amount, collect your payments, or decide whether to approve a modification. Those decisions belong entirely to the third-party lender that funded your loan. If you already have a loan through a lender you found via AdvanceCash, you must contact that lender directly to discuss hardship options. AdvanceCash cannot modify your existing agreement.
Where AdvanceCash does help is in the shopping phase. If you and your lender cannot reach a workable restructuring agreement, or if your existing loan is simply too expensive to maintain, AdvanceCash can connect you with lenders who may offer alternative products. The service is free to use, and you are under no obligation to accept any offer. You submit one request, and participating lenders may present offers. This can be useful if you want to compare installment loan options that might carry a lower monthly payment than your current obligation.
Keep expectations realistic. A new loan is not a fix for a fundamental income problem; it is a bridge. If your income has dropped permanently, you may need to adjust your budget, seek additional income, or explore credit counseling. A short term loan, whether new or restructured, should be a temporary tool, not a long-term solution. AdvanceCash publishes plain-language guides on borrowing and budgeting to help borrowers make informed decisions, and those resources are worth reviewing before you commit to any new debt.
For borrowers who are already behind, a payment plan may be the best path forward. Our guide on payday loan payment plan options when you cannot repay explains how to negotiate a plan and what to expect. The principles are similar: communicate early, propose a realistic amount, and get the agreement in writing.
Building a Short-Term Plan You Can Actually Sustain
Lowering a payment is only useful if the new payment fits your reduced income. Before you agree to any arrangement, build a bare-bones budget for the next two months. List your essential expenses: housing, utilities, food, transportation, insurance, and minimum debt payments. Subtract those from your reduced income. The remainder is what you can realistically offer your lender. Do not promise more than that, even if the lender pressures you. A sustainable partial payment is better than an unsustainable full payment that fails next month.
Consider temporary income sources as well. Gig work, part-time shifts, selling unused items, or negotiating a temporary reduction in other bills can free up cash to put toward the loan. Every dollar you free up reduces the amount you need to defer or restructure. If you have multiple debts, prioritize the one with the highest risk of default or the highest fees. Secured debts like a car loan may take priority because losing the vehicle would make it harder to earn income.
Finally, protect yourself from predatory quick fixes. When income drops, high-cost emergency loans can look tempting, but they often deepen the problem. If you must borrow, borrow from the lowest-cost source available and have a clear repayment plan. Avoid rolling over payday loans or taking multiple loans simultaneously. If you feel overwhelmed, nonprofit credit counseling can help you build a debt management plan, sometimes with reduced interest rates negotiated by the counselor. The important thing is to keep moving forward with a plan, not to freeze in place.
Income drops are stressful, but they are often temporary. By calling your lender early, asking specifically for hardship options, understanding how partial payments affect your credit, and carefully weighing restructuring against new borrowing, you can lower your short term loan payment without wrecking your financial future. The steps are within your control, and the sooner you take them, the more options you will have.