Cut Monthly Costs to Free Up Loan Repayment Cash
Use reducing monthly expenses to free up loan repayment money with a practical audit and negotiation plan. Call (833)-501-3363 for guidance.
By Alex Thompson
Your loan payment is due in two weeks, and the number in your checking account is smaller than you hoped. You are not alone. Millions of Americans juggle loan payments alongside rising rent, grocery bills, and utility costs. The good news is that you do not need a second job to find breathing room. A systematic approach to reducing monthly expenses to free up loan repayment money can uncover hundreds of dollars you already earn but never see. This guide walks you through a practical audit, negotiation tactics, due-date flexibility, and the discipline to keep those savings working for you long after the loan is paid off.
Start With a Subscription and Recurring Charge Audit
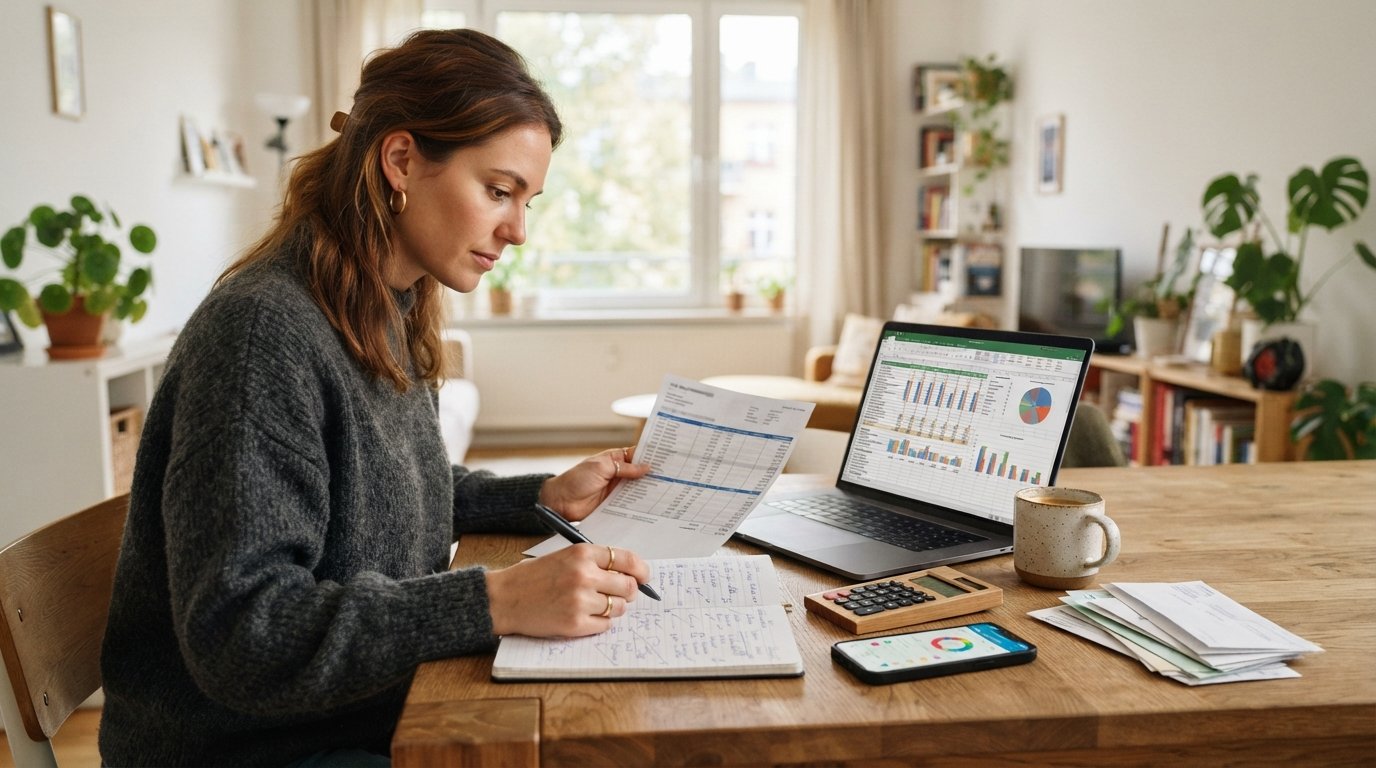
The fastest way to find hidden money is to list every recurring charge that hits your bank account or credit card. Most people underestimate this number by 20 to 30 percent. Pull the last two months of statements and highlight every automatic payment, from streaming services and gym memberships to app subscriptions, cloud storage, and insurance premiums. Group them into three buckets: essential, useful but negotiable, and forgotten.
Once you have the list, apply a simple rule. Cancel anything in the forgotten bucket immediately. For the useful but negotiable bucket, set a 14-day pause or downgrade to a cheaper tier. Many services offer a basic plan that covers 90 percent of what you actually use. Essential subscriptions, such as car insurance or phone service, should not be canceled but can often be renegotiated or bundled. The goal is not deprivation. It is aligning your spending with what you truly value so that loan repayment becomes a priority.
Here is a practical framework for the audit:
- List every recurring charge from the past 60 days, including annual fees divided by 12.
- Mark each charge as essential, useful, or forgotten.
- Cancel forgotten charges the same day and request refunds where possible.
- Pause or downgrade useful charges for 30 days to test whether you miss them.
- Renegotiate essential charges by calling the provider and asking for a loyalty or retention rate.
After one pass, most households find $50 to $150 per month in savings. That money should be redirected to your loan payment immediately, not absorbed into general spending. If you need a temporary bridge while you complete the audit, a short-term option like advance cash loans for unexpected expenses can cover an urgent bill, but the audit is the long-term fix.
Renegotiate or Pause Non-Essential Services
Many service providers build retention offers into their customer service scripts. You simply have to ask. Call your internet provider, cell phone carrier, gym, and insurance company. State that you are reviewing your budget and considering cancellation. Ask for the retention department and request a lower rate, a promotional discount, or a temporary hardship plan. Success rates are higher than most people expect, especially if you have been a customer for more than a year and have a good payment history.
For services you cannot cancel outright, ask about seasonal holds. Gyms often allow a three-month freeze for a small fee. Streaming services let you pause for up to 90 days. Even your car insurance may offer a low-mileage discount if you are driving less. Each pause or discount frees up cash for loan repayment without permanently removing the service from your life.
Consider bundling where it makes sense. Combining home and auto insurance, or internet and mobile phone service, can reduce the total monthly outlay by 10 to 25 percent. The key is to compare the bundled price against the sum of your current individual bills. Do not accept the first offer. Ask for the promotional rate and confirm the price after the promotional period ends.
Shift Bill Due Dates to Match Your Cash Flow
Sometimes the problem is not the total amount you owe but the timing. If your loan payment is due on the same day as rent and utilities, your account may dip into overdraft even when your monthly budget is balanced. Many lenders and service providers allow you to change your due date. Call each creditor and ask to move due dates to the days immediately following your paycheck. This simple change can prevent late fees and give you more control over your cash flow.
Prioritize the loan payment. If your loan servicer reports to credit bureaus, on-time payments help your score. Moving the due date to a lower-stress day of the month reduces the risk of an accidental late payment. For bills that cannot be moved, set up autopay for the minimum amount on the original date and schedule a second payment for the remainder after your next paycheck.
Keep a simple calendar or spreadsheet that maps income dates against bill due dates. Identify the weeks where outflows exceed inflows and adjust due dates accordingly. This is not about borrowing more money. It is about matching the money you already have to the obligations you already owe.
Direct Freed-Up Money to the Loan First
Finding savings is only half the battle. The other half is making sure those savings actually reduce your loan balance. Open a separate savings account labeled "loan payoff" and set up an automatic transfer for the exact amount you cut from your monthly expenses. Treat that transfer like a bill. If you found $120 in subscription cuts, transfer $120 to the loan payoff account on the same day you would have paid those subscriptions.
Then make a lump-sum payment toward your loan principal. Confirm with your lender that extra payments are applied to principal rather than future interest. Some loans have prepayment penalties, so ask before you pay extra. If your loan allows it, a biweekly payment schedule can also accelerate repayment without feeling like a major sacrifice. You can read more about managing short-term obligations responsibly at 4Payday, a resource for understanding payday and installment loan options.
Use a simple priority order for the freed-up cash:
- Cover any past-due loan amounts to stop late fees and credit reporting.
- Pay the current month's loan installment on time.
- Apply extra money to the principal of the highest-interest loan.
- Build a small emergency buffer of $500 to $1,000 to avoid future borrowing.
This order protects your credit, reduces interest over time, and creates a cushion that prevents the next unexpected expense from derailing your progress.
Keep the Cuts After the Loan Is Repaid
The most common mistake is to celebrate a paid-off loan by restoring every canceled subscription and paused service. Within three months, the old spending pattern returns, and the next financial emergency feels just as urgent. Instead, keep at least half of the cuts in place and redirect that money to an emergency fund or a high-yield savings account.
Review your audit list every six months. Services raise prices, and new subscriptions creep in. A 30-minute review twice a year keeps your monthly expenses aligned with your goals. If you used a short-term loan to bridge a gap, use the repayment period as a training ground for permanent financial habits. The skills you build, tracking recurring charges, negotiating bills, and timing payments, will serve you long after the loan is gone.
Reducing monthly expenses to free up loan repayment money is not about living in scarcity. It is about making deliberate choices so that your income supports your obligations and your goals. Start with the subscription audit this week, make one negotiation call, and move one due date. Small actions compound quickly, and the relief you feel when the loan payment clears without stress is worth the effort.