What Happens After You Submit a Loan Request Online
Submitting a loan request online starts an instant, automated process. Here is what lenders check and how to compare offers before you accept.
By Alex Thompson
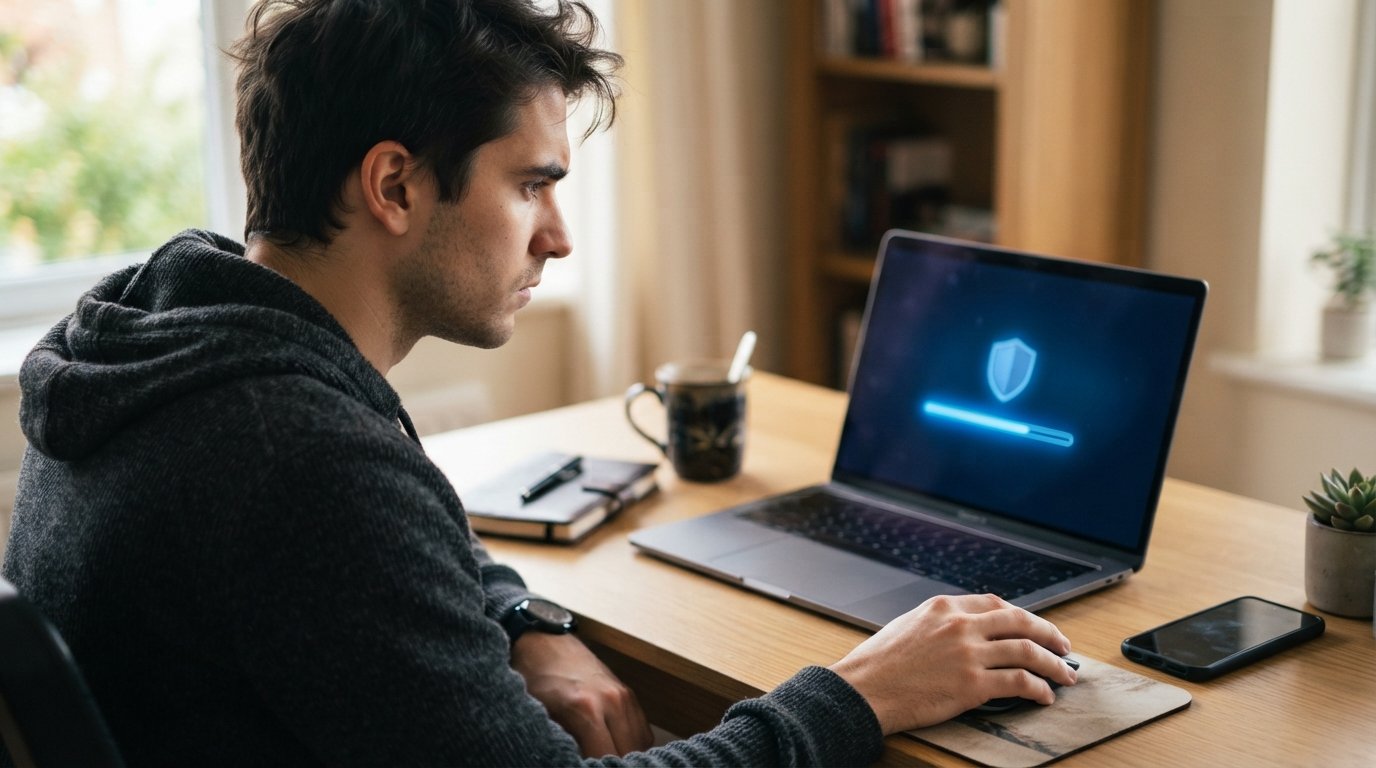
You hit submit on an online loan request, and the screen shifts to a message that says your information is being reviewed. Your stomach tightens a little because you need the money soon, and you are not sure what is happening behind that loading bar. The reality is that a specific, largely automated sequence kicks off the moment your form reaches a lender network, and understanding that sequence helps you spot legitimate offers, avoid wasted time, and protect your personal data.
This guide walks through each stage of the process used by loan-connecting platforms like CashLoanFunded, from the instant your request is encrypted and transmitted to the moment a lender deposits funds in your bank account. You will also learn what can slow things down, what lenders actually check, and what you should do if you receive multiple offers at once.
The First Few Seconds: Encryption, Consent, and Data Routing
The instant you click the submit button, your browser encrypts the information you entered, typically using 256-bit SSL technology, and sends it to the platform's servers. That encryption protects your name, address, income details, and Social Security number while the data travels across the internet. On the receiving end, the system logs your electronic consent, which is the legal permission lenders need to run credit and verification checks on you.
Within seconds, the platform formats your request into a standardized profile that third-party lenders can evaluate. This is not the same as a loan application with one bank. It is a single request that gets broadcast to a network of lenders who each apply their own criteria. Because these platforms are connectors and not direct lenders, they do not decide whether you qualify. They simply route your information to lenders who might be interested.
One detail that surprises many borrowers is how quickly your data moves. Some platforms report that initial matching begins in under a minute. That speed is possible because the system uses automated filters that compare your profile against each lender's basic requirements, such as minimum loan amount, state licensing, and income thresholds. If your request does not meet a lender's baseline, it is skipped without any human review.
During this stage, you may notice a soft credit pull, which does not affect your credit score, or you may be asked for additional consent for a hard inquiry later. The specific sequence depends on the platform and the lenders in its network. AdvanceCash.com, for example, states that its service is free to use and that submitting a request does not obligate you to accept any offer. That distinction matters because some borrowers assume that submitting a request is the same as accepting a loan. It is not.
How Lenders Evaluate Your Request Behind the Scenes
Once your profile reaches a lender, an automated underwriting engine takes over. This engine does not just look at your credit score. It examines a combination of factors that together paint a picture of your ability and willingness to repay. Lenders typically review your income, employment status, banking history, existing debts, and the amount you requested. They also check whether your state allows the loan product you are seeking, because payday and installment loan regulations vary widely across the United States.
Different lenders weigh these factors differently. One lender might approve a borrower with a 580 credit score because the income is steady and the requested amount is small. Another lender might decline the same borrower because its internal risk model prioritizes a longer credit history. This is why two people with similar financial profiles can receive different outcomes from the same loan request. It also explains why a single request can generate multiple offers, each with its own terms.
Here is a closer look at what lenders commonly verify during this evaluation:
- Identity and age: Lenders confirm you are at least 18 years old and a U.S. citizen or legal resident, since these are baseline legal requirements for most short-term loans.
- Income and employment: They check whether you have a reliable source of income, which can include a job, self-employment, benefits, or other regular deposits.
- Banking details: A valid checking account is often required so the lender can deposit funds and set up automatic repayment.
- Credit history: Lenders review your credit report, but many short-term lenders specialize in working with borrowers who have less-than-perfect credit.
- State eligibility: Some loan products are not available in every state, and loan amounts and fee structures are regulated at the state level.
This evaluation usually happens in minutes, but it can take longer if the lender needs to verify something manually. For instance, if your income comes from a less common source or your banking information does not match your application exactly, a human reviewer might step in. That manual review can add hours or even a full business day to the process.
It is also worth noting that lenders do not all respond at the same speed. Some return a decision almost instantly, while others take a few hours. The platform collects these responses and prepares to present them to you, usually on a single page where you can compare offers side by side. If no lender expresses interest, the platform will typically notify you that no offers are available, and you can decide whether to adjust your request or explore other options.
Receiving and Comparing Loan Offers
When lenders respond with offers, the platform displays them in a format that lets you review the key terms. You will typically see the loan amount, the annual percentage rate (APR), the repayment schedule, and any fees. This is the moment where careful reading pays off, because the lowest monthly payment is not always the cheapest loan. A longer repayment term can reduce your monthly payment but increase the total interest you pay over time.
You are not required to accept any offer. In fact, financial experts recommend comparing at least two or three offers before making a decision. Look beyond the headline number and examine the fine print. Does the loan have a prepayment penalty? Are there origination fees? What happens if you miss a payment? These details determine the true cost of borrowing.
If you are considering a cash advance product, it helps to understand the specific risks involved. In our guide on what happens if you miss a cash advance payment, we explain how late payments can trigger additional fees and affect your credit. That knowledge is valuable when you are comparing offers and deciding which repayment schedule you can realistically handle.
Once you choose an offer, the lender typically redirects you to its own website or portal to finalize the agreement. At that point, you are no longer dealing with the connecting platform. You are entering into a direct relationship with the lender, and all terms, rates, and fees are set by that lender. The platform's role ends once it connects you with the lender, although some platforms continue to provide educational resources or customer support.
Final Verification and Funding Timeline
After you accept an offer, the lender performs final verification steps. This can include confirming your identity, validating your bank account, and reviewing any documents you submitted. Some lenders use instant verification tools that connect directly to your bank, while others may ask for copies of pay stubs or bank statements. The speed of this step depends largely on the lender and how quickly you provide any requested information.
Once verification is complete, the lender initiates the funding process. If you are approved early in the business day and your bank participates in same-day or next-day ACH transfers, you could see funds in your account as soon as the next business day. However, weekends and holidays can delay the process, and some banks hold incoming deposits for a short period before making the money available.
It is important to set realistic expectations about timing. While many platforms advertise fast funding, the actual speed depends on the lender, your bank, and the time of day you complete the process. If you submit your request on a Friday evening, for example, the lender might not process it until Monday. Understanding this timeline helps you avoid unnecessary stress and plan accordingly.
Keep in mind that short-term loans are designed to be temporary solutions, not long-term financial fixes. They can be helpful when you face an unexpected expense and have no other immediate options, but they can also become expensive if you roll them over or miss payments. Before accepting any offer, make sure you have a clear plan for repayment that fits your budget.
What to Do If You Are Approved, Declined, or Receive No Offers
If you are approved, congratulations. Take a moment to review the final agreement one more time before signing. Confirm the repayment dates, the total amount you will repay, and the consequences of late payments. Set a reminder for your first payment so you do not accidentally miss it. If your lender offers automatic payments, consider whether that option works for your budget or whether you prefer to make manual payments.
If you are declined by all lenders, do not panic. A decline is not a permanent judgment of your financial health. It may simply mean that your profile did not match the criteria of the lenders in that particular network at that particular time. You can ask the lender for the reason for the denial, which is often provided in an adverse action notice. That information can help you identify what to improve before you apply again.
If you receive no offers at all, it may be because your requested amount or loan type is not available in your state, or because your income and banking details did not meet the minimum thresholds. In that case, you might consider adjusting your request, such as asking for a smaller amount, or exploring other financial options like credit union loans, payment plans with creditors, or assistance programs. The key is to avoid applying repeatedly in a short period, as multiple hard inquiries can affect your credit score.
Whether you are approved or not, protect your personal information throughout the process. Only submit your details on secure, reputable platforms, and never pay an upfront fee to receive a loan. Legitimate lenders do not ask for payment before funding. If something feels off, trust your instincts and walk away.
Understanding what happens after you submit a loan request online puts you in a stronger position to make informed decisions. You know that your data is encrypted, that lenders evaluate your profile using multiple factors, and that you have the right to compare offers before committing. That knowledge helps you borrow responsibly and avoid the traps that catch unprepared borrowers.