What Documents a Lender Needs for an Online Loan Request
Know exactly what documents a lender needs for an online loan request so your file is complete and your funding is not delayed by missing paperwork.
By Tessa Caldwell
You have probably seen the ads: apply online in minutes, get cash as soon as tomorrow. What those ads do not always show is the part where you scramble to find a pay stub, dig up your bank routing number, or realize your ID photo is too blurry to upload. The documents you provide during an online loan request are not busywork. They are the evidence lenders use to verify who you are, confirm you can repay, and decide how much risk they are taking on. Missing or messy paperwork is one of the most common reasons a request stalls, and in a market where speed matters, a single missing file can push your funding back by a day or more.
This guide walks through exactly what documents a lender needs for an online loan request, why some lenders ask for more than others, and how to prepare a clean file set before you ever hit submit. You will also see how the process works on a connection platform like AdvanceCash.com, where a single request can be reviewed by multiple third-party lenders, each with slightly different documentation standards. The goal is simple: help you avoid the back-and-forth so your request moves through review as smoothly as possible. For a broader look at how speed and process fit together, see this guide to fast online loans for quick cash.
The Core Document Set Most Lenders Expect
Across the short-term lending market, a fairly consistent baseline has emerged. Whether you are requesting a payday loan, a personal loan, or an installment loan, most lenders will ask for the same handful of items. These documents serve two purposes: they satisfy legal identity and anti-fraud requirements, and they give the lender a snapshot of your financial capacity. If you have these four categories ready, you are ahead of most applicants.
- Government-issued photo ID: A driver's license, state ID card, or passport. Lenders typically want a clear, color image showing your full name, date of birth, photo, and expiration date. Some also ask for a secondary proof of address, such as a utility bill or lease agreement.
- Proof of income: Recent pay stubs (usually the last 30 days), bank statements showing direct deposits, or benefit award letters. Self-employed applicants may need tax returns, 1099 forms, or profit-and-loss statements.
- Bank account details: A voided check, a bank statement, or a screenshot from your online banking portal showing your routing number and account number. This is how the lender verifies your account for potential funding and repayment.
- Contact information: Your full legal name, current address, phone number, and email. Some lenders verify your phone or email during the request, so use channels you can access immediately.
Having these items ready in digital form (clear photos or PDFs) makes the difference between a request that flows and one that gets flagged for manual review. Lenders are not trying to make the process difficult; they are matching the person in front of them to a verified identity and a realistic repayment profile. The faster you can supply clean documentation, the faster a lender can move toward a decision.
Why Income Verification Methods Vary Across Lenders
Income is the single most scrutinized part of an online loan request, and it is also the area where lenders differ most. A payday lender might accept a single recent pay stub and a bank statement, while a personal loan lender may want two months of bank statements or direct verification through a payroll or bank data service. The variation is not random. It reflects differences in loan size, repayment terms, underwriting models, and regulatory expectations.
Short-term lenders often rely on a combination of stated income and bank account activity. They may use third-party verification tools that connect to your bank account and confirm recurring deposits, or they may ask you to upload statements manually. Personal loan lenders, especially those offering larger amounts or longer terms, tend to apply stricter income analysis because their risk exposure lasts longer. Installment lenders fall somewhere in between, often requesting proof of income plus a check that your account can handle the scheduled payment.
This is why the same applicant can be asked for different paperwork by different lenders on the same day. On a connection platform, your single request may be reviewed by multiple lenders, each applying its own documentation standards. That is not a sign that something is wrong; it is a sign that underwriting is lender-specific. The practical takeaway is to prepare a slightly broader document set than the minimum, so you can respond quickly when a particular lender asks for an extra statement or a different income format.
Which Lenders Request Additional Paperwork and When
Most online loan requests are decided on the core document set, but some situations trigger additional requests. Knowing when extra paperwork is likely helps you decide what to have on hand and what questions to ask before you submit. The table below outlines common triggers and the documents that often follow.
- Self-employment or gig work: Lenders may ask for tax returns, 1099 forms, or bank statements showing consistent deposits. If your income arrives through multiple platforms, a summary sheet can help.
- Recent job change: A new employer may prompt a request for an offer letter or the first pay stub from the new job, especially if the lender cannot yet see a deposit history.
- Large loan amounts: Requests above a certain threshold often require more income documentation, such as two months of bank statements or direct verification through a third-party service.
- Thin or damaged credit: Lenders may look for additional proof of ability to repay, such as utility payment history or a co-signer, when credit data is limited.
- Address or identity mismatch: A recent move or a name change can trigger a request for a secondary ID or proof of address to resolve the discrepancy.
If you fall into one of these categories, gather the extra items before you start the request. A quick phone call or email to the lender's support team can confirm what they accept, which is far faster than submitting and waiting for a follow-up. The same principle applies on a connection platform: the more complete your initial file, the fewer rounds of clarification you will face.
How to Gather Documents Before Starting a Request
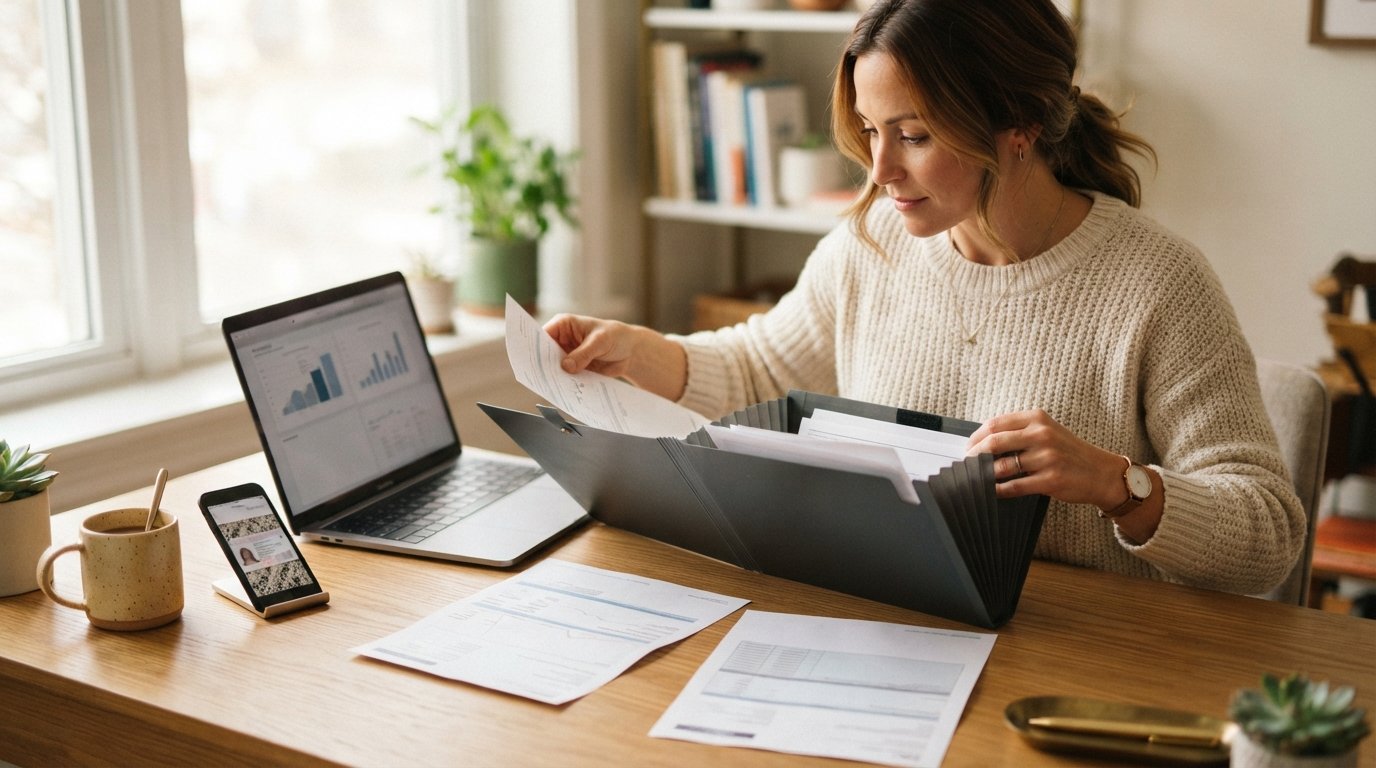
Preparation is the most underrated part of a successful online loan request. The applicants who move fastest are usually the ones who treated document collection as a separate task, completed before the application. A simple two-step approach works well: assemble a master folder, then tailor it to the lender.
- Create a digital loan folder: On your phone or computer, make a folder named something like Loan Documents. Save a color photo of your ID (front and back), your two most recent pay stubs, your two most recent bank statements, and a voided check or a screenshot of your account details.
- Check quality and dates: Make sure images are readable, not cropped, and not expired. Lenders often reject blurry or outdated files, and a rejected upload can add hours to your timeline.
- Write a one-page income summary: If your income is variable or comes from multiple sources, a short note listing each source, the amount, and the frequency can help a reviewer understand your situation quickly.
- Confirm the lender's preferred formats: Some lenders accept PDFs, some prefer photos, and some use secure upload portals. Check before you send anything by email, since email is not a secure channel for sensitive documents.
Once your folder is ready, the actual request takes far less time. You can copy the same files into multiple lender portals if needed, and you will not be caught searching for a statement while a review clock is ticking. This is especially valuable on platforms that route your request to several lenders, because each lender may ask for documents in a slightly different way.
Data-Safety Practices for Uploading Sensitive Files
Loan documents contain some of the most sensitive information you have: your ID, your income, and your bank account numbers. Treat every upload as a security decision. The safest approach is to use the lender's or platform's secure portal rather than email or text message, and to confirm that the site uses encryption before you upload anything.
Here are practical habits that reduce risk:
- Use secure, encrypted portals: Look for https in the address bar and a lock icon. Avoid sending documents as email attachments unless the lender explicitly provides a secure method.
- Redact what is not needed: If a document shows more than the lender requires (for example, a full bank statement with unrelated transactions), ask whether a redacted version is acceptable. Never redact the information the lender needs to verify.
- Share only with verified parties: Confirm the lender or platform's identity before uploading. On a connection service, the platform should clearly state that it is not a direct lender and that your information is shared with third-party lenders for review.
- Keep a record: Save a copy of what you submitted and when. If a dispute or question arises later, you will have a clear trail.
A reputable platform will explain how your data is used, who it is shared with, and what security measures are in place. If a site is vague about these points, that is a reason to pause. Your documents are valuable, and the lender you choose should treat them that way.
How the Document Check Fits Into the Online Request Process
Understanding the sequence helps you see why documents matter at each stage. On a typical connection platform, the process looks like this: you submit a single online request with your basic information, the platform shares it with third-party lenders, and interested lenders review it and may ask for documents. Each lender then makes its own decision and presents its own offer, including terms, rates, and fees. The platform itself does not make credit decisions or guarantee approval.
That structure explains why documentation can feel repetitive. You may upload a pay stub to one lender and a bank statement to another, even though both received the same initial request. Each lender is building its own file. The upside is choice: you can compare offers, and a document that satisfies one lender's stricter standard may unlock a better option from another. A service like LendersCashLoan works on a similar connection model, helping users submit one request to a network of third-party lenders. The key is to treat your document folder as a portable asset you can reuse across reviews.
Timing also matters. Some lenders can review a complete file and present an offer within minutes, while others take longer, especially if additional documents are needed. If speed is your priority, submit during business hours, use a stable internet connection, and have your files ready before you start. That combination gives you the best chance of moving through review without delays.
Common Document Mistakes That Delay Funding
Most delays are avoidable, and they usually come down to a few recurring mistakes. The first is submitting expired identification. A driver's license that expired last month will not pass verification, even if everything else is perfect. The second is using a bank statement that is too old or does not show the required deposit history. Lenders typically want recent statements, often from the last 30 to 60 days.
The third mistake is illegible images. A photo taken at an angle, with glare, or with the corner of the document cut off can be rejected even if the information is technically there. The fourth is inconsistent information: a name that does not match your ID, an address that differs from your bank statement, or a phone number you cannot verify. These mismatches trigger manual review, which adds time.
Finally, some applicants send documents through insecure channels because it feels faster. That can create a security risk and may not even reach the right reviewer. Stick to the lender's official portal or the platform's secure upload tool. If you are unsure, ask support before you send anything. A few extra minutes of care can save you a day of delay.
Frequently Asked Questions About Loan Documents
Can I use a screenshot instead of a bank statement?
Some lenders accept screenshots from online banking if they clearly show your name, account number, and the transaction history the lender needs. Others require an official PDF statement. Check the lender's instructions or ask support before submitting a screenshot, since acceptance varies.
What if I do not have pay stubs because I am self-employed?
Self-employed applicants typically provide tax returns, 1099 forms, or bank statements showing consistent business deposits. A profit-and-loss statement prepared by you or your accountant can also help. The goal is to demonstrate stable income, not necessarily a traditional paycheck.
How recent do my documents need to be?
Most lenders want identification that is currently valid and income or bank documents from the last 30 to 60 days. Some may accept older statements if they show a longer history, but recent is always safer. If your document is near the edge of the window, consider getting a newer version before you apply.
Is it safe to upload my ID and bank statements online?
It can be safe if you use a secure, encrypted portal and a reputable lender or platform. Look for https in the address bar, avoid email attachments, and confirm how your data will be used. If a site does not explain its security practices, treat that as a warning sign.
Preparing the right documents is one of the few parts of an online loan request you fully control. A clear ID, recent proof of income, accurate bank details, and verified contact information form the backbone of almost every review, and a little extra preparation covers the situations that trigger additional requests. Keep your files organized, upload them through secure channels, and treat your document folder as a reusable toolkit for every lender you engage with. That approach will not guarantee approval, since credit decisions and terms belong to individual lenders, but it will help you avoid the most common delays and put your best financial foot forward.