Using a Small Personal Loan to Cover a Utility Shutoff Notice
Using a small personal loan to cover a utility shutoff notice can restore service fast, but only if you confirm the exact past-due amount and choose a short term.
By Mark Reynold
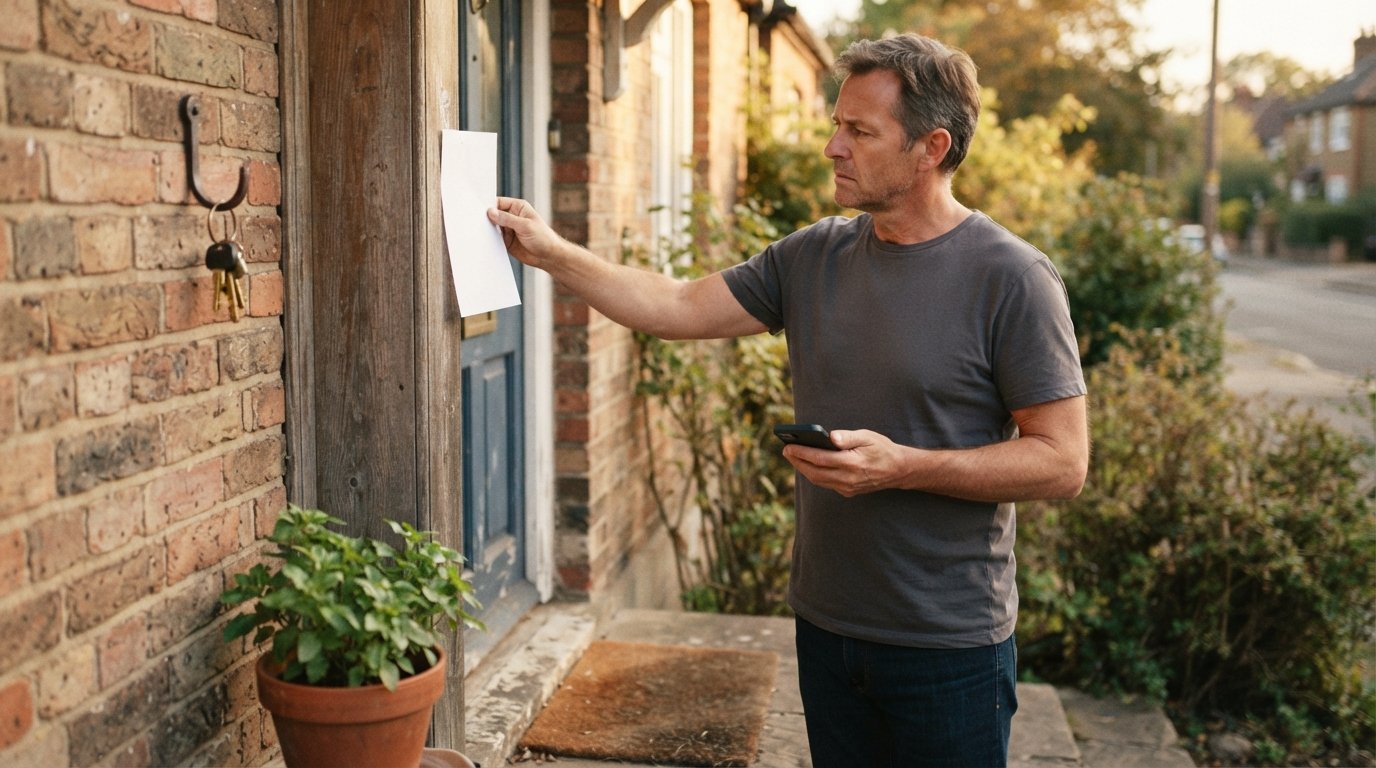
The shutoff notice is taped to your door, the due date is days away, and your bank account will not stretch far enough to cover the past-due balance. This is a scenario millions of U.S. households face each year, and the anxiety it creates can push people toward rushed decisions. Before you panic or pay a steep late fee, consider a practical middle path: using a small personal loan to cover a utility shutoff notice. A modest, short-term loan can clear the overdue bill, restore your service, and give you a structured repayment plan, provided you approach it with clear eyes and a plan.
This guide walks through the full playbook: calling the utility first, pinpointing the exact past-due amount, choosing a small loan with a short repayment term, and preventing the same shutoff from happening again next season. Along the way, you will see how a loan-connection service like Advance Cash vs Personal Loan can help you compare product types before you commit, and where a service such as StartPaydayLoan fits into the picture for borrowers exploring short-term options.
Call the Utility Before You Call a Lender
Your first call should be to the utility company, not a lender. Utilities in most states are required to offer some form of assistance before disconnection, and many have customer service teams trained to handle hardship cases. The conversation goes better when you are specific: give your account number, the shutoff date on the notice, and a clear statement of what you can pay today. Ask directly about three things: an extension, a payment arrangement, and any hardship or low-income assistance program you may qualify for. Utilities often prefer a partial payment plan over the administrative cost of shutting off service and later reconnecting it.
Ask whether the utility offers budget billing, which averages your annual usage into predictable monthly payments. This single change can smooth out seasonal spikes in winter heating or summer cooling costs and reduce the odds of another shutoff notice. If you qualify for the Low Income Home Energy Assistance Program (LIHEAP) or a state-level fund, the utility can usually tell you how to apply and whether a pending application pauses disconnection. In some states, a pending LIHEAP application legally protects you from shutoff during the review period.
Document the call. Write down the representative's name, the date, the arrangement you agreed to, and any confirmation number. If the utility agrees to hold off disconnection for a partial payment, get that in writing or by email. This record matters if the shutoff crew arrives anyway. Only after you know the utility's best offer should you decide whether a small personal loan is needed to cover the remaining gap.
Pin Down the Exact Past-Due Amount
A shutoff notice rarely reflects only the most recent bill. It usually bundles the past-due balance, the current month's charges, late fees, and sometimes a reconnection deposit. Borrowing the wrong amount creates two problems: you may borrow more than you need, paying interest on money you did not require, or you may borrow too little and still face disconnection. Call the utility and ask for a breakdown of every charge included in the shutoff total, then ask what the minimum payment is to keep service on. Those two numbers are often different.
Here is a simple way to organize the numbers before you request any loan:
- Past-due balance from prior months (the amount that triggered the notice)
- Current month's charges, if already billed
- Late fees and any reconnection or deposit amounts
- The minimum payment the utility will accept to avoid shutoff
- Any assistance, credit, or payment already applied to the account
That last item is easy to miss. If you made a partial payment or the utility applied a LIHEAP credit, the notice may be outdated. Confirm the live balance on the day you apply for the loan. Request only the minimum amount needed to satisfy the utility, plus a small buffer for the next bill if your budget allows. A small personal loan sized to the actual gap is far cheaper than a loan sized to the full notice with fees baked in.
Why a Small Loan With a Short Term Fits a One-Time Bill
A utility shutoff is usually a one-time cash flow problem, not a permanent income shortfall. That distinction should shape the loan you choose. A small personal loan with a short repayment term, often 3 to 12 months, keeps total interest low because you are not stretching the debt across years. The longer the term, the more interest accrues, even at a modest annual percentage rate. If you can repay the loan within two or three billing cycles, the total cost of borrowing stays manageable and the loan does not become a recurring monthly burden.
Compare that with alternatives. A credit card cash advance often carries a fee plus immediate interest and may not be available if your card is near its limit. A payday loan is designed to be repaid on your next payday and can become expensive if rolled over. A small personal loan from a lender in a connection network can offer a fixed payment schedule, which makes budgeting easier. The key is to read the loan agreement carefully: check the APR, the origination fee, the repayment schedule, and whether there is any prepayment penalty. A loan with no prepayment penalty lets you pay it off early and cut total interest.
Borrowers with less-than-perfect credit should know that approval is not guaranteed, but many lenders in these networks review more than just a credit score. Income, banking history, and the size of the request all factor in. A smaller loan request is generally easier to qualify for than a large one. If you are comparing product types and want to understand how cash advances differ from personal loans, a comparison resource can clarify the trade-offs before you submit a request.
How to Request a Small Personal Loan Without Overpaying
Once you know the exact amount and have the utility's arrangement in hand, the loan request itself should be deliberate. Gather your identification, proof of income, and bank account details, since most online lenders ask for these. Submit one request through a connection service rather than applying to multiple lenders individually, because multiple hard inquiries in a short window can ding your credit. A single request that matches you with lenders lets you compare offers side by side.
Follow these steps to keep the process clean and cost-effective:
- Confirm the live past-due amount with the utility and write it down.
- Decide the maximum monthly payment your budget can absorb.
- Submit one request for the minimum amount needed, not the maximum offered.
- Compare at least two offers on APR, fees, and repayment term.
- Accept the offer with the shortest term you can comfortably repay.
After you accept, set up automatic payments for the loan so you do not miss a due date, and pay the utility immediately once funds arrive. Keep the utility's confirmation that your account is current. If the loan funds arrive after the shutoff date, call the utility again with proof of payment; many will restore service quickly once payment posts. A loan-connection service does not make credit decisions or set terms; those come from the lender you choose, so read every disclosure before signing.
Avoid a Repeat Shutoff by Smoothing Utility Costs Year-Round
Paying off the shutoff notice solves today's problem, but the underlying pattern, seasonal bills that outpace your budget, will return unless you change how you pay for utilities. The most effective fix is budget billing, which the utility can set up so you pay roughly the same amount each month. The utility estimates your annual usage, divides it by twelve, and adjusts periodically. Winter heating spikes and summer cooling spikes stop wrecking your monthly cash flow, and you can plan around a predictable number.
Pair budget billing with a small utility buffer fund. Even $200 to $500 set aside specifically for utility bills can absorb a rate increase or a cold snap without a crisis. Build it gradually by transferring a fixed amount each payday, and replenish it after each use. If your income is irregular, consider paying a little extra toward the utility account during high-income months so your account carries a credit balance going into peak season. Many utilities allow this, and it functions as a forced savings plan with no bank account required.
Finally, review your usage and rate plan once a year. Ask the utility whether a different rate structure, a time-of-use plan, or an energy audit would lower your bills. Small efficiency changes, such as sealing drafts or adjusting the water heater temperature, reduce the base amount you owe each month. The goal is to make the shutoff notice a one-time event rather than a seasonal ritual. A small personal loan can bridge a genuine emergency, but predictable billing and a modest reserve are what keep the lights on for good.
Facing a utility shutoff is stressful, but you have more options than it first appears. Call the utility, confirm the exact amount due, and use a small, short-term personal loan only for the gap you cannot cover otherwise. Then put budget billing and a small reserve in place so the next notice never arrives. If you are ready to explore short-term borrowing options from third-party lenders, start with a single request and compare the terms before you commit.