Spotting Phishing Scams in Online Lending: 2026 Guide
Spotting phishing scams in online lending protects your data and money. Learn red flags, verification steps, and what to do if targeted.
By Sophia Hayes
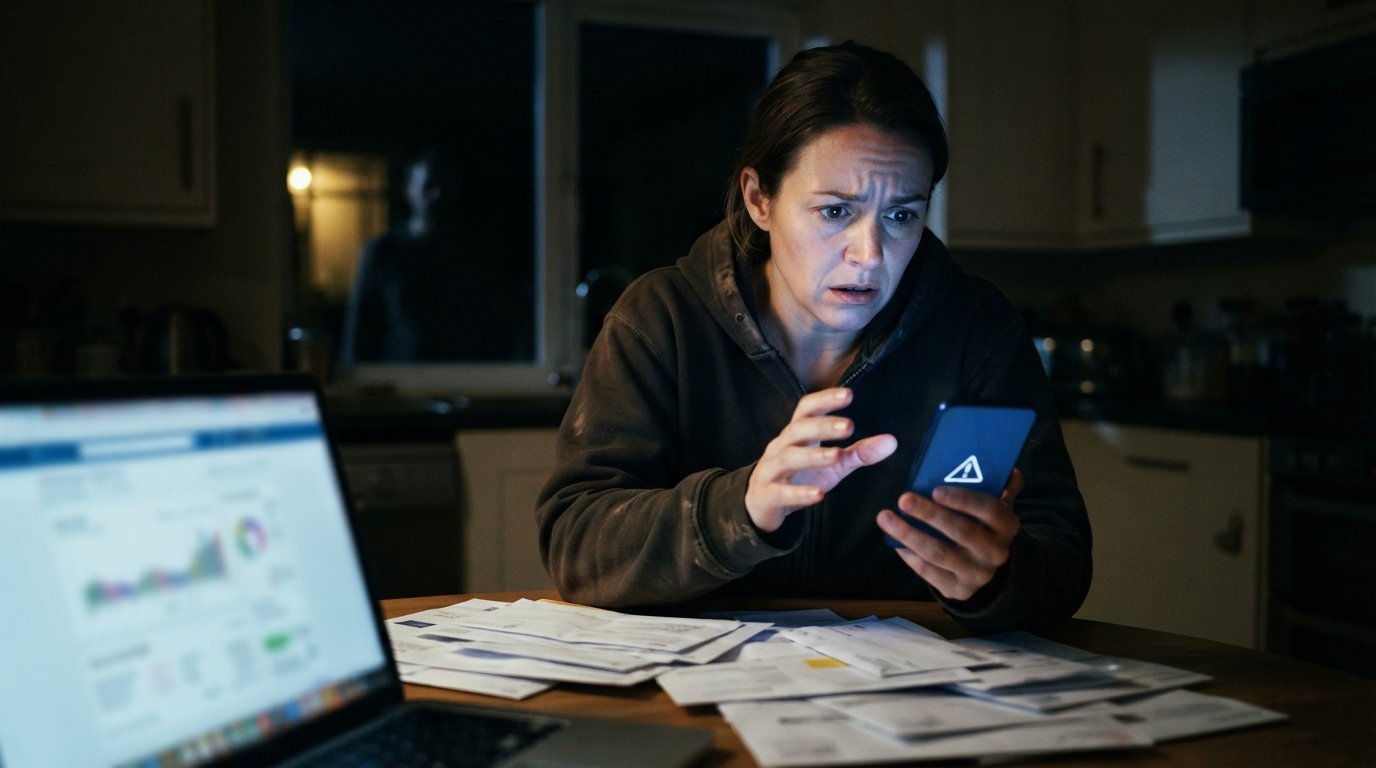
You get a text at 11 p.m. The message says your loan application was approved, but you never applied. It includes a link, a countdown timer, and a promise of $5,000 in your account within minutes. Your heart races because you do need money, and the offer feels like a lifeline. That is exactly the emotional state phishing scammers design their traps to exploit. In online lending, where urgency is already high and personal data is already in play, phishing attacks have become more convincing, more targeted, and more expensive for everyday borrowers. This guide shows you how to spot them before they cost you.
Why Online Lending Is a Magnet for Phishing Scams
Online lending combines three ingredients that scammers love: urgency, personal information, and money movement. Borrowers searching for a cash advance or a personal loan are often under time pressure. They are willing to share sensitive details such as Social Security numbers, bank account information, and income records. And they expect funds to move quickly, which means they may not pause to question a suspicious request.
Phishing in this space takes many forms. Some attacks impersonate well-known lenders or loan-connecting services. Others mimic government agencies, credit bureaus, or even your own bank. The common thread is a request for action: click this link, confirm this information, pay this fee, or call this number. Once you comply, scammers can steal your identity, drain your accounts, or charge you for a loan that never exists.
The rise of artificial intelligence has made these scams harder to detect. Emails and text messages now arrive with flawless grammar, realistic logos, and personalized details pulled from data breaches. A fake loan offer can look nearly identical to a legitimate one. That is why you need a repeatable verification process, not just a gut feeling.
Red Flags That Reveal a Phishing Loan Offer
Most phishing scams in online lending share recognizable warning signs. Learning to spot them quickly is your best defense. The following red flags should immediately raise your suspicion, especially if more than one appears in the same message.
- Guaranteed approval before any application. Legitimate lenders must review your information. A message that promises approval before you apply, or guarantees a specific amount regardless of credit, is almost certainly a scam.
- Requests for upfront payment. Real lenders deduct fees from the loan proceeds or disclose them in the agreement. They never ask you to pay an insurance fee, processing fee, or collateral deposit before releasing funds.
- Pressure to act immediately. Countdown timers, threats that the offer will expire in minutes, or claims that your account will be frozen are classic manipulation tactics.
- Links to unfamiliar websites. Hover over any link before clicking. If the domain does not match the lender's official website, or if it contains random characters, do not click.
- Requests for sensitive information by text or email. Legitimate lenders use secure portals. They do not ask for your full Social Security number, online banking password, or debit card PIN through an unsecured message.
One red flag alone might be a coincidence. Two or more together are a strong signal that you are dealing with a phishing attempt. Trust your instincts and verify through independent channels before taking any action.
How to Verify a Lender Before You Share Anything
Verification is the single most effective habit you can build. Before you provide personal information or pay any fee, take a few minutes to confirm that the lender is real and that the offer is legitimate. This step is especially important when you are using a loan-connecting service, because you may be matched with third-party lenders you have never heard of.
Start by checking the lender's official website directly, not through a link in the message. Look for a physical address, a phone number, and a privacy policy. Then cross-check the company with your state's licensing database or the Consumer Financial Protection Bureau. If the lender claims to be registered but you cannot find any record, walk away.
You should also verify the loan terms independently. Legitimate lenders provide a written loan agreement that clearly states the annual percentage rate, repayment schedule, and all fees. If you are asked to sign something that is missing these details, or if the terms change after you apply, that is a serious red flag. For a step-by-step walkthrough of how a safe online application should look, see our guide on how to apply for advance cash online. It explains what information a legitimate lender will and will not request.
Finally, never rely on a single point of contact. If someone calls you claiming to be from a lender, hang up and call the company's official customer service number. Scammers can spoof caller ID, so the number on your screen means nothing.
Protecting Your Personal and Financial Data
Even if you avoid a phishing link, your data can be exposed through other channels. Data breaches at lenders, retailers, and credit bureaus put millions of records into circulation every year. Scammers use that stolen information to craft highly convincing loan offers that reference your real name, address, or partial account numbers.
To reduce your risk, follow these data protection practices:
- Use unique passwords for every financial account. A password manager makes this easy and prevents one breach from compromising multiple accounts.
- Enable two-factor authentication. Even if a scammer steals your password, they cannot log in without the second factor.
- Monitor your credit reports regularly. Look for unfamiliar inquiries or new accounts. You can request free reports from each major bureau every week.
- Never share your online banking credentials. No legitimate lender needs your bank login to deposit funds. They use account and routing numbers, not your password.
- Freeze your credit if you suspect identity theft. A freeze prevents scammers from opening new accounts in your name.
These steps take a little time upfront, but they can save you weeks of frustration and thousands of dollars. If you are working with a loan-connecting platform like CashLoanFunded, confirm that the site uses encryption and has a clear privacy policy before you submit any information. Reputable platforms will explain exactly how your data is used and shared.
What to Do If You Have Been Targeted
If you clicked a link, shared information, or sent money to a suspected phishing scam, act quickly. The first 24 to 48 hours are critical for limiting the damage. Start by contacting your bank or credit union to freeze or close any compromised accounts. Then change your passwords for all financial accounts and enable two-factor authentication where possible.
Next, report the scam. You can file a complaint with the Federal Trade Commission at ReportFraud.ftc.gov, contact your state attorney general's office, and notify the lender or platform that was impersonated. If your Social Security number was exposed, consider placing a fraud alert or credit freeze with the major credit bureaus. You can also report the incident to the FBI's Internet Crime Complaint Center.
Document everything: save emails, text messages, screenshots, and any transaction records. This evidence will help you dispute fraudulent charges and support any investigation. Finally, monitor your credit reports for at least a year. Scammers sometimes wait months before using stolen data, so vigilance matters long after the initial incident.
Building Long-Term Defenses Against Loan Phishing
Phishing tactics evolve, but the core principles of protection remain constant. Stay skeptical of unsolicited offers, verify every lender independently, and never let urgency override your judgment. When you need a loan, start with a reputable loan-connecting service that connects you with multiple lenders and clearly discloses its role. AdvanceCash.com, for example, is a loan-connecting service, not a direct lender. It does not make credit decisions or guarantee approval. All loan terms, rates, and fees are set by third-party lenders, and the final agreement is between you and the lender you choose.
Understanding that distinction is itself a defense against phishing. Scammers often pose as direct lenders or claim to be affiliated with a service you trust. By knowing how legitimate platforms operate, you can spot the fakes more easily. A real service will never ask for an upfront fee, will never promise guaranteed approval, and will always direct you to a secure application process.
Education is your best long-term tool. Share what you learn with friends and family, especially older adults who are frequently targeted. The more people who know how to spot phishing scams in online lending, the harder it becomes for scammers to succeed. Stay cautious, verify before you trust, and protect your financial future one decision at a time.