Short Term Loan Request Denied: What to Do Next
A denied short term loan request is not the end. Learn what to do next, from fixing errors to finding alternative lenders. Call 8335013363 for guidance.
By Georgia Meyer
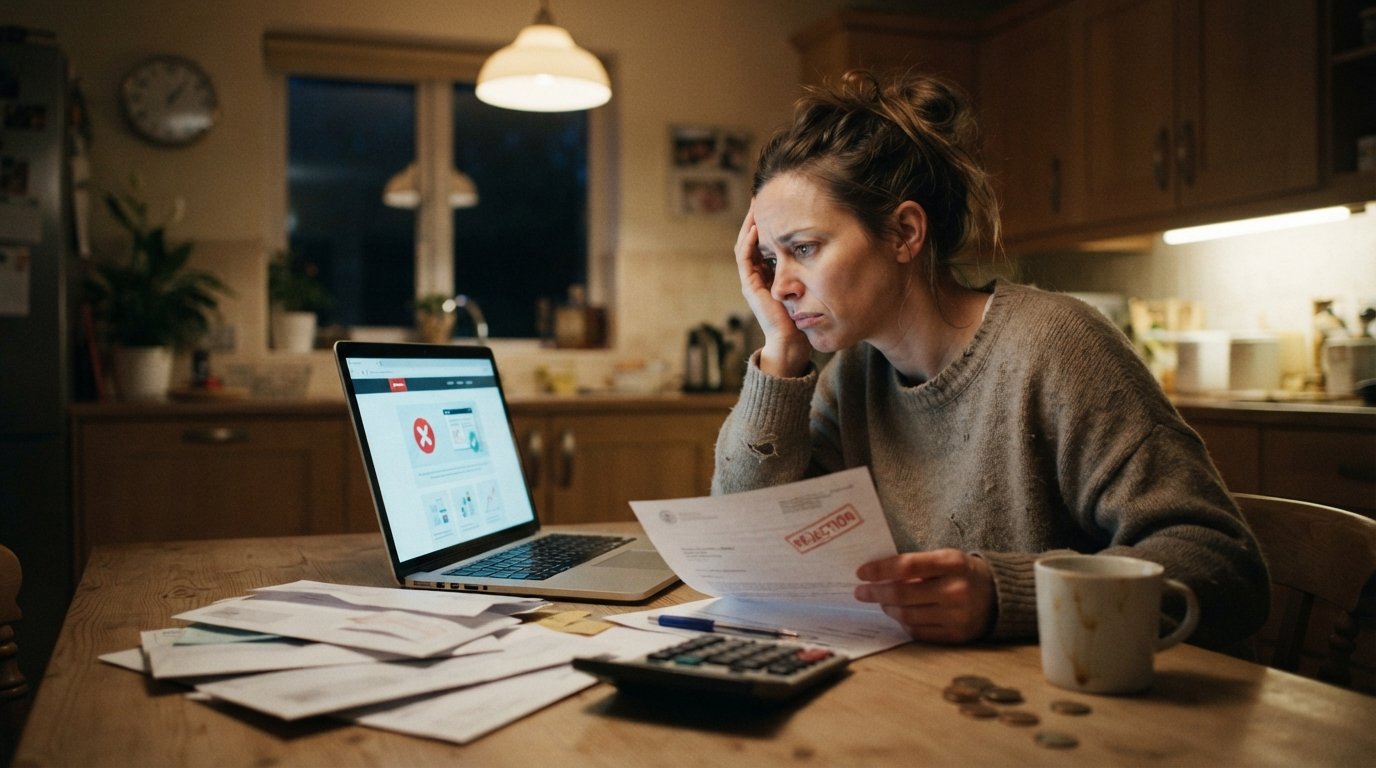
The email or screen message stings: your short term loan request was denied. Maybe an urgent bill is due, a car repair cannot wait, or a medical expense landed without warning. You applied expecting a quick decision, and now you are staring at a dead end while the clock keeps ticking. Before you panic, refresh the application, or call a dozen lenders in frustration, take a breath. A denial is not the end of your options. It is information, and you can use it.
The first thing to understand is that denial reasons vary widely. Some rejections come from a single red flag in your application, such as a recent late payment or an income figure that does not match the lender's minimum. Others reflect broader lending policies, state regulations, or the simple fact that the lender you chose does not serve your specific situation. Knowing which category your denial falls into tells you what to fix and where to look next.
This guide walks you through the practical steps after a short term loan request is denied. You will learn how to read a denial notice, correct application errors, improve your approval odds, and explore legitimate alternatives that can still put cash in your hands quickly. You will also see how a loan connection service like CashLoanFunded can match you with lenders who are more likely to say yes, even when your credit history is not perfect.
Why Short Term Loan Requests Get Denied
Lenders evaluate short term loan applications using a mix of credit data, income verification, and internal risk rules. When one of those factors falls outside their comfort zone, the system issues a denial. Common reasons include a credit score below the lender's cutoff, a debt-to-income ratio that signals you are already stretched thin, insufficient proof of income, or a checking account that has a history of overdrafts. Sometimes the issue is simpler: you applied for more money than the lender allows for your profile, or you live in a state where that particular loan product is restricted.
Another frequent culprit is incomplete or inconsistent information. If your stated income does not match what the lender sees in bank data, or if your address and phone number cannot be verified, the application may be rejected automatically. Some lenders also deny applicants who have an active short term loan with another provider, because they view multiple concurrent loans as a high-risk signal. Understanding these triggers helps you decide whether to reapply, adjust your request, or pivot to a different type of lender.
It also helps to know that denial does not always mean you are out of options permanently. Many lenders have different appetites for risk. One may decline you for a $500 payday loan while another approves a $1,000 installment loan with a longer repayment schedule. The key is to avoid firing off applications blindly, because each hard inquiry can further ding your credit. Instead, work through the steps below in order.
Step 1: Read the Denial Notice Carefully
When your short term loan request is denied, the lender is required by law to tell you why, at least in general terms. Under the Fair Credit Reporting Act, if the denial was based on information in your credit report, you must receive an adverse action notice. That notice will name the credit bureau used and explain your right to a free copy of the report. Read every line. Sometimes the reason is obvious, such as "insufficient credit history" or "income below minimum threshold." Other times the notice points to a specific credit account that you did not realize was in collections.
If the denial came from an online loan connection service rather than a direct lender, the message may be less specific. In that case, contact the service's support team and ask which lender or lenders reviewed your request and what criteria led to the rejection. Reputable platforms will at least tell you whether the issue was credit, income, or something else. This step is not about arguing the decision; it is about gathering the data you need to improve your next attempt.
Once you have the reason in hand, categorize it. Is it a fixable error (a typo in your income), a temporary setback (a recent late payment), or a structural issue (no credit history at all)? Your next move depends on which bucket it falls into. For a deeper look at how lenders price short term loans and why some applications fail on cost grounds, see our guide on what APR is and why it matters for short term loans.
Step 2: Fix Application Errors and Reapply Strategically
If the denial stemmed from a mistake on your application, you may be able to correct it and reapply with the same lender or a different one. Common errors include mistyped income, an old address, a phone number that does not match public records, or a bank account that was recently closed. Before you resubmit, pull your most recent bank statements and pay stubs so every number you enter is accurate. Double-check your name spelling, date of birth, and Social Security number. These small details matter more than most applicants realize.
If there was no error, you can still improve your odds by adjusting your request. Ask for a smaller loan amount, which lowers the lender's risk. Choose a longer repayment term if the lender offers one, because smaller payments fit more comfortably into your budget. If you applied for a payday loan, consider an installment loan instead; many lenders view installment products as less risky because they are repaid over several months rather than a single balloon payment. You can also add a co-signer if the lender allows it, though this puts someone else's credit on the line, so discuss it openly first.
Timing matters too. If you were denied because of a recent late payment, waiting even two or three weeks can make a difference if that payment is now current. If your credit report contains an error that dragged down your score, dispute it with the bureau and wait for the correction before reapplying. Each new application creates a hard inquiry, so space them out and only apply where you have a reasonable chance of approval.
Step 3: Strengthen Your Profile Before the Next Request
When you have a little time before you need funds, use it to shore up the weak spots that caused the denial. If your credit score was the issue, focus on the fastest levers: pay down revolving balances to lower your credit utilization, bring any past-due accounts current, and avoid opening new credit lines. Even a modest score improvement can move you from the decline pile to the approval pile at many short term lenders.
If income verification was the problem, gather stronger documentation. Lenders often accept recent pay stubs, bank statements showing consistent deposits, or benefit award letters. If you are self-employed or gig worker, a few months of bank statements may be required. Some lenders also look at your checking account behavior, so avoid overdrafts in the weeks before you apply. A steady balance, even a small one, signals that you can handle a repayment.
Another powerful step is to reduce your debt-to-income ratio. If you have multiple small loans or credit card balances, paying off even one can improve the ratio enough to qualify. You do not need to eliminate all debt; you just need to show the lender that you have room in your budget for one more payment. Keep in mind that short term loans are best used as temporary bridges, not long-term solutions, so the goal is to borrow only what you can comfortably repay on time.
Step 4: Explore Alternative Lending Options
If a direct reapplication is not realistic right now, turn to alternatives that serve borrowers with varied credit profiles. A loan connection service is often the fastest path, because it lets you submit one request and receive offers from multiple lenders who may have different approval criteria. AdvanceCash.com, for example, connects U.S. consumers with third-party lenders for payday loans, personal loans, and installment loans, with loan amounts from $100 up to $5,000 through the main form and up to $50,000 in general. The service is free to use, and you are under no obligation to accept any offer.
Other options worth considering include credit union small-dollar loans, which often have lower fees than payday products, and employer paycheck advances if your company offers them. Family and friends can be a no-interest source, though it is wise to put any agreement in writing. If you belong to a faith community or a local nonprofit, ask about emergency assistance funds. These alternatives may not be as fast as a payday loan, but they can be far less expensive.
When you compare offers, look beyond the monthly payment. Check the APR, the finance charge, the repayment schedule, and any prepayment penalties. A longer term lowers your payment but may increase the total interest you pay. A shorter term saves interest but strains your budget. The right choice is the one you can repay without borrowing again next month. If you are unsure how to evaluate costs, the APR guide mentioned earlier walks through the math in plain language.
Step 5: Know When to Pause and Rebuild
Sometimes the wisest response to a denied short term loan request is to pause and rebuild. If you have been denied by multiple lenders in a short period, more applications will only damage your credit further and waste your time. Instead, take a few weeks or months to improve the underlying issues. Build a small emergency fund, even $500, so the next surprise expense does not force you into a high-cost loan. Set up automatic payments on your existing bills to avoid late marks. Check your credit report for errors and dispute anything inaccurate.
If you are struggling with debt, consider speaking with a nonprofit credit counselor. They can help you create a budget, negotiate with creditors, or enroll in a debt management plan. This is not a quick fix, but it addresses the root cause of repeated denials: a budget that cannot absorb shocks. Once your finances stabilize, you may find that you qualify for better loan terms or no longer need a short term loan at all.
It is also important to recognize the difference between a temporary cash flow problem and a chronic shortfall. Short term loans are designed for the former. If you are consistently short on money before payday, a loan will only deepen the hole. In that case, focus on increasing income, reducing expenses, or both. A side gig, a roommate, or a renegotiated bill can do more for your long-term financial health than any loan.
How a Loan Connection Service Can Help After a Denial
After a denial, your instinct may be to apply everywhere at once. That is the wrong move. A better approach is to use a connection service that routes your information to a network of lenders with different criteria. One lender might decline you for a payday loan but approve an installment loan. Another might specialize in borrowers with thin credit files. By submitting a single request, you avoid multiple hard inquiries and let the matching technology do the work.
AdvanceCash.com operates this way. It is not a direct lender and does not make credit decisions. Instead, it connects you with independent third-party lenders who review your request and may present offers. You can then compare terms and choose the one that fits. The process is secure, uses 256-bit SSL encryption, and can return options in minutes, with funding potentially available as soon as the next business day. If you are tired of guessing which lender will say yes, this kind of service can save you time and reduce the number of rejections.
Before you accept any offer, confirm the lender's terms in writing. Check the APR, fees, and repayment schedule. Make sure the lender is licensed in your state. And remember that short term loans are not intended as long-term financial solutions. They are a tool for bridging a temporary gap, and they should be repaid on time to avoid damaging your credit further.
Your Next Steps After a Denial
A denied short term loan request is frustrating, but it is not a final verdict on your financial options. Start by reading the denial notice and identifying the specific reason. Fix any application errors and reapply strategically, or strengthen your profile before trying again. If you need funds sooner, explore alternative lending options through a connection service, credit union, or community resource. And if denials keep piling up, pause, rebuild your emergency savings, and address the root cause.
The most important thing is to avoid panic borrowing. Do not accept the first offer that comes along without reading the terms. Do not take out multiple loans to cover one expense. Use the denial as a signal to slow down, gather information, and make a decision that improves your situation rather than prolonging it. With the right steps, you can move past this rejection and find a path to the cash you need.