Short Term Loan for a Car Transmission Repair Without Savings
A short term loan for a car transmission repair without savings can get you back on the road fast. Learn how to borrow only what the repair requires and repay with confidence.
By Georgia Meyer
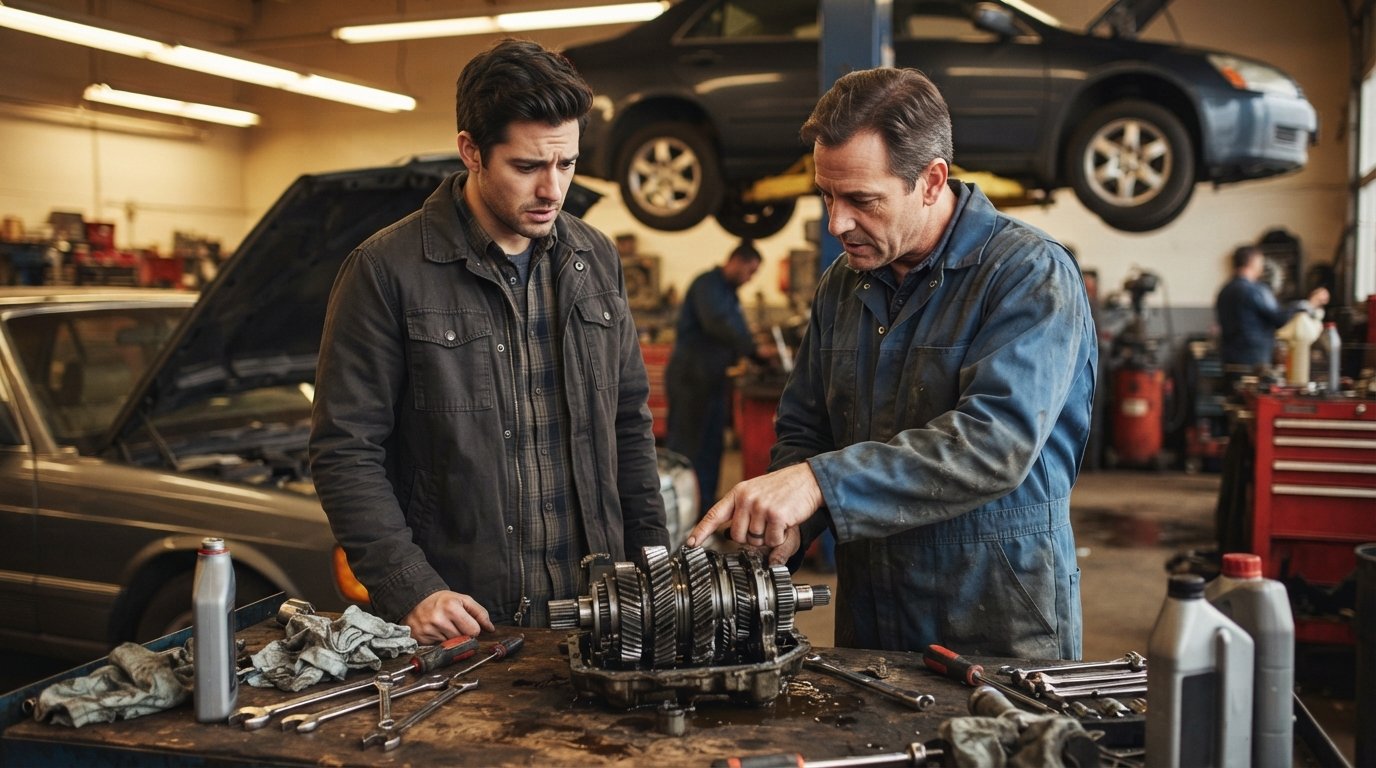
A grinding noise, a slipping gear, or a warning light that will not quit: when your transmission starts to fail, you are facing one of the most expensive car repairs a driver can encounter. If you do not have savings set aside, the pressure multiplies quickly. You need your vehicle to get to work, take your kids to school, and handle every errand that keeps your life running. A short term loan for a car transmission repair without savings can bridge the gap, but only if you approach it with a clear plan. This guide walks you through the real costs, the borrowing decisions, and the repayment strategies that keep a bad situation from becoming a financial crisis.
What a Transmission Repair Really Costs and Why Timing Matters
Transmission work is not a one-size-fits-all expense. The final bill depends on the type of transmission, the severity of the damage, and whether you drive a compact sedan or a heavy-duty truck. A simple fluid flush and filter change might run $150 to $300, but that is maintenance, not a repair. Once internal components fail, the numbers climb fast. Replacing a solenoid pack or a torque converter can land between $500 and $1,500. A full rebuild often falls in the $2,500 to $4,500 range. A remanufactured or new transmission, especially for an all-wheel-drive or performance vehicle, can exceed $5,000 and sometimes approach $8,000 with labor.
Timing adds another layer of stress. Transmission problems rarely fix themselves, and driving on a failing unit can turn a $600 repair into a $4,000 rebuild. That means you often cannot wait weeks to save up the cash. You need a decision within days. This urgency is exactly where a short term loan for a car transmission repair without savings enters the picture. It provides immediate funds so you can authorize the repair before the damage spreads. The key is to treat the loan as a bridge, not a permanent state of borrowing.
Before you apply anywhere, get a written estimate from a reputable shop. Ask for a breakdown of parts and labor, and ask whether a rebuild, a used unit, or a remanufactured unit is the recommended path. A second opinion is worth the time if your schedule allows it. That written estimate becomes your borrowing anchor. It tells you exactly how much you need, which prevents the common mistake of borrowing a round number that is far above the actual bill.
How to Avoid Over-Borrowing for a Single Repair
The biggest risk with any short term loan is borrowing more than the job requires. Lenders may approve you for a larger amount than you requested, and it can be tempting to take the extra as a cushion. Resist that urge. Every extra dollar borrowed adds interest and fees, and it increases the pressure on your next few paychecks. Your goal is to borrow the repair cost plus a small buffer for taxes, shop supplies, or a related part that the mechanic discovers mid-job. A buffer of 10 to 15 percent above the estimate is usually reasonable. Anything beyond that is lifestyle borrowing disguised as an emergency.
Here is a simple framework to set your loan amount before you apply:
- Start with the written repair estimate, including parts, labor, and tax.
- Add a 10 to 15 percent contingency for hidden damage or shop fees.
- Subtract any cash you can safely contribute without emptying your checking account.
- Round down to the nearest amount that covers the bill, not up to a comfort number.
That final figure is your target. If a lender offers more, you can decline the excess or request a smaller amount. Some borrowers also make the mistake of folding unrelated expenses, such as overdue bills or holiday shopping, into a transmission loan. That blurs the purpose and makes repayment harder to track. Keep this loan tied to the repair. If you need help understanding what documentation lenders may request when your income situation is unusual, the guide on advance cash without income proof explains how alternative verification can work. Knowing the requirements ahead of time keeps your application focused and reduces the chance of surprises.
Preparing a Loan Request With Repair Estimates in Hand
Lenders evaluate short term loan requests on perceived ability to repay, not on the emotional weight of your car trouble. A repair estimate is more than a number. It is evidence that the funds have a defined purpose and a defined end date. When you can show a lender a written estimate from a licensed shop, you present yourself as a organized borrower with a plan. That matters, especially when your credit history is less than perfect.
Gather the following before you submit a request: the written repair estimate, proof of income such as recent pay stubs or bank statements, a government-issued ID, and your vehicle information. If you are self-employed or between jobs, be ready to explain your income pattern clearly. Many online loan connection services, including platforms like CashLoanFunded, let you submit one request and compare offers from multiple third-party lenders. That comparison is valuable because terms, fees, and repayment schedules vary widely. A single request saves you from filling out the same forms five times and gives you a clearer view of what is available.
When you review offers, focus on the annual percentage rate, the repayment term, and the total cost of borrowing, not just the monthly payment. A longer term lowers the monthly burden but raises the total interest. A shorter term saves money but demands more from each paycheck. Use the repair estimate to decide which term fits your budget. If the shop needs the car for three days, you do not need a six-month loan for a job that will be done by Friday. Match the loan term to the repair timeline whenever possible.
Short Term Loan Versus Paying by Credit Card
Many drivers instinctively reach for a credit card when the transmission fails. It is fast, familiar, and does not require a separate application. But a credit card is not always the cheaper option, and it carries risks that a dedicated short term loan may avoid. The right choice depends on your credit limit, your interest rate, and your discipline with revolving debt.
Here is a direct comparison of the two paths:
- Interest cost: A short term loan often carries a fixed fee or a fixed interest rate disclosed upfront. A credit card may have a lower promotional rate that jumps after a few months, or a variable rate that rises with the market.
- Repayment structure: Short term loans have a defined payoff date. Credit cards allow minimum payments that can stretch a $3,000 repair into years of debt if you are not aggressive.
- Credit impact: A new loan adds an installment account and a hard inquiry. A credit card charge raises your utilization ratio, which can hurt your score if your limit is low.
- Approval speed: Both can be fast, but loan connection services can return offers within minutes, while a credit limit increase may take longer.
If you have a credit card with a zero percent introductory APR and a limit high enough to cover the repair, that can be the cheapest route, provided you pay it off before the promotional period ends. If your only card is near its limit or carries a high APR, a short term loan for a car transmission repair without savings may cost less overall. Run the numbers on both options using the total repayment amount, not the monthly minimum. The lower monthly payment is not always the lower total cost.
One more factor deserves attention: your ongoing transportation costs. If your car is in the shop for a week, you may need a rental or rideshare. Those costs do not disappear because you took out a loan. Build them into your budget before you sign anything. A repair loan that leaves you unable to afford gas or insurance is not a solution.
Planning Repayment Around Ongoing Transportation Costs
Repayment planning starts the day you accept the loan, not the day the first payment is due. Your transmission repair restores your vehicle, but it does not restore your cash flow. You still have fuel, insurance, registration, and routine maintenance to cover. A realistic repayment plan accounts for all of it. Start by listing your take-home pay and your fixed monthly obligations. Then subtract the loan payment you are considering. If the remaining amount does not cover your normal transportation costs and basic living expenses, the loan is too large or the term is too short.
Consider setting up automatic payments for the loan on a date that aligns with your payday. This reduces the risk of late fees and missed payments, which can damage your credit and add to the cost of the loan. If your income is irregular, choose a due date that follows your most reliable pay period. Some lenders allow biweekly payments, which can reduce the total interest and align with how you get paid. Ask about prepayment penalties before you sign. If there are none, you can pay the loan off early when a bonus or tax refund arrives, saving money on interest.
It also helps to create a small repair fund after this experience. Even $25 per paycheck builds a cushion over time. The next transmission problem, or any major repair, will be less frightening if you have a few hundred dollars set aside. A short term loan solved this emergency, but savings prevent the next one from requiring the same solution. Treat the loan payment as a temporary line item and redirect it into savings once the debt is cleared.
When a Short Term Loan Makes Sense and When It Does Not
A short term loan for a car transmission repair without savings makes sense when the repair is necessary for your income, the loan amount matches the estimate, and you have a clear repayment path within a few months. It makes less sense when the repair cost exceeds the value of the vehicle, when you are already behind on other debts, or when the only available offers carry fees that push the total cost far beyond the repair itself. In those cases, consider alternatives such as a payment plan with the repair shop, a lower-cost rebuilt unit, or delaying non-essential expenses to free up cash.
Your vehicle is essential, and a failed transmission is not a problem you can ignore. By getting a written estimate, borrowing only what the repair requires, comparing loan offers carefully, and planning repayment around your real transportation costs, you can handle this emergency without letting it spiral. A short term loan is a tool. Used with discipline, it gets you back on the road and keeps your finances intact.