Saving for an Emergency Fund on a Tight Monthly Budget
Saving for an emergency fund on a tight monthly budget starts with small, automated transfers. Learn how to build a cash cushion that prevents future borrowing.
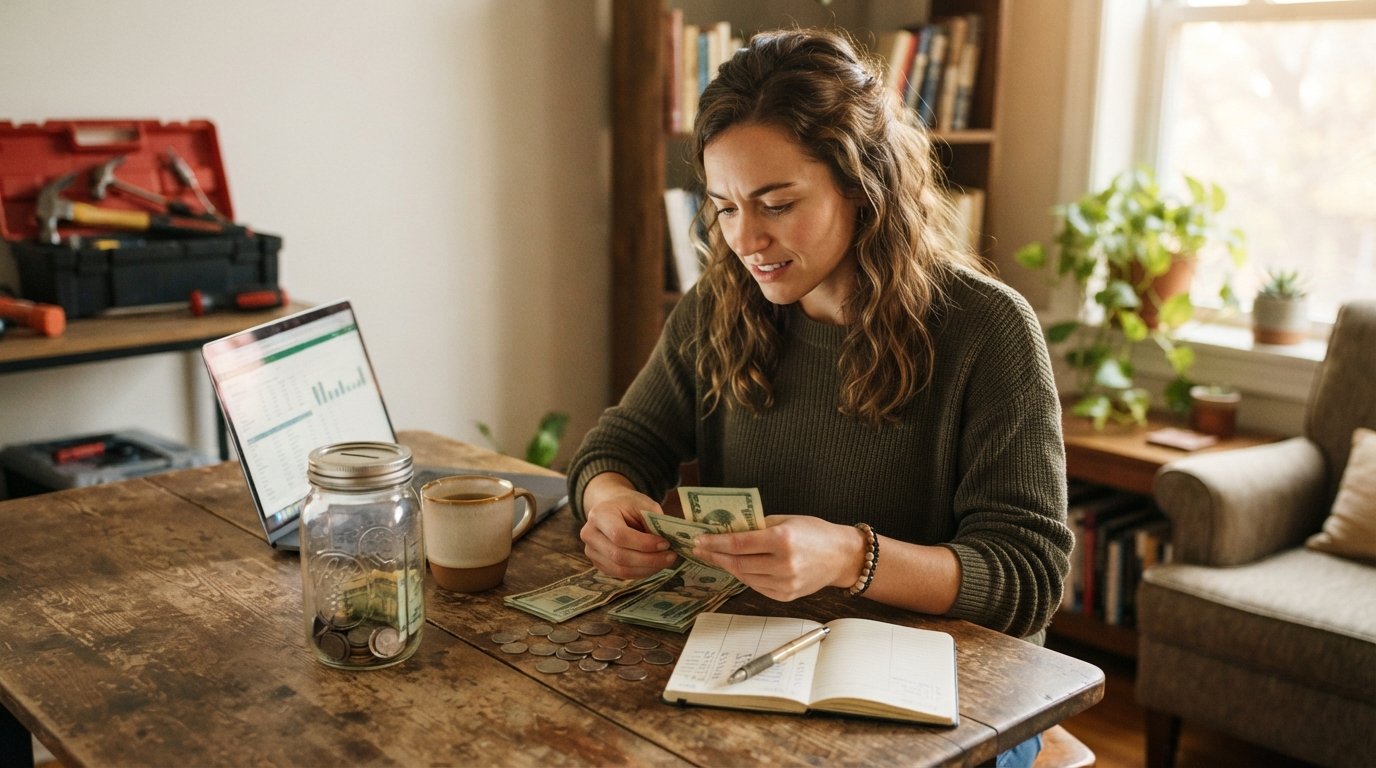
Your car's check engine light just came on, your refrigerator is making a strange noise, or your child needs an unexpected medical visit. These moments rarely arrive at a convenient time, and when money is already stretched thin, they can feel like a financial earthquake. The good news is that you do not need a six-figure salary or a perfect budget to build a safety net. Saving for an emergency fund on a tight monthly budget is entirely possible when you focus on small, consistent actions and use a few smart strategies to protect your progress. Even a modest cushion of a few hundred dollars can mean the difference between a minor inconvenience and a financial crisis that pushes you toward high-interest borrowing.
Why a Small Emergency Fund Changes Everything
Many people assume an emergency fund needs to cover three to six months of living expenses before it is worth starting. That goal is admirable, but it can feel so overwhelming that it stops you from saving anything at all. The truth is that the first few hundred dollars in your fund do the heaviest lifting. They cover the most common emergencies: a tire replacement, a prescription, a plumbing repair, or a short gap between paychecks. Those are exactly the situations that often send people searching for fast cash options and end up costing far more in fees and interest than the original expense.
Consider a $400 car repair. If you have no savings, you might need to use a credit card with a high interest rate or apply for a short-term loan. Paying that money back over several months could cost you an extra $100 or more. But if you had $500 set aside, the repair becomes a simple transaction with no lingering debt. That is the real power of a starter emergency fund: it keeps a small problem from becoming a long-term financial burden. When you are saving for an emergency fund on a tight monthly budget, your first goal should be to reach $500 as quickly as possible, then build from there.
Start With a Small Target and Automate Weekly Transfers
The biggest mistake people make when money is tight is waiting for a large lump sum to appear before they start saving. That day rarely comes. Instead, the most effective approach is to pick a target that feels almost too easy and automate it. If you can only spare $10 per week, that is $40 per month and nearly $500 in a year. If you can manage $25 per week, you will cross the $1,000 mark in about ten months. The key is consistency, not size.
Automation removes willpower from the equation. Set up a recurring transfer from your checking account to a separate savings account on the day after you get paid. Even better, schedule it for the same day your paycheck arrives so the money never sits in your spending account where it can be tempted away. Start with an amount you know you will not miss, even if it is just $5 or $10 per week. You can always increase it later when your budget loosens up. The habit of saving matters more than the initial dollar amount.
If your income is irregular, try a different automation strategy. Transfer a small percentage of every deposit, such as 2% or 3%. On a $600 paycheck, that is $12 to $18, which is painless but adds up over time. You can also use a rule like rounding up every purchase to the nearest dollar and transferring the difference at the end of the week. Many banking apps offer this feature automatically. The goal is to make saving a background process rather than a monthly decision you have to negotiate with yourself.
Where to Keep the Money So It Stays Accessible but Out of Reach
An emergency fund needs to be liquid enough to access quickly, but not so accessible that you spend it on non-emergencies. Keeping the money in your everyday checking account is a recipe for failure because it blends with your spending money and disappears without a trace. On the other hand, locking it into a long-term investment or a certificate of deposit with steep withdrawal penalties defeats the purpose of an emergency fund.
The sweet spot is a separate high-yield savings account at a different bank from your checking account. The separation adds a small amount of friction, which gives you time to ask yourself whether a purchase is truly an emergency. Look for an account with no monthly fees, no minimum balance requirement, and free transfers. Online banks often offer these features along with competitive interest rates, which means your emergency fund grows a little bit on its own. Even a modest interest rate helps your money keep pace with inflation and rewards you for leaving it alone.
If you are worried about the temptation to dip into the fund, consider a few extra barriers. You could choose an account that does not offer a debit card, or one that requires a transfer to your checking account before you can spend the money. That one-day delay is often enough to prevent impulse withdrawals. Some people also keep a small portion of their emergency fund in cash at home, perhaps $100 to $200, for immediate needs like a power outage or a local merchant that does not accept cards. The rest should stay in the savings account where it can earn interest and stay out of daily reach.
If you currently have a short-term loan or cash advance to repay, your budgeting strategy needs to account for that obligation first. Our guide on monthly budgeting with a cash advance explains how to balance repayment with other financial goals, including building savings. The key is to avoid taking on new debt while you are working toward your emergency fund, so you can break the cycle of borrowing and start moving forward.
Use Windfalls to Seed and Accelerate Your Fund
One of the fastest ways to build momentum is to commit a portion of any unexpected money to your emergency fund. Tax refunds, work bonuses, cash gifts, stimulus payments, and even small rebates can give your savings a significant boost when you direct them intentionally. The average tax refund in the United States is often several hundred to a few thousand dollars, which could fund a starter emergency fund in one shot. If you are saving for an emergency fund on a tight monthly budget, a windfall is your best opportunity to skip ahead.
The trick is to decide in advance how you will use windfalls so you are not making the decision in the moment when you are tempted to spend. A simple rule is to split any unexpected money three ways: one-third to immediate needs or debt repayment, one-third to your emergency fund, and one-third to something you enjoy. That way you are making progress without feeling deprived. If you are expecting a refund or bonus, set up the transfer to your savings account as soon as the money arrives, before you have a chance to spend it on something else.
You can also create your own small windfalls throughout the year. Sell unused items around the house, cash in unused gift cards, or redirect money from a subscription you cancel. A $50 sale on a local marketplace or a $30 refund from a canceled service might not feel like much, but those small amounts add up quickly when they go straight into your emergency fund. The habit of catching these little opportunities is just as important as the amount you save.
Find Money in Your Budget Without Feeling Deprived
When money is already tight, saving for an emergency fund on a tight monthly budget requires finding a few dollars that are not currently working as hard as they could. The goal is not to cut everything you enjoy, but to identify expenses that provide little value relative to their cost. Start by reviewing your last two or three bank statements and look for patterns. You might find subscriptions you forgot about, fees you did not notice, or small purchases that add up more than you realized.
Here are a few categories where people often find hidden savings without sacrificing their quality of life:
- Subscription audit: List every recurring charge and cancel anything you have not used in the past 30 days. Even $15 per month is $180 per year for your fund.
- Bill negotiation: Call your internet, phone, and insurance providers and ask about current promotions or lower-cost plans. A single call can save $20 to $50 per month.
- Grocery planning: Plan meals around store sales and use a list to avoid impulse purchases. Reducing food waste by even 20% can free up $40 to $80 monthly.
- Energy efficiency: Adjust your thermostat by a few degrees, unplug unused devices, and switch to LED bulbs. Small changes can lower your utility bill by 10% or more.
Once you identify savings, do not let them disappear into your general spending. Redirect the exact amount to your emergency fund automatically. If you cancel a $15 subscription, set up a $15 recurring transfer on the same day the charge used to hit your account. That way your lifestyle does not absorb the savings, and your fund grows without any extra effort on your part. The same principle applies to any raise or income increase you receive. Before you adjust your spending, increase your automatic savings transfer by half of the new amount.
Protect Your Progress and Avoid Common Pitfalls
Building an emergency fund on a tight budget takes time, and it is easy to get derailed by a single unplanned expense or a moment of weakness. One of the most important habits is to define what counts as an emergency before you need to make a decision. A true emergency is unexpected, necessary, and urgent. A sale on a new television is none of those things. Write down your personal definition and keep it somewhere visible, like a note on your phone or a sticky note on your computer. When you are tempted to withdraw from your fund, review your definition first.
Another common pitfall is using your emergency fund to cover expenses that are actually predictable. Car maintenance, annual insurance premiums, and holiday gifts are not emergencies because you know they are coming. Create separate sinking funds for those expenses so your emergency fund stays reserved for the truly unexpected. A sinking fund is simply a savings account for a specific planned expense. You contribute a small amount each month, and when the bill arrives, the money is already there. This strategy keeps your emergency fund intact and reduces the number of financial surprises you face.
If you do need to use your emergency fund, do not see it as a failure. The entire purpose of the fund is to be used when an emergency arises. The key is to replenish it as soon as possible. After you spend the money, set up a temporary increase to your automatic transfer until the fund is back to its previous level. You might also consider using a portion of your next windfall to speed up the replenishment. The goal is to keep the cycle going so you are never left without a safety net for long.
Know When to Use a Short-Term Loan Instead of Your Emergency Fund
There are situations where preserving your emergency fund is the smarter financial move, even if it means using a short-term loan for a small expense. If your car breaks down and you need $200 for a repair, using a short-term loan for a few weeks might be better than draining the $500 you spent months building. The loan costs you a fee, but your emergency fund stays intact for a larger crisis. That said, this strategy only works if you can repay the loan quickly and avoid rolling it over. Short-term loans are not designed to be long-term solutions, and the costs can add up fast if you do not have a clear repayment plan.
If you are considering a short-term loan, compare offers carefully and understand the total cost before you commit. AdvanceCash.com is a free online connection service that helps U.S. consumers explore short-term and payday loan options from third-party lenders. You can complete a single request form and potentially be matched with lenders in the network, with funds available as soon as the next business day. AdvanceCash is not a lender and does not make credit decisions; all loan terms, rates, and fees are set by the individual lender. Using a service like this can be a reasonable stopgap when you have an urgent expense and want to protect your savings, but it should never replace the goal of building a robust emergency fund.
For more information on how the connection process works, visit FundingCashLoans to explore options. The site provides plain-language guides on borrowing and budgeting, which can help you make an informed decision. Remember that any loan you take should have a clear repayment plan built into your monthly budget. If you cannot afford to repay the loan within a short period, it may be better to use your emergency fund or look for other alternatives.
Build the Habit First, Then Grow the Balance
Saving for an emergency fund on a tight monthly budget is not about finding a large sum of money you did not know you had. It is about building a habit of setting aside small amounts consistently and protecting those savings from everyday spending. Start with a target that feels achievable, automate your transfers, keep the money in a separate account, and use windfalls to give yourself a head start. Celebrate every milestone, whether it is your first $100 or your first $1,000, because each dollar you save is a dollar you will not have to borrow in a crisis.
Over time, the habit becomes easier and the balance grows faster than you might expect. The peace of mind that comes from knowing you can handle a small emergency without derailing your finances is worth far more than the sacrifices you make to get there. And if you ever do need to borrow, you will be in a stronger position to repay quickly and get back to building your safety net.