Quick Start Emergency Savings on a Tight Budget
Build a quick start emergency savings on a tight budget with small, consistent steps. Protect yourself from surprise bills and avoid high-cost debt.
By Sophia Hayes
An emergency never waits for a convenient moment. A car repair, a medical bill, or a sudden job loss can arrive when your bank account is already stretched thin. That is why building an emergency fund matters, even when money is tight. The good news is that you do not need a windfall to get started. You can begin with a few dollars, a clear plan, and a habit that grows over time. This guide shows you how to quick start emergency savings on a tight budget, using realistic steps that work for real people with rent, groceries, and debt to manage. Whether you are living paycheck to paycheck or recovering from a financial setback, these strategies help you create a safety net without starving your current needs.
Why Emergency Savings Matter More Than Ever
Life is unpredictable. According to surveys, a large share of Americans cannot cover a $400 emergency expense without borrowing. That gap forces people into high-cost options like payday loans or credit card debt, which can spiral quickly. An emergency fund changes the math. It turns a crisis into an inconvenience. Instead of scrambling for cash, you pay the bill and move on.
Emergency savings also reduce stress. Financial anxiety affects sleep, health, and relationships. Knowing you have even a small cushion lets you breathe. And it protects your long-term goals. Without savings, one emergency can wipe out months of progress on debt payoff or retirement. With savings, you stay on track.
For those with less-than-perfect credit, the stakes are higher. Traditional lenders may decline you, and alternative options can be expensive. A cash advance or short-term loan might be the only option in a true crisis. But if you have savings, you avoid that path entirely. That is why starting small today beats waiting for the perfect moment.
Set a Realistic First Goal: $100 to $500
Most experts suggest three to six months of expenses for a full emergency fund. That number feels impossible when you are on a tight budget. So ignore it for now. Your first goal is much smaller: $100, then $500. These amounts cover common emergencies like a tire replacement, a prescription, or a utility bill.
A mini fund of $500 prevents many high-interest loans. It also builds confidence. Once you hit $500, you can aim for one month of essential expenses, then two. The key is to start with a target you can actually reach. A $100 goal is achievable in weeks, not years, which keeps you motivated.
Write down your first goal and a deadline. For example, save $100 in 30 days. That means setting aside about $3.33 per day. You can find that by skipping a takeout coffee, packing lunch, or canceling a streaming service. Small wins add up.
Find Money to Save Without Feeling the Pinch
When your budget is already tight, you cannot simply will extra money into existence. You must find it. Start by tracking every dollar for one week. Use a notebook or a free app. You will likely spot leaks: unused subscriptions, impulse buys, ATM fees, or groceries that go bad. Redirect those dollars to savings.
Next, review your bills. Call your internet, phone, and insurance providers. Ask for a lower rate or a promotional discount. Many companies have retention offers. Even a $10 monthly reduction is $120 per year. That is a solid start to your emergency fund.
Here are practical ways to free up cash quickly:
- Cancel or pause subscriptions you do not use (streaming, gym, apps).
- Switch to a cheaper phone plan or negotiate your current bill.
- Use cashback apps and coupons for groceries and gas.
- Sell unused items online or at a consignment shop.
- Take on a side gig like dog walking, tutoring, or delivery for a few hours a week.
Each of these actions can generate $20 to $200 per month. The goal is not to overhaul your life overnight but to stack small savings. Even $50 per month grows to $600 in a year, plus interest. That is a meaningful emergency buffer.
If you need a larger sum quickly for a true emergency, you might consider a short-term loan. For example, top advance cash services can connect you with lenders who provide fast funding, but use these options only after you have exhausted savings and other resources. They are not a substitute for an emergency fund.
Automate Your Savings, Even in Small Amounts
Willpower is unreliable. Automation is not. Set up an automatic transfer from your checking account to a separate savings account on payday. Start with $5 or $10 per week. You will barely notice it, but the balance will grow. Many banks allow you to open a savings account with no minimum balance and no monthly fee.
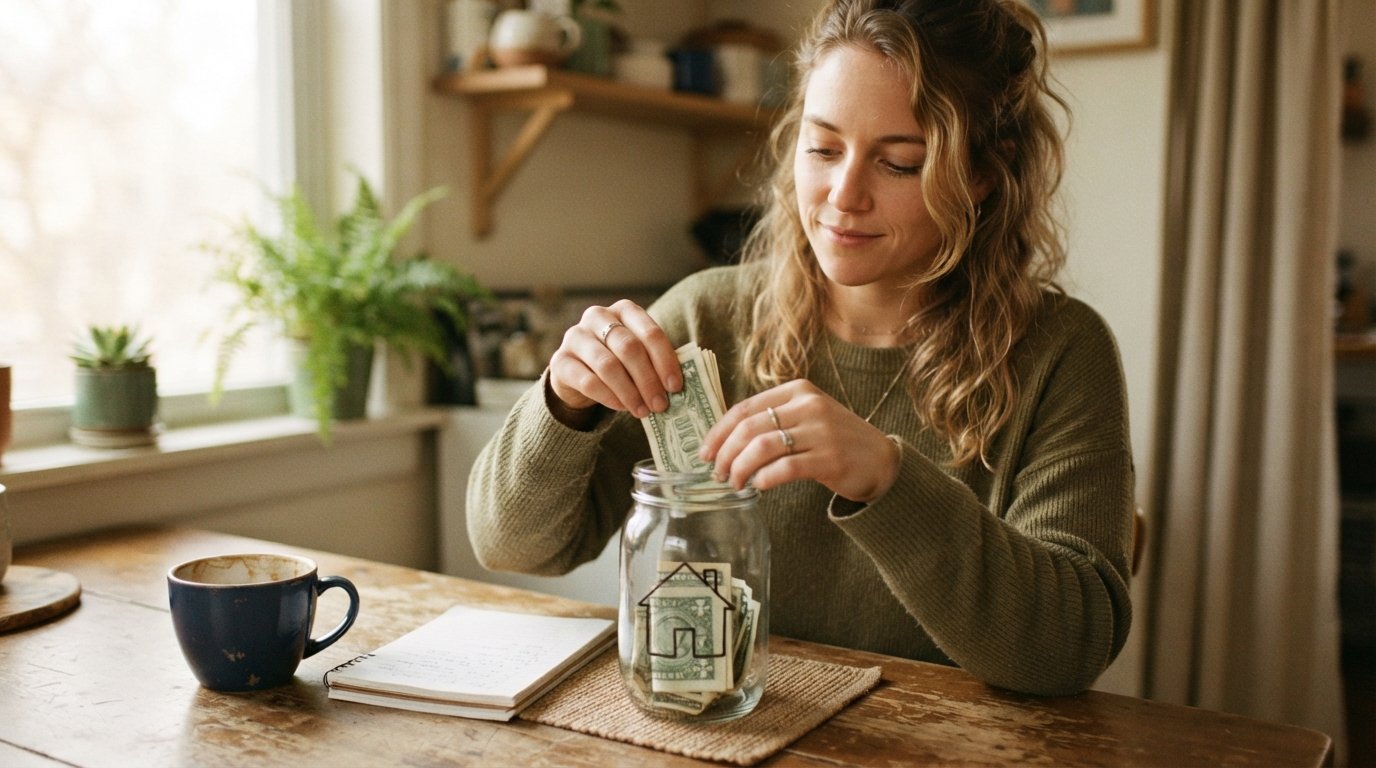
If your employer offers direct deposit, split your paycheck so a portion goes directly to savings. That way, you never see the money in your checking account, so you are less tempted to spend it. If you get paid in cash, set aside a small amount in an envelope or a jar each week. The physical act reinforces the habit.
Another trick is to save windfalls. Tax refunds, bonuses, birthday money, or stimulus payments are opportunities to boost your fund. Put at least half of any windfall into savings. You will still have extra to enjoy, but your emergency fund gets a significant lift. For example, a $600 tax refund could fully fund a $500 mini emergency fund in one step.
Use a Separate Account to Avoid Temptation
Keeping emergency savings in your checking account is a recipe for spending. Open a separate savings account at a different bank or credit union. The friction of transferring money back makes you think twice before raiding it. Look for an account with no monthly fees and a decent interest rate. Online banks often offer higher yields than traditional branches.
Name the account something that reminds you of its purpose, like "Emergency Fund" or "Safety Net." Some banks let you set up sub-accounts for different goals. That visual separation helps you stay disciplined. If you must use the money for a true emergency, replenish it as soon as possible. The fund is not a slush fund for sales or vacations.
If you have a side hustle or variable income, deposit a percentage of each payment into savings. Even 5% adds up. The key is consistency, not perfection. Missing a week is fine; just resume as soon as you can.
Cut Expenses Strategically, Not Painfully
Extreme frugality backfires. If you cut everything you enjoy, you will rebel and spend more. Instead, target areas where you can save without feeling deprived. Housing, transportation, and food are the biggest budget categories. Can you refinance your car loan, take public transit, or meal plan to reduce grocery bills? Small changes in these areas yield big savings.
For example, meal planning can cut your grocery bill by 20% or more. Instead of buying lunch at work, bring leftovers. That saves $10 per day, or $200 per month. Over a year, that is $2,400, enough to fund a solid emergency cushion. Similarly, bundling insurance or raising your deductible can lower premiums. Just make sure you have enough savings to cover the higher deductible if you file a claim.
Review your debt payments. If you have high-interest credit card debt, consider a balance transfer to a 0% APR card or a debt consolidation loan. Lower payments free up cash for savings. But be careful: do not use your emergency fund to pay down debt unless the interest rate is extremely high and you have another safety net. Usually, you should save and pay debt simultaneously.
When to Consider a Short-Term Loan Instead
Sometimes an emergency is too big for your current savings. If you need $1,000 for a car repair and only have $200, you might need a short-term loan. Options include payday loans, installment loans, and personal loans. These products are available through loan-connecting services like CashLoanFunded, which links borrowers with third-party lenders. Such services are not direct lenders; they simply connect you with lenders who may offer funds as soon as the next business day.
Before you borrow, understand the costs. Payday loans often carry very high APRs and short repayment terms. Installment loans spread payments over months but may still be expensive. Personal loans from online lenders can be more affordable if you have decent credit. Always read the terms and borrow only what you can repay. A short-term loan should be a last resort, not a first choice.
If you do take a loan, make repaying it a priority. Add the payment to your budget and avoid taking on more debt. Once the loan is repaid, redirect that payment amount into your emergency savings. That way, you turn a negative experience into a positive habit.
Build the Habit: Consistency Over Perfection
The biggest mistake people make is waiting for a large sum to start saving. You do not need $1,000 to begin. You need $1. Saving is a habit, not a one-time event. Set a daily or weekly savings goal, no matter how small. Track your progress visually. Use a chart or an app that shows your growing balance. Celebrate milestones: $50, $100, $250, $500.
Involve your family or a friend. Share your goal and ask them to check in on your progress. Accountability increases success. If you slip up, do not quit. Just get back on track the next day. Over time, your emergency fund will become a normal part of your financial life.
Remember that building savings on a tight budget is possible. It requires creativity, discipline, and patience. But the peace of mind is worth it. Start today with one small action: open a savings account, transfer $5, or cancel one subscription. Your future self will thank you.
Emergency savings are not a luxury for the rich. They are a necessity for everyone. By starting small and staying consistent, you can protect yourself from life's surprises and avoid the debt trap. Whether you save $5 a week or $50, the important thing is to begin. Your quick start emergency savings on a tight budget begins now.