Loan Eligibility When Paid Cash or Under the Table
Loan eligibility when paid cash or under the table depends on alternative income proof. Learn which documents lenders accept and how to strengthen your application.
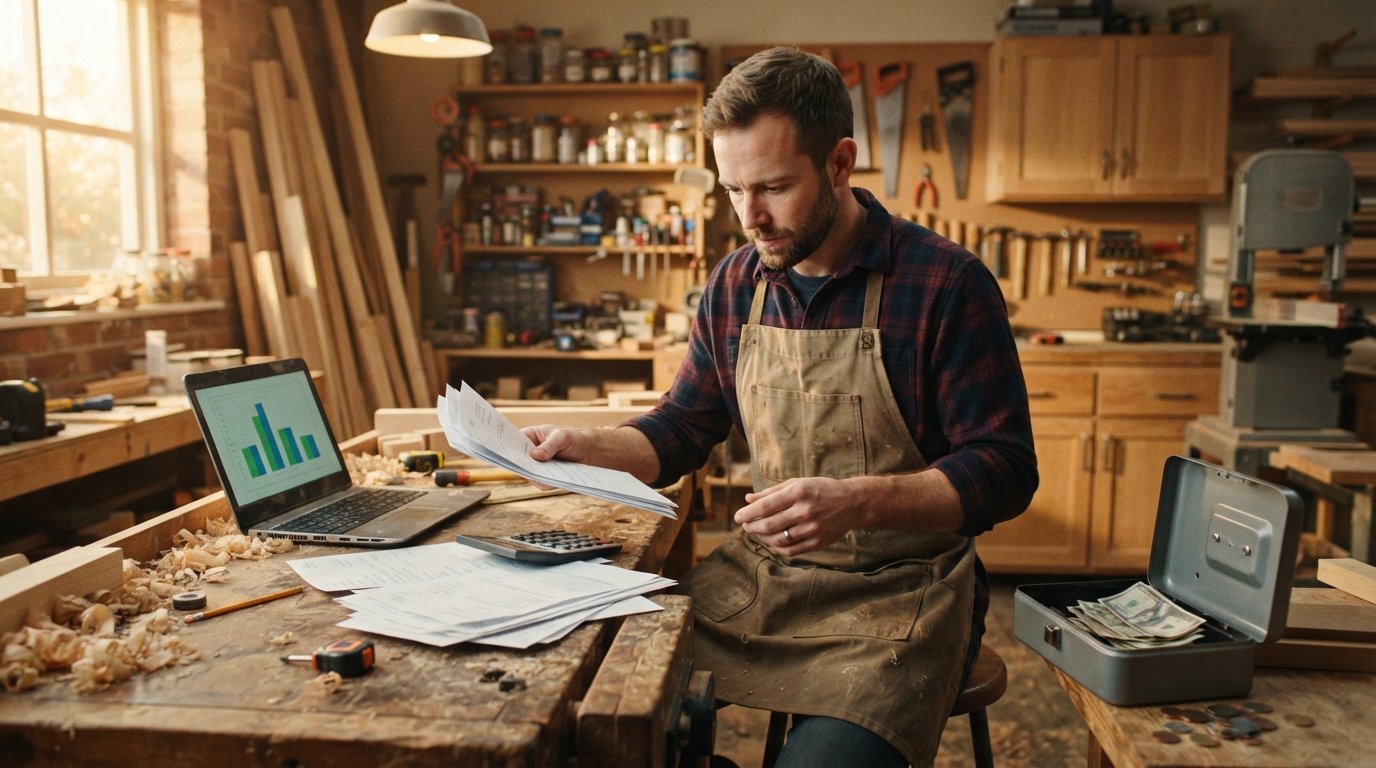
If you earn cash or work off the books, you already know the frustration: the money is real, but your pay stubs are not. Traditional lenders often treat undocumented income as invisible, leaving millions of U.S. workers wondering whether a loan is even possible. The short answer is yes, but the path looks different. Lenders do not simply reject cash earners; they look for alternative evidence that income is steady and reliable. Understanding how that evidence works, and where to find lenders who accept it, can make the difference between a quick approval and a dead end.
This guide walks through the practical side of loan eligibility when paid cash or under the table. You will learn which documents can replace pay stubs, why some lenders are stricter than others, and how a consistent deposit history can quietly do the work of a formal paycheck. The goal is not to promise approval, because no one can do that except a lender, but to help you present your income in the most credible light possible.
Why Cash Income Is Not a Dealbreaker
Many people assume that without a W-2 or a recent pay stub, loan applications are automatically denied. That is not accurate. Lenders are ultimately trying to answer one question: can this person repay the loan on time? A paycheck is convenient proof, but it is not the only proof. Bank statements showing regular deposits, invoices from clients, or a history of consistent cash flow can all support the same conclusion. The key is to demonstrate that your income is not a one-time windfall but a recurring reality.
That said, not every lender is set up to evaluate alternative income. Large banks and many online lenders rely on automated systems that pull payroll data and credit reports. If your income does not appear in those systems, the application may stall. This is why cash earners often have better luck with lenders that manually review applications or specialize in non-traditional borrowers. Knowing which type of lender you are dealing with saves time and avoids unnecessary credit inquiries.
It also helps to understand that loan eligibility when paid cash or under the table is not a single standard. Each lender sets its own rules, and those rules can vary widely. Some may accept three months of bank statements, while others want six months or a letter from an accountant. Some may look at your credit score, while others focus almost entirely on income and affordability. The more you know about these variations, the better you can target your applications.
Documentation That Can Replace a Pay Stub
When you cannot produce a traditional pay stub, you need to build an alternative paper trail. The strongest evidence is anything that shows money coming in regularly and going into an account that a lender can verify. Here are the most commonly accepted alternatives, ranked roughly by how much weight they tend to carry:
- Bank statements: Three to six months of statements showing consistent deposits, even if they are cash deposits or transfers from payment apps. Lenders look for regularity, not necessarily a single large balance.
- Invoices and receipts: If you are self-employed or do contract work, invoices paired with matching deposit records create a clear story of ongoing income.
- Tax returns and 1099 forms: Even if you did not report every dollar, filed returns show declared income and can support your case. Lenders understand that cash businesses sometimes report conservatively.
- Profit and loss statements: A simple, honest P&L prepared by you or a bookkeeper can help a lender understand your monthly cash flow.
- Letters from clients or employers: A signed letter confirming ongoing work and payment terms can add credibility, especially for independent contractors.
These documents work best when they tell a consistent story. If your bank statements show irregular deposits and your invoices do not match, a lender may question the reliability of your income. Take time to organize your records before applying. A clean, chronological folder of statements and invoices makes a manual review much easier and signals that you are a serious borrower.
It is also worth noting that some lenders will accept alternative documentation only if you have a certain amount of history. For example, a lender might require six months of bank statements rather than three if you cannot provide pay stubs. The trade-off is more paperwork in exchange for a clearer picture of your finances. If you are working with a loan connection service, you can ask which documents are typically requested so you can prepare in advance.
How Lenders Evaluate Cash Income and Why They Vary
Lenders vary in how much income proof they require because they have different risk appetites and different business models. A payday lender, for instance, may focus on your next paycheck and a bank account in good standing, while an installment lender might want a broader view of your monthly budget. Online lenders that use automated systems may simply decline applications that do not fit their data model, not because your income is invalid but because their system cannot see it. Manual underwriters, by contrast, can read bank statements and make a judgment call.
This variation is why a denial from one lender does not mean you are ineligible everywhere. It may mean you applied to a lender that does not accept alternative income documentation. Before submitting a full application, ask about documentation requirements. A quick phone call or a look at the lender's FAQ page can save you from a hard credit inquiry that goes nowhere. If you are using a connection service, the initial request form is usually a soft inquiry and does not affect your credit score.
Another factor is the size of the loan. Small short-term loans often require less documentation because the lender is taking on less risk. Larger personal loans or installment loans usually involve more scrutiny. If you are seeking a smaller amount, you may find more flexibility. If you need a larger sum, be prepared to provide a more comprehensive picture of your income and expenses. The same principle applies to loan eligibility when paid cash or under the table: the stronger your documentation, the more options you are likely to see.
Credit history also plays a role, but it is not the only factor. Some lenders specialize in working with borrowers who have less-than-perfect credit, and they may weigh income stability more heavily than a credit score. Others may require a minimum score but be flexible on documentation. The combination of credit and income requirements is unique to each lender, so it is worth exploring a range of options rather than assuming one denial applies to all.
Building a Steady Deposit History That Supports Your Request
If you have time before you need the loan, one of the most effective things you can do is build a steady deposit history. This means depositing your cash earnings into a bank account on a regular schedule, ideally every week or every two weeks. Even if you typically keep cash on hand, routing a portion of your income through a bank account creates a verifiable record. Lenders can then see a pattern that looks like a paycheck, which makes underwriting easier.
Consistency matters more than amount. A borrower who deposits $800 every two weeks for six months looks more reliable than one who deposits $3,000 one month and nothing for the next two. If your income is seasonal or irregular, try to show a baseline that covers your essential expenses. You can also use a separate account for business income if you are self-employed, which makes it easier to track deposits and present them to a lender.
When you are ready to apply, organize your statements so the deposits are easy to spot. Highlight recurring deposits or use a simple spreadsheet to summarize monthly inflows. This is not about hiding anything; it is about making your financial picture legible to someone who reviews dozens of applications a day. A lender who can quickly see your income pattern is more likely to move forward. For a deeper look at how lenders assess cash income, see this guide on cash loan eligibility requirements.
Setting Realistic Expectations About Approval and Terms
No article can guarantee approval, and any lender or service that promises a specific outcome is worth scrutinizing. Loan eligibility when paid cash or under the table is ultimately determined by the lender's underwriting criteria, which may include your credit history, income stability, existing debts, and even your banking history. Your job is to present the strongest possible case; the lender's job is to decide. Going in with that mindset helps you avoid frustration and make better choices.
Terms are also lender-specific. Interest rates, fees, and repayment schedules can vary dramatically based on your perceived risk. Cash earners may see higher rates than W-2 employees because alternative income is harder to verify. That does not mean the loan is a bad idea, but it does mean you should compare offers carefully. Look at the annual percentage rate (APR), the total cost of the loan, and the repayment terms. If an offer feels predatory, walk away. Responsible borrowing starts with understanding what you are signing.
It is also wise to borrow only what you need and can repay. Short-term loans are designed to bridge a gap, not to solve long-term financial problems. If you are considering a payday or installment loan, map out your budget to ensure the repayment fits. If you are unsure where to start, a free online connection service like FundingCashLoans can help you compare offers from multiple lenders with a single request, without obligating you to accept any of them. Remember that FundingCashLoans is not a lender and does not make credit decisions; all terms come directly from the lender.
Practical Steps to Improve Your Chances
If you are planning to apply for a loan with cash income, a little preparation goes a long way. Start by gathering your documents: bank statements, invoices, tax returns, and any letters that support your income. Then think about which lenders are most likely to accept your situation. Specialized online lenders and connection services often have more experience with non-traditional income than big banks. Finally, be honest about your income. Exaggerating or fabricating documents is fraud and will be caught. Lenders appreciate transparency, and a truthful application with solid evidence is your best strategy.
Consider these steps as a checklist before you apply:
- Collect three to six months of bank statements showing regular deposits.
- Organize invoices or receipts if you are self-employed.
- Check your credit report for errors and know your score.
- Decide on a loan amount you can comfortably repay.
- Research lenders or use a connection service that accepts alternative income.
Each step reduces uncertainty and helps you present a coherent financial story. It also protects you from applying to lenders that will not consider your income, which saves time and avoids unnecessary credit checks. The more prepared you are, the smoother the process will feel.
Ultimately, being paid cash or under the table does not close the door to borrowing. It simply changes the paperwork. Lenders who understand alternative income will look for patterns, not pay stubs, and a steady deposit history can be just as persuasive as a formal paycheck. By knowing your options, preparing your documents, and setting realistic expectations, you can navigate the process with confidence and find a loan that fits your situation.