Fixed Versus Variable Rates on Personal Loan Offers
Compare fixed versus variable rates on personal loan offers and learn how rate caps and repayment windows affect what you pay each month.
By Tessa Caldwell
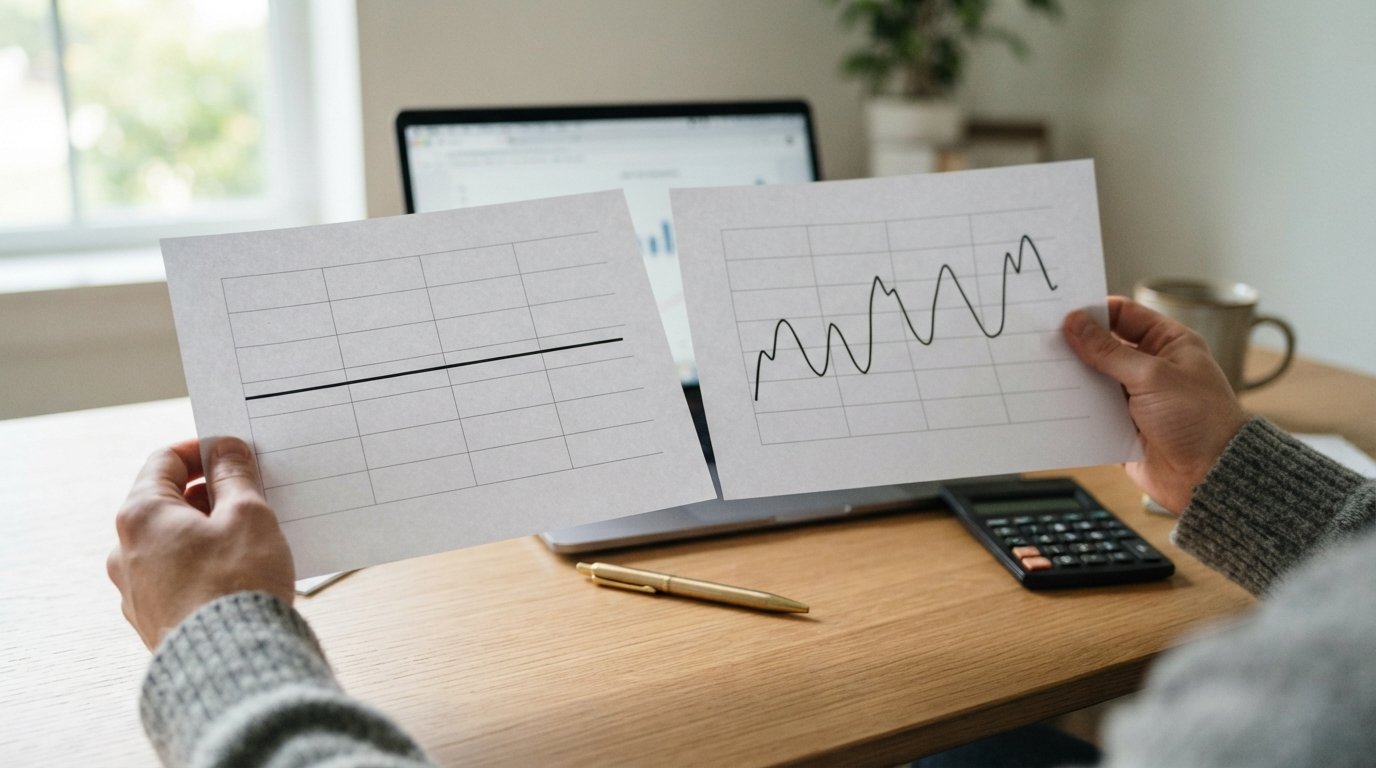
You submit a loan request, offers appear, and each one shows a rate. Some look stable. Others seem lower at first. The difference between those numbers often comes down to one decision: fixed versus variable rates on personal loan offers. That single detail can change what you repay months from now, not just on day one.
Understanding how each rate type works, where it appears in an offer, and how it behaves over time helps you compare deals on equal footing. This guide breaks down fixed and variable pricing, explains how rate-change language works in loan agreements, and shows which structure tends to fit short repayment windows versus long ones. If you are connecting with third-party lenders through a platform such as AdvanceCash.com, knowing how to read rate terms is one of the most practical skills you can build before accepting any offer.
How Fixed and Variable Rates Appear in an Online Loan Offer
When you request personal loan offers online, lenders present pricing in a standardized way, but the details behind the headline rate can differ. A fixed rate is stated as one number that stays the same for the life of the loan. A variable rate is usually shown as a starting rate plus a reference to an index, such as the prime rate, that can move up or down over time.
In a typical offer card or disclosure, look for the annual percentage rate (APR), the interest rate, and any language describing whether the rate is fixed or adjustable. The APR matters because it bundles interest with certain fees, giving you a more complete cost picture. The interest rate tells you what you pay on the principal. Both should be clearly labeled, and if an offer does not say whether the rate is fixed or variable, that is a question to raise before you proceed.
Offers can also include a range rather than a single rate. A lender might show a range of APRs based on creditworthiness, then finalize the rate after review. With variable offers, the disclosed starting rate is often tied to a margin plus an index value at the time of approval. That starting point is not a promise about future payments, which is why reading the surrounding language matters as much as the headline number.
- Fixed rate: one interest rate for the entire repayment term, with a predictable monthly payment.
- Variable rate: a starting rate that can adjust, usually in relation to an index, changing your payment or term.
- APR: the broader cost measure that includes interest and certain fees, useful for side-by-side comparison.
- Rate range: the spread of possible rates a lender may offer based on credit and other factors.
Because personal loan offers from different lenders may mix fixed and variable products, comparing them requires more than ranking the lowest starting number. A variable offer with a low introductory rate can look cheaper than a fixed offer at first glance, but the comparison changes once you account for potential adjustments. The next section explains why those adjustments happen and how they affect your monthly payment.
Why Variable Rates Can Change Your Monthly Payment Mid-Loan
A variable rate is connected to a benchmark that moves with the broader interest rate environment. When that benchmark rises, your rate typically rises with it, and when it falls, your rate may fall too. Lenders usually describe the adjustment in terms of a margin added to the index. For example, if the index is 5 percent and the margin is 3 percent, your rate starts at 8 percent. If the index later climbs to 6 percent, your rate becomes 9 percent, unless caps or other limits apply.
What happens to your payment depends on how the loan is structured. Some variable-rate personal loans adjust the monthly payment to keep the same repayment timeline. Others keep the payment similar and extend or shorten the term, or apply the change at specified intervals. The agreement should state the adjustment frequency, the index used, and how the new payment is calculated. Without that clarity, a borrower can be caught off guard when a payment increases.
Consider a simple example. You borrow $8,000 over three years at a variable rate that starts at 9 percent. Your initial payment is calculated on that rate. If the index rises by one percentage point after the first year and the lender passes that increase through, your rate becomes 10 percent. On the same remaining balance and term, the monthly payment rises. Over a long repayment window, several small increases can add up to a meaningful difference in total interest paid.
This is why variable rates deserve careful attention when the repayment window is long. A change that seems minor in month three can compound across years. Borrowers who plan to repay early or who have a short term may have less exposure to adjustments, but the risk is not zero. Reading the rate-change language closely is the best defense, and the section below covers what to look for in the agreement.
Reading Rate-Change Language in the Loan Agreement
Loan agreements contain a section that describes how the rate can change, often labeled something like variable rate feature, rate adjustments, or change in terms. This section is where the practical details live. It should identify the index, the margin, the frequency of adjustments, the effective date of each change, and any caps that limit how high or how fast the rate can rise. If any of those elements are missing or vague, ask the lender to clarify before signing.
Caps come in a few forms. A periodic cap limits how much the rate can increase at one adjustment. A lifetime cap limits the total increase over the life of the loan. A floor may set a minimum rate. These limits matter because they define the worst-case scenario for your payment. An offer with a low starting rate but a high lifetime cap carries more risk than one with a moderate starting rate and a tight cap. The agreement should state these numbers explicitly, not just refer to them in general terms.
Pay attention to how the lender calculates the new payment and whether the term can change. Some agreements specify that the payment adjusts to keep the original payoff date, while others allow the term to extend. A term extension can lower the monthly payment but increase total interest, which is a trade-off worth understanding in advance. Also look for notice requirements: lenders typically must tell you before a rate change takes effect, and the method and timing of that notice should be described.
If you are comparing multiple offers, a practical approach is to read the rate-change section of each one and note the index, margin, caps, and adjustment frequency in a simple table. That side-by-side view makes it easier to see which offers carry more uncertainty. It also gives you specific questions to ask the lender, which is the focus of a later section.
Matching Rate Structure to Repayment Window
The length of your repayment window is one of the strongest signals for choosing between fixed and variable pricing. Short windows, such as 12 to 24 months, leave less time for rate adjustments to accumulate. Long windows, such as 60 months or more, give more opportunities for the index to move and for your payment to change. That does not mean short-term borrowers should ignore variable risk, but it does mean the exposure is generally smaller.
For short repayment windows, a fixed rate offers certainty that can be worth more than a slightly lower starting variable rate. You know the payment, you know the payoff date, and you can budget around it. If the variable offer includes a low introductory rate that later adjusts, the savings in the early months may be offset by increases later, especially if the term is long enough for adjustments to occur. For borrowers using personal loans to cover an urgent expense, predictability often matters more than chasing the lowest initial number.
For longer windows, variable rates can make sense for borrowers who can absorb potential payment increases and who want to benefit if rates decline. However, the downside is asymmetric in practice: a payment increase can strain a budget, while a decrease may only modestly reduce it. Many borrowers prefer the certainty of a fixed rate for larger loans and longer terms, even if the starting rate is a bit higher. The right choice depends on your cash flow, your tolerance for uncertainty, and whether the agreement includes caps that limit the downside.
There is also a middle path worth considering. Some borrowers choose a fixed-rate loan for the core amount they need and keep a small buffer for emergencies, rather than stretching a variable-rate loan over a long term. That approach keeps the main obligation predictable while preserving flexibility. Whatever structure you choose, the goal is to align the rate type with how long you will be making payments and how much payment variability your budget can handle.
Questions to Ask a Lender About Rate Caps and Adjustments
Before accepting any personal loan offer, ask direct questions about how the rate behaves. Lenders should be able to explain the index, the margin, the caps, and the adjustment schedule in plain terms. If an answer is vague or refers only to the agreement without explanation, treat that as a signal to slow down. The questions below cover the essentials and can be used whether you are speaking with a lender or reviewing an online disclosure.
- Is the rate fixed or variable, and if variable, which index is used and what is the current margin?
- What are the periodic and lifetime caps on rate increases, and is there a floor?
- How often can the rate adjust, and when would the first adjustment occur?
- Will a rate change alter my monthly payment, my term, or both?
- How and when will I be notified before a rate change takes effect?
These questions also help you compare offers from different lenders on a consistent basis. A lender that answers clearly and provides specific numbers is easier to evaluate than one that offers general assurances. If you are working through a connecting service, remember that the service itself is not the lender and does not set the terms. The final rates, fees, and caps are determined by the third-party lender that makes the offer, so the answers should come from that lender or appear in its disclosure documents.
It also helps to ask what happens if you want to repay early. Some loans have prepayment penalties, while others do not. Early repayment can reduce your exposure to future rate changes on a variable loan, but only if the loan allows it without extra cost. Understanding this before you sign gives you more control over the total cost.
Comparing Offers Without Getting Misled by the Headline Rate
The lowest advertised rate is not always the lowest-cost loan. A variable offer with a low starting rate can end up costing more than a fixed offer with a slightly higher rate, depending on how the index moves and how long you hold the loan. To compare fairly, look at the APR, the rate type, the caps, the fees, and the repayment term together. A useful habit is to calculate or estimate the total interest you would pay under a plausible rate increase, not just the starting scenario.
Another practical step is to separate needs from wants. If the loan is covering an essential expense and your budget is tight, a fixed rate with a predictable payment is often the safer choice. If you have room in your budget for some variability and the term is short, a variable rate with strong caps may be acceptable. The point is to make the decision deliberately rather than defaulting to whichever number looks smallest on the offer screen.
Finally, keep the broader purpose in mind. Personal loans, including short-term options, are best used as temporary tools rather than long-term financial solutions. Whether you choose a fixed or variable rate, the goal is to repay on schedule and avoid letting the loan become a recurring cost. If you want to understand how different loan costs are structured across products, a related guide on why advance cash interest rates differ explains how pricing varies by product and lender. And if you are exploring short-term borrowing options from multiple lenders, services such as 4Payday can help you submit a request and review offers, though the final terms always come from the lender you choose.
Fixed versus variable rates on personal loan offers is ultimately a question of certainty versus potential savings. Fixed rates give you a stable payment and a clear payoff path. Variable rates may start lower and can benefit you if rates fall, but they carry the risk of increases that affect your budget. Read the rate-change language, ask about caps, match the structure to your repayment window, and compare the full cost rather than the headline number. That approach puts you in a stronger position to choose an offer that fits your finances and your tolerance for uncertainty.