Emergency Cash for a Utility Shutoff Notice: Fast Relief
Get emergency cash for a utility shutoff notice fast. Call 8335013363 to explore loan options and keep your power on.
By Emily Parker
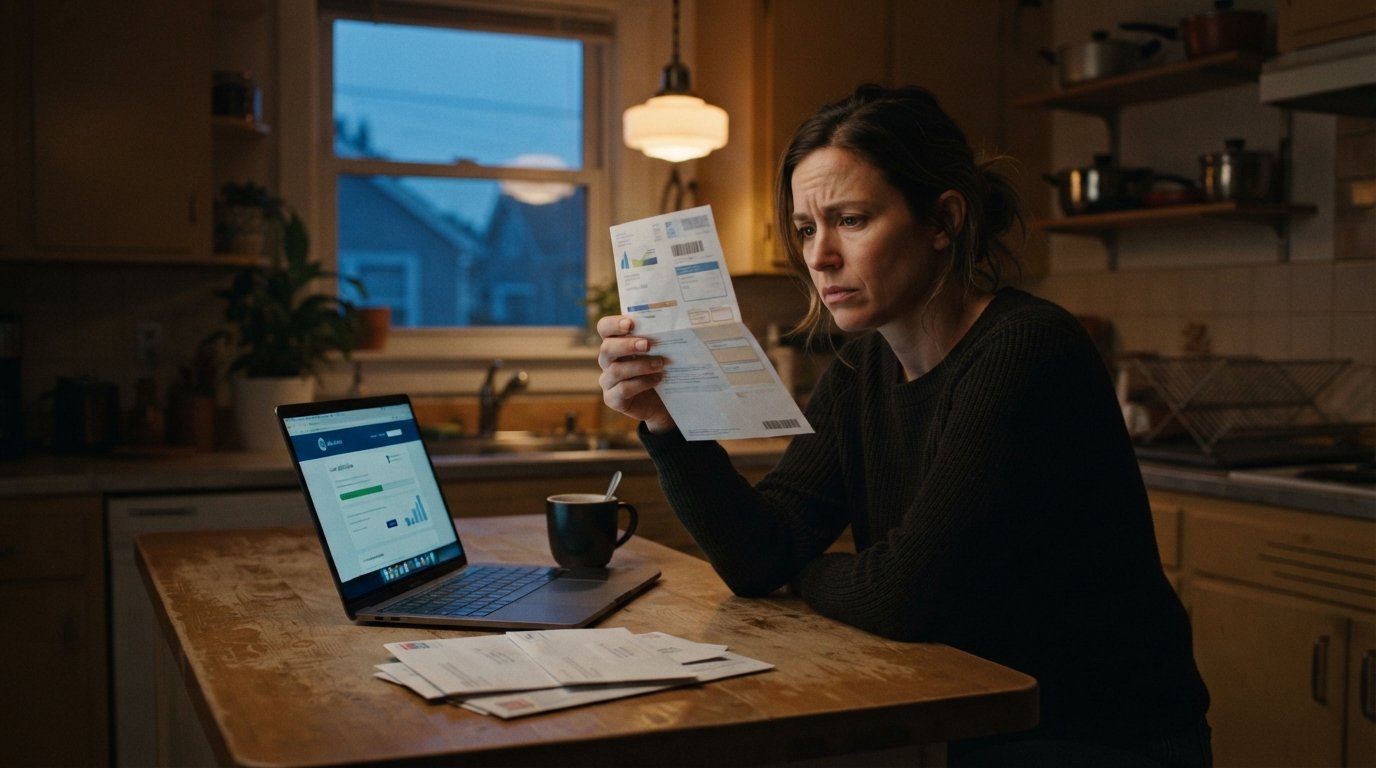
Your electricity or water is about to be disconnected, and the shutoff notice gives you only a few days to act. The stress is immediate, and the solution needs to be just as fast. Emergency cash for a utility shutoff notice can bridge the gap between a past-due balance and a restored account, but only if you understand where to look, what lenders require, and how to avoid making a temporary problem worse. This guide walks you through realistic funding paths, practical negotiation tactics, and the steps that protect your credit and your household.
Why Utility Shutoff Notices Create a Unique Cash Emergency
Utility companies operate under state regulations that dictate how much notice they must give before disconnection. In most states, a shutoff notice arrives 7 to 14 days before the scheduled termination date. That window is short, but it is not zero. The problem is that many households already live paycheck to paycheck, so an extra $150 to $400 bill lands like a brick.
Unlike a car repair that you can delay for a week, a utility shutoff has a hard deadline. Once the power or water is off, reconnection often requires paying the past-due balance plus a reconnect fee, and in some jurisdictions, a security deposit. That means waiting can double or triple your cost. The urgency is real, which is why emergency cash for a utility shutoff notice is one of the most common short-term borrowing needs in the United States.
There is another layer: shutoff notices affect renters and homeowners differently. Renters may have protections in certain states, especially during extreme weather. Homeowners typically have no such buffer. Regardless of your situation, the fastest path forward starts with knowing exactly how much you owe and the final date to pay.
How to Confirm the Exact Amount and Deadline
Before you apply for any loan, get the precise numbers. Call the utility company and ask for the total past-due amount, the reconnect fee if service has already been cut, and the final date and time to make a payment. Write these down. You will need them when comparing loan offers or negotiating a payment plan.
Ask specifically about payment extensions, partial payment arrangements, or low-income assistance programs. Many utilities have funds set aside for hardship cases, and they may not advertise them unless you ask. If you qualify, you might reduce the amount you need to borrow, which lowers your overall cost.
Once you know the exact figure, you can decide whether you need emergency cash for a utility shutoff notice or whether a payment plan will solve the problem without borrowing. If the utility agrees to split the balance over two or three months, you may avoid a loan entirely. If they refuse, you need a funding plan within 24 to 48 hours.
Fast Funding Options for Utility Shutoff Emergencies
When the deadline is tight, you have several realistic places to turn. Each has trade-offs in speed, cost, and eligibility. The best choice depends on your credit, your income, and how quickly you can repay.
- Online loan-connecting services: Submit one request and receive offers from multiple third-party lenders. Funding can arrive as soon as the next business day, and credit requirements vary by lender.
- Payday and cash advance loans: Small, short-term loans typically due on your next payday. Fast but expensive if rolled over.
- Installment loans: Larger amounts repaid over several months. Higher total cost but more manageable payments.
- Credit union small-dollar loans: Lower rates for members, but approval may take longer than a day.
- Payment arrangements with the utility: Not a loan, but the cheapest option if approved.
For most people facing a shutoff notice, the fastest route is an online loan-connecting platform. These services do not lend directly. Instead, they pass your information to a network of lenders who compete for your business. You can compare offers in minutes and choose the one with the lowest fee and most realistic repayment schedule.
If you are in Texas, you can also explore emergency cash advances in Houston to see how local borrowers handle urgent bills. The process is similar nationwide, but state regulations affect loan amounts, fees, and repayment terms.
How Online Loan Connecting Works for Urgent Bills
AdvanceCash.com is a loan-connecting service, not a direct lender. That distinction matters because it shapes what you can expect. You fill out a single secure online form with basic details: your name, contact information, income, and the amount you need. The platform then shares your request with third-party lenders who review it and may present offers.
You are never obligated to accept an offer. If the terms do not work for your budget, you can decline and try another path. The service is free to use, and it uses 256-bit SSL encryption to protect your data. Loan amounts range from $100 to $5,000 directly through the form, with some lenders offering up to $50,000 depending on your state and qualifications.
The key advantage is speed. Instead of calling five lenders one by one, you submit one request and let the network respond. For a utility shutoff notice, that efficiency can be the difference between keeping the lights on and paying a reconnect fee.
If you want to see how the process works end to end, you can connect with trusted lending partners through a simple online request. The platform is designed for borrowers with a range of credit backgrounds, including those with less-than-perfect credit.
What Lenders Look For When You Need Emergency Cash
Lenders who specialize in short-term loans do not use the same strict criteria as traditional banks. They focus on your ability to repay, not just your credit score. That said, they still evaluate several factors before making an offer.
- Income: Steady employment or regular benefits show you can handle a payment.
- Bank account: Most lenders require an active checking account for direct deposit and repayment.
- Identification: A government-issued ID and a Social Security number are standard.
- Credit history: A poor score does not automatically disqualify you, but it may affect your rate and loan amount.
- State of residence: Loan availability and terms vary by state law.
If you have bad credit, you may still qualify for emergency cash for a utility shutoff notice. Some lenders specialize in working with borrowers who have damaged credit. The trade-off is usually a higher fee or interest rate. That is why you should compare multiple offers before accepting one.
Pay attention to the annual percentage rate (APR), the repayment schedule, and any origination fees. A loan that looks cheap upfront can become expensive if you cannot repay it on time. Use the offers you receive to calculate the total cost, not just the monthly payment.
Step-by-Step: Getting Emergency Cash Before the Shutoff Date
When the clock is ticking, a clear sequence keeps you from wasting time. Follow these steps in order.
- Confirm the exact amount and deadline. Call the utility and write down the total due, including any reconnect fees.
- Ask about assistance programs. Before borrowing, check whether the utility offers a hardship plan or extension.
- Submit one online loan request. Use a loan-connecting service to reach multiple lenders at once.
- Compare offers carefully. Look at APR, fees, repayment terms, and total cost.
- Accept the best offer and receive funds. Many lenders deposit money as soon as the next business day.
- Pay the utility immediately. Do not wait, because processing times can vary.
- Set up repayment. Mark the due date and ensure funds are available.
If you cannot complete all steps before the shutoff date, call the utility again. Some companies will delay disconnection if you can show proof that a payment is in progress. A loan approval letter or a pending deposit may buy you an extra day or two.
Understanding the True Cost of Emergency Loans
Emergency cash for a utility shutoff notice solves an immediate problem, but it comes with a cost. Payday loans, for example, often carry fees of $15 to $30 per $100 borrowed. On a $300 loan, that is $45 to $90 in fees for a two-week term. If you cannot repay on time and roll the loan over, those fees compound quickly.
Installment loans spread the cost over several months, which lowers the monthly payment but increases the total interest you pay. A $1,000 installment loan with a 36% APR repaid over 12 months costs about $200 in interest. That is far less than rolling over a payday loan four times, but it is still real money.
The smartest approach is to borrow only what you need to cover the shutoff notice, not a penny more. If the past-due balance is $220, do not borrow $500 just because you qualify. Every extra dollar adds to your repayment burden. Treat the loan as a targeted tool, not a windfall.
Also, check whether your state caps interest rates on short-term loans. Some states limit APRs to 36% or less, while others allow much higher rates. Knowing your state's rules helps you spot predatory offers.
Alternatives to Borrowing for a Utility Shutoff Notice
Borrowing is not the only option. Before you sign a loan agreement, explore these alternatives. They may take more effort, but they can save you hundreds of dollars.
- Low Income Home Energy Assistance Program (LIHEAP): Federal funds administered by states to help with heating and cooling bills.
- Utility hardship programs: Many companies have internal funds for customers facing temporary setbacks.
- Payment plans: Ask to split the balance over two or three months.
- Local charities and churches: Community organizations often have emergency assistance funds.
- Family and friends: A short-term loan from a trusted person may be interest-free.
These options take time, so start with them immediately when you receive the notice. If they fail, then pursue emergency cash for a utility shutoff notice through a loan-connecting service. The combination of negotiation and borrowing can reduce the amount you need and lower your overall cost.
How to Avoid Future Shutoff Emergencies
Once the crisis passes, take steps to prevent it from happening again. Budgeting for utilities is easier when you smooth out seasonal spikes. Many utility companies offer level billing, which averages your payments across the year. That makes winter and summer bills predictable.
Build a small emergency fund, even if it is only $10 per week. Over six months, that is $260, enough to cover a typical past-due balance before it triggers a shutoff notice. Automate the transfer so you do not have to think about it.
If you have bad credit, work on improving your score so you qualify for better loan terms in the future. Pay bills on time, reduce credit card balances, and check your credit report for errors. A higher score opens doors to lower-cost borrowing when emergencies strike.
Finally, keep a list of local assistance resources and your utility company's hardship program contact information. When the next notice arrives, you will know exactly who to call and what to do.
Emergency cash for a utility shutoff notice is not a permanent fix, but it can keep your power on while you regain your footing. Confirm the deadline, ask for help, compare offers carefully, and borrow only what you need. With a clear plan, you can protect your home and your credit without turning a short-term crisis into a long-term debt problem.