Credit Union Personal Loan vs Online Lender Network
Compare credit union personal loans vs online lender networks for rates, speed, and approval odds. For inquiries, call 8335013363.
By Alex Thompson
When you need cash fast, the choice between a credit union personal loan and an online lender network can feel overwhelming. One offers the comfort of a local branch and relationship banking, while the other promises speed and access to multiple offers in minutes. Understanding how these two options differ in rates, approval odds, funding speed, and flexibility will help you make a decision that fits your financial situation. This guide breaks down the credit union personal loan versus online lender network comparison so you can borrow with confidence.
How Credit Unions and Online Lender Networks Differ
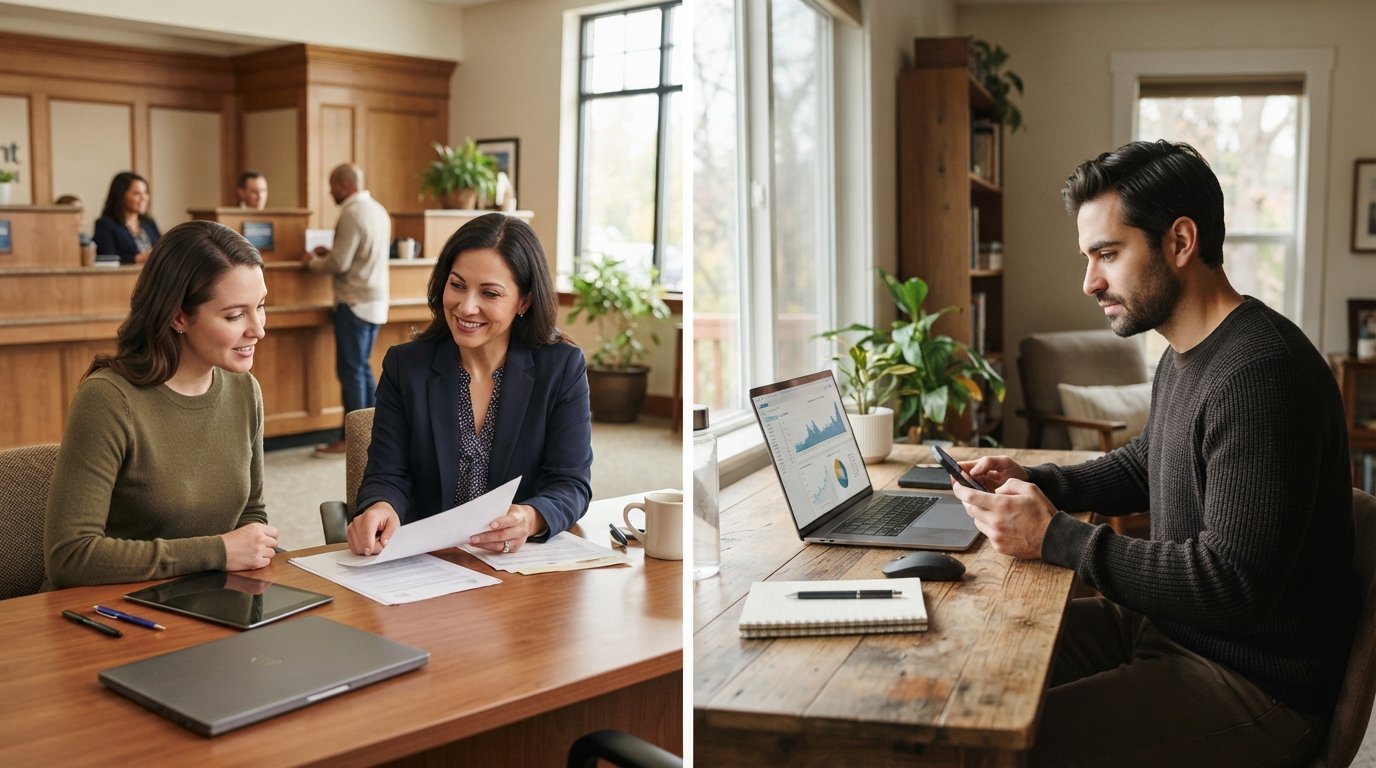
Credit unions are member-owned, not-for-profit financial cooperatives. When you take out a personal loan from a credit union, you are borrowing from an institution that exists to serve its members rather than generate profits for shareholders. This structure often translates into lower interest rates, fewer fees, and more personalized service. However, membership typically requires meeting certain eligibility criteria, such as living in a specific geographic area, working for a particular employer, or joining an association.
Online lender networks operate very differently. These platforms, including services like CashLoanFunded, connect borrowers with a network of third-party lenders. You submit a single request, and multiple lenders may review your information and present offers. The key advantage is speed and convenience: you can complete the entire process from your phone or computer, often receiving offers within minutes. The trade-off is that rates and terms vary widely because they are set by individual lenders, not by the network itself.
Understanding this fundamental difference is critical. A credit union personal loan versus online lender network comparison is not just about rates; it is about the entire borrowing experience, from application to funding to ongoing support.
Interest Rates and Fees: Where the Real Cost Lives
Interest rates are often the first thing borrowers compare, and for good reason. Credit unions typically offer lower annual percentage rates (APRs) than many other lending sources because they are not driven by profit maximization. According to industry data, credit union personal loan rates often range from about 8% to 18% APR, depending on your creditworthiness and the term you choose. Fees are also generally minimal, with many credit unions charging no origination fees or prepayment penalties.
Online lender networks present a broader range. Because these platforms work with many lenders, the APR you see depends entirely on the lender that approves you and your credit profile. Rates can range from competitive (similar to credit unions) for borrowers with excellent credit to significantly higher for those with less-than-perfect credit. Some lenders in these networks may charge origination fees, late fees, or prepayment penalties, so reading the fine print is essential.
Here is a quick breakdown of typical cost structures you might encounter:
- Credit union personal loan: Lower APRs (often 8% to 18%), minimal fees, no prepayment penalties
- Online lender network: APRs vary widely (can be 5% to 36% or higher), possible origination fees, terms set by individual lenders
- Speed of funding: Credit unions may take 1 to 3 business days; online networks can fund as soon as the next business day
- Credit requirements: Credit unions often prefer established credit; online networks may accommodate bad credit or no credit
While credit unions generally win on cost, online lender networks can be a lifeline when you need fast cash and cannot wait for a credit union approval process. The key is to weigh the total cost against your urgency and credit situation.
Approval Odds and Credit Requirements
Credit unions tend to have stricter credit requirements than online lender networks. Because they are member-owned and risk-averse, they often look for borrowers with established credit histories, stable income, and low debt-to-income ratios. If you have a score below 600, you may find it challenging to qualify for a credit union personal loan without a co-signer or collateral.
Online lender networks, by contrast, are designed to accommodate a wider range of credit profiles. Many lenders in these networks specialize in working with borrowers who have bad credit or limited credit history. While you may pay a higher interest rate, you have a better chance of getting approved. This makes online lender networks a practical option for people who have been turned down by traditional banks or credit unions.
It is also worth noting that some credit unions offer "second chance" or credit-builder loans specifically designed for members with damaged credit. However, these programs are not universally available, and they may come with higher rates or lower loan amounts. If you are unsure about your approval odds, an online lender network can provide a quick, no-obligation way to see what offers you might receive.
Speed and Convenience: Getting Your Money Fast
When you are facing an urgent expense, such as a car repair or medical bill, speed matters. Online lender networks excel in this area. The application process is entirely digital, and you can often receive multiple offers within minutes. Once you accept an offer, funds can be deposited directly into your bank account, sometimes as soon as the next business day.
Credit unions, while offering competitive rates, typically have a slower process. You may need to visit a branch, provide documentation, and wait for manual underwriting. Even credit unions with online applications may take several business days to approve and disburse funds. If you have time to plan ahead, this slower pace is a fair trade for lower costs. But if you need money now, an online lender network is often the more practical choice.
For those exploring fast funding options, resources like Affordable Personal Loans in Florida for Emergency Auto Repairs illustrate how online lending can address urgent needs efficiently.
Loan Amounts, Terms, and Flexibility
Credit unions typically offer personal loans ranging from a few hundred dollars to $50,000 or more, with terms from one to seven years. Because they are relationship-driven, they may be more willing to customize terms for members, such as adjusting due dates or offering payment holidays during hardship.
Online lender networks also offer a wide range of loan amounts, often from $100 to $5,000, and sometimes up to $50,000 depending on the lender. Terms can be short (a few months) or longer (several years). The flexibility here comes from the variety of lenders: you can compare offers and choose the one that best fits your budget. However, because you are dealing with a network rather than a single institution, you will not have the same ongoing relationship or ability to negotiate terms later.
It is important to read the terms carefully with any lender. For credit unions, ask about prepayment penalties and whether you can change your payment date. For online lenders, confirm the APR, origination fee, and repayment schedule before signing. The best choice depends on whether you value long-term flexibility or immediate access to funds.
Customer Service and Member Benefits
Credit unions are known for personalized customer service. As a member, you can often speak with a representative who knows your history and can work with you if you run into trouble. Many credit unions also offer financial education, budgeting tools, and other member perks that go beyond the loan itself.
Online lender networks, by contrast, are more transactional. You interact primarily through digital interfaces, and customer support may be limited to email or phone. However, the best networks provide clear disclosures and helpful support to guide you through the process. If you value convenience and do not need hand-holding, this trade-off is usually acceptable.
Consider what matters most to you: a long-term banking relationship with a credit union, or a fast, efficient borrowing experience with an online network. Both have their place, and your choice should align with your financial habits and immediate needs.
Which Option Is Right for You?
There is no one-size-fits-all answer to the credit union personal loan versus online lender network debate. Your decision should hinge on your credit score, how quickly you need funds, and how much you value personalized service.
Choose a credit union personal loan if:
- You have good to excellent credit and want the lowest possible rate
- You can wait a few days for funding
- You value a long-term relationship with a local institution
- You prefer minimal fees and no prepayment penalties
Choose an online lender network if:
- You need cash quickly, ideally by the next business day
- You have less-than-perfect credit or a thin credit file
- You want to compare multiple offers in one place
- You prefer a fully digital application process
In some cases, you might use both: an online lender network for immediate needs and a credit union for larger, longer-term goals. The key is to borrow responsibly, understand all terms, and never take on more debt than you can repay.
Before you commit, take a moment to evaluate your budget, explore your options, and read the fine print. Whether you go with a credit union or an online lender network, informed borrowing is your best protection against financial stress.