Credit Union Loan vs. Online Lender Network: How to Compare
Compare a credit union loan with an online lender network by weighing speed, total cost, and eligibility so you avoid paying more than necessary.
When you need money quickly, the choice between a credit union and an online lender network can feel like a trade-off between cost and speed. A credit union might offer a lower interest rate, but the application process can take days. An online lender network can surface multiple offers in minutes, but you may pay more for that convenience. The key is knowing exactly what to compare so you do not sacrifice one benefit for another without realizing it. This guide walks you through how to compare a credit union loan with an online lender network step by step, so you can choose the option that fits your timeline and your budget.
Start with Your Timeline, Then Compare Costs
Before you look at a single interest rate, get honest about how soon you need the money. If your rent is due tomorrow or your car repair cannot wait until next week, a credit union loan may not be practical even if it is cheaper on paper. Credit unions are member-owned cooperatives, and that structure often translates into lower rates and fewer fees. But the trade-off is a slower process: you may need to open a membership account first, provide documentation in person or by phone, and wait for underwriting that can take several business days.
Online lender networks, by contrast, are built for speed. You submit one request, and the network routes it to multiple third-party lenders who may compete for your business. Decisions can arrive in minutes, and funds may be available as soon as the next business day. That speed comes with a caveat: the lenders in these networks often specialize in short-term or installment loans for borrowers with less-than-perfect credit, and the annual percentage rates can run higher than what a credit union would charge.
So the first comparison point is not just the rate itself, but the total cost of waiting versus the total cost of borrowing quickly. Ask yourself: if I wait three days for a credit union decision, will I incur a late fee, a utility shutoff fee, or a missed payment that damages my credit? If the answer is yes, the effective cost of the slower option may be higher than it first appears. If you have a little flexibility, the credit union route can save you real money over the life of the loan.
Evaluate Eligibility and Membership Requirements
Credit unions are not open to everyone. Most require you to meet a field of membership rule, which can be based on your employer, your geographic area, a family member's membership, or a community organization. Some credit unions have broad eligibility, but others are narrow. Before you invest time in an application, confirm that you qualify to join. You will also typically need to open a savings account with a small deposit, which is your share of ownership in the cooperative.
Online lender networks cast a wider net. Because they work with many third-party lenders, they can often accommodate borrowers with bad credit, no credit history, or irregular income. That does not mean approval is guaranteed, and it does not mean every offer will be affordable. But the eligibility bar is usually lower than at a traditional credit union, which makes these networks a practical option when you have been turned down elsewhere.
Here is a quick checklist of eligibility questions to ask each option before you commit:
- Can I join this credit union based on my employer, location, or family? If not, is there a community organization I can join to qualify?
- What is the minimum deposit to open a membership account, and does it earn dividends?
- Does the online lender network require a minimum credit score, or does it work with a range of credit profiles?
- What documentation will each option require (pay stubs, bank statements, government ID), and how long will verification take?
- Are there any application fees, origination fees, or prepayment penalties?
Answering these questions side by side will quickly reveal which option is realistically available to you. A lower rate is meaningless if you cannot qualify for membership or if the verification process takes longer than your deadline allows.
Compare the Full Cost of Borrowing, Not Just the Interest Rate
The advertised interest rate is only one piece of the cost puzzle. Credit unions are required to disclose the annual percentage rate (APR), which includes both the interest rate and most fees. Online lender networks also disclose APR, but the range can be wide because each third-party lender sets its own terms. When you compare a credit union loan with an online lender network, put the APR at the top of your comparison sheet, then add the following line items:
- Origination fee: Some lenders charge a percentage of the loan amount upfront. A 5% origination fee on a $2,000 loan adds $100 to your cost before you make a single payment.
- Prepayment penalty: Credit unions rarely charge this, but some online lenders do. If you plan to pay off early, confirm there is no penalty.
- Late payment fees: These can vary widely. A $35 late fee on a small loan can rival the interest charge for that month.
- Membership or account fees: Credit unions may require a small monthly maintenance fee or a minimum balance. Factor these into the total cost.
- Repayment term: A longer term lowers your monthly payment but increases the total interest you pay. Compare the total of payments, not just the monthly figure.
A useful exercise is to calculate the total cost of credit for each option: multiply your monthly payment by the number of payments, then subtract the amount you borrowed. That number tells you what you are paying for the privilege of borrowing. Run it for the credit union offer and for the best two or three offers from the online lender network. You may find that the network's fastest offer is not the cheapest, or that a slightly longer wait at the credit union saves you hundreds of dollars.
Ask the Right Questions Before You Sign
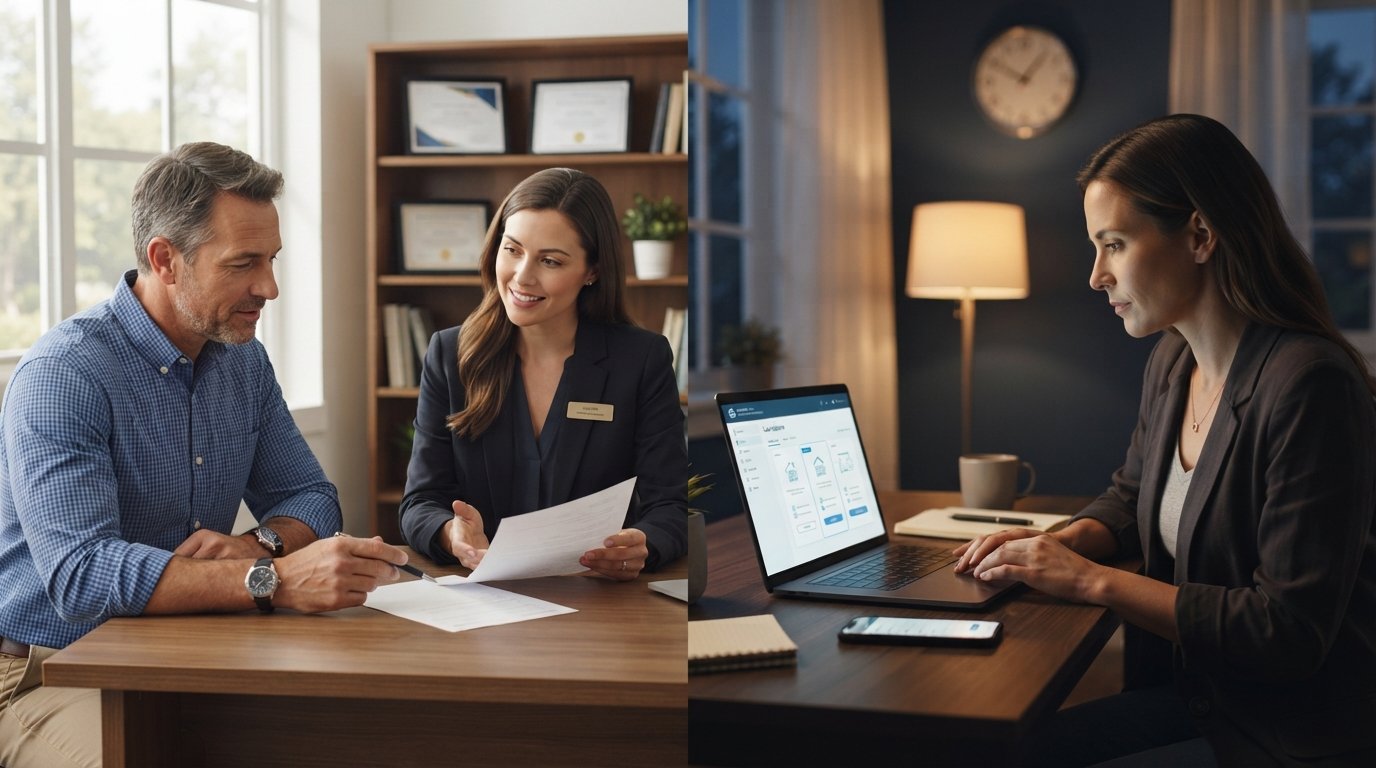
Whether you are sitting across from a credit union loan officer or reviewing offers on a lender network's dashboard, the questions you ask should be the same. The answers will tell you how transparent each option is and whether the terms are sustainable for your budget.
Start with the repayment schedule. Ask exactly when the first payment is due, how often payments are withdrawn, and whether you can choose a due date that aligns with your payday. Then ask what happens if you miss a payment: does the lender offer a grace period, and will a late payment be reported to the credit bureaus? Credit unions often have more flexibility to work with members who hit a rough patch, while online lenders may follow stricter collection timelines.
Next, ask about the total repayment amount and whether there are any balloon payments or variable rates. A variable rate can rise over time, which makes budgeting harder. If the loan has a variable rate, ask how often it adjusts and what the maximum cap is. Finally, ask whether the lender reports to the major credit bureaus. On-time payments can help you build credit, which is a meaningful benefit that goes beyond the interest rate. If you want a broader overview of fast funding options before you apply, our guide to top online lenders for fast cash advances can help you understand the landscape.
For borrowers who want to see multiple offers in one place without visiting several credit unions and websites, a connection service can simplify the comparison. StartPaydayLoan is a free online connection service that helps U.S. consumers find short-term and payday loan options. Visitors complete one simple request form and may be matched with third-party lenders in the network. It is not a lender and does not make credit decisions; any loan terms come directly from the lender. The site also publishes plain-language guides on borrowing and budgeting, which can help you ask better questions when you compare offers.
Weigh Speed, Convenience, and Customer Service
Cost is not the only factor. Think about how you prefer to do business. Credit unions often provide a personal touch: you can walk into a branch, talk to a loan officer, and get help understanding the paperwork. That human guidance can be valuable if you are new to borrowing or if your financial situation is complicated. The trade-off is that branch hours, paperwork requirements, and back-office processing can slow things down.
Online lender networks operate entirely online, which means you can apply at midnight and receive a decision before morning. That convenience matters when you are dealing with an emergency. But you will not have a single point of contact who knows your situation; you will be dealing with whichever third-party lender makes the offer. Read reviews and check the lender's contact options before you accept. A lender that offers phone support and a clear repayment portal is easier to work with than one that only communicates by email.
Also consider the application experience itself. A credit union may require you to upload documents or visit a branch, while an online network may use automated verification that pulls your information instantly. Neither approach is inherently better, but one may fit your schedule and comfort level more than the other. If you value speed and digital convenience, the network model has a clear edge. If you value a relationship and the ability to ask questions face to face, the credit union may be worth the wait.
Check the Fine Print for Red Flags
Both credit unions and online lender networks are regulated, but the fine print can still contain surprises. Watch for these red flags as you compare:
- Prepayment penalties that punish you for paying off the loan early.
- Automatic renewal or rollover features that extend the loan and add fees instead of helping you pay it down.
- Unclear fee schedules that do not disclose origination, late, or insufficient funds fees upfront.
- Pressure to accept an offer immediately before you have had time to read the terms.
- No physical address or phone number for the lender, which makes it hard to resolve disputes.
Credit unions are member-owned, so their fee structures tend to be simpler and more transparent. Online lender networks vary widely because each third-party lender sets its own terms. That is why comparing multiple offers is essential: one lender may bury a fee that another discloses clearly. Take screenshots or print the terms of each offer so you can compare them line by line without relying on memory.
Finally, confirm that the lender is licensed to do business in your state. State regulations cap fees and interest rates for short-term loans, and a licensed lender will comply with those caps. If a lender cannot tell you its license number or the name of the regulator that oversees it, walk away.
Make the Decision with a Simple Framework
You do not need a spreadsheet with dozens of columns to make a sound choice. A simple three-step framework can keep you focused on what matters most. First, confirm eligibility and timeline: can you qualify, and can the option deliver funds before your deadline? Second, compare the total cost of credit, including APR, fees, and the total of payments. Third, assess the terms and the lender's reputation: are the repayment terms sustainable, and does the lender communicate clearly?
If two options are close on cost, choose the one with the more flexible repayment terms and the better customer service. A slightly higher APR with a lender who will work with you if you hit a rough patch may be safer than a lower APR with a lender who imposes stiff late fees. And if the credit union option is affordable and you can wait a few days, it is often the better long-term choice because the lower cost leaves more room in your budget for other needs.
Remember that short-term loans are best used as temporary bridges, not long-term solutions. Whether you choose a credit union or an online lender network, borrow only what you need, repay on time, and use the experience to strengthen your credit profile. If you are unsure where to start, comparing offers from multiple sources is the single most effective way to protect your wallet. Take the time to ask questions, read the fine print, and choose the option that fits your timeline without creating a new financial burden.