Can You Get a Short Term Loan on Unemployment Benefits?
Unemployment income can qualify for a short term loan with some lenders. See what proof they need and how to keep payments affordable on benefits.
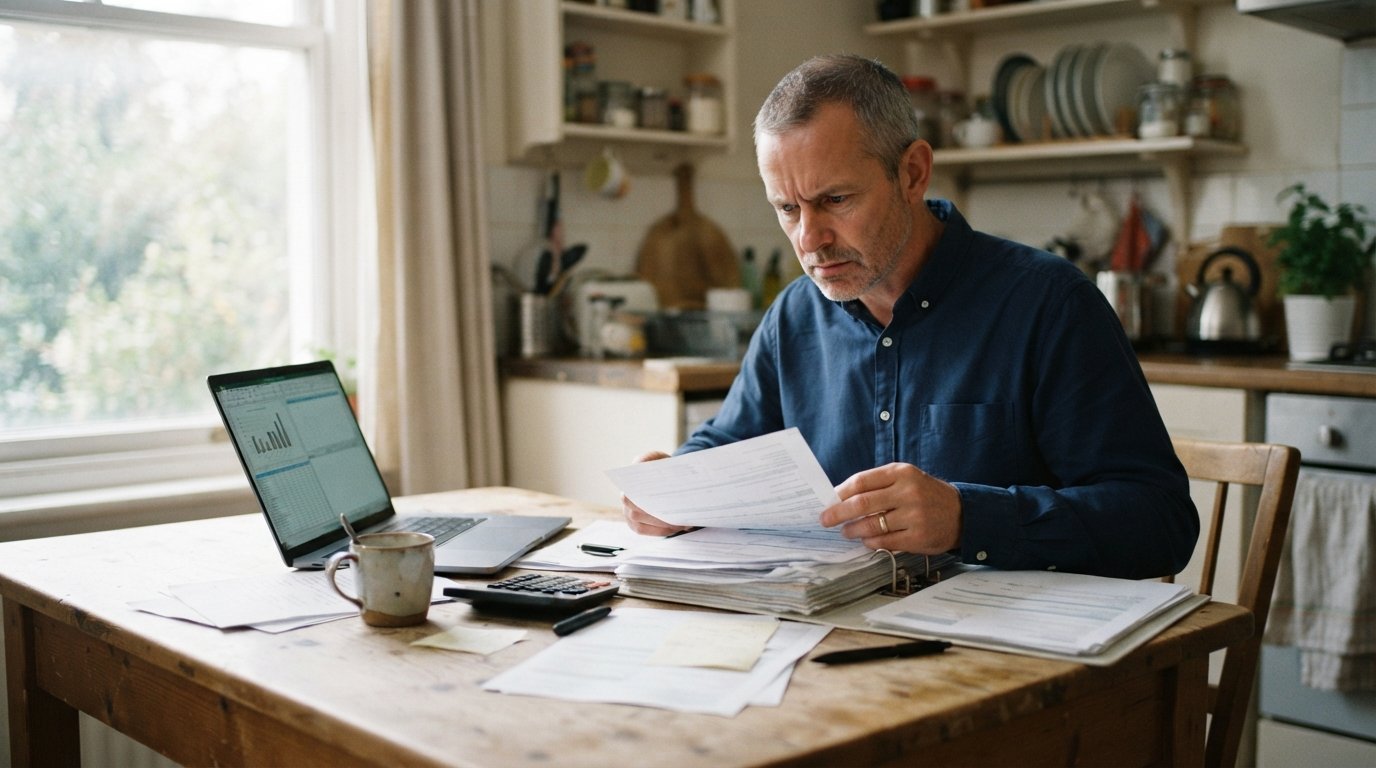
If you are collecting unemployment benefits and an unexpected expense lands on your doorstep, the question of whether you can get a short term loan on unemployment benefits becomes urgent. The short answer is yes, it is possible, but the path is narrower than it is for someone with a steady paycheck. Many traditional banks will not count unemployment income as qualifying income, yet a growing number of online lenders and loan-connection services are willing to look at benefit income alongside other factors. Understanding how lenders view unemployment, what documentation they need, and how to plan repayment on a fixed income can mean the difference between a helpful bridge and a costly trap.
This guide walks through the realities of borrowing while unemployed, from the proof of income lenders typically request to the alternatives worth exploring before you sign anything. It also explains how benefit amount and duration shape the offers you may see, and how to build a repayment plan that does not put your benefits at risk.
How Lenders View Unemployment Income
Unemployment benefits are a form of income, but they are temporary by design. That distinction matters to lenders. A bank evaluating a personal loan usually wants to see a stable, ongoing income stream that will continue past the loan term. Unemployment benefits, even when they arrive reliably every week, have an expiration date and can be reduced or ended if your claim status changes. As a result, many mainstream lenders treat benefits as secondary income at best, and some will not count them at all.
That does not mean the door is closed. Online lenders and short term lending networks often use broader criteria than banks. They may consider your benefit amount, the remaining duration of your claim, any household income from a spouse or roommate, and your credit history. Some lenders will approve a loan based on benefits alone if the amount is sufficient to cover the payment and the claim has months left to run. Others will require a co-borrower or a secondary income source. The key is to be honest about your situation and to understand that the offer you receive, if any, will reflect the lender's view of your risk.
It helps to think of unemployment income as one factor in a larger picture. Lenders who work with borrowers in transition often weigh bank account history, recent payment behavior, and the size of the requested loan against the benefit. A small loan that can be repaid within a few weeks from a single benefit check is viewed very differently from a large installment loan that would stretch across many months of uncertain income. If you want to understand the broader category of products available, a clear guide to advance cash loans can help you see how short term funding works before you apply.
What Lenders Typically Require as Proof of Income
When you apply for a short term loan while receiving unemployment, the lender will want evidence that money is actually coming in. The exact documents vary by lender, but most will ask for a combination of the following:
- Recent unemployment benefit statements or claim summaries showing your weekly or biweekly amount
- Bank statements covering the last one to three months, which show the deposits landing in your account
- Government-issued photo identification and proof of your current address
- Your Social Security number and, in many cases, a record of your claim start date and remaining balance
Some lenders also ask for a benefits award letter or an online portal screenshot that shows your claim status and weekly benefit amount. Because unemployment systems vary by state, there is no single universal document, so be prepared to provide whatever official record your state issues. Lenders who work with borrowers in this situation are familiar with these formats and can usually tell you exactly what they need before you submit a request.
If you have other income, such as a part-time job, freelance work, or a spouse's paycheck, gather documentation for that as well. A combined income picture is stronger than benefits alone, and it may widen the range of offers you receive. The same is true if you have savings or a retirement account you can reference, even if you do not plan to draw on it. Lenders want to see that the loan payment will fit comfortably within your total monthly resources.
How Benefit Amount and Duration Affect Your Offer
Two numbers matter more than almost anything else when a lender evaluates unemployment income: how much you receive each week and how long the benefits are scheduled to continue. A higher weekly benefit supports a larger loan payment. A longer remaining duration gives the lender more confidence that payments can be made before the claim ends. If your benefits are set to expire in a few weeks, a lender may limit the loan term or decline the request altogether, because the income stream backing the loan is about to disappear.
This is why the timing of your application matters. Applying early in your benefit period, when months of payments remain, generally produces better outcomes than applying near the end of your claim. If you are close to exhaustion, consider whether a smaller loan with a shorter term could be repaid from your final checks, or whether another option might be safer. It is also worth checking whether your state offers extensions, because a pending extension can change a lender's view of your income stability.
The requested loan amount should align with your benefit. A common guideline is to keep the monthly loan payment well below the portion of your benefit that is not already committed to rent, utilities, food, and other essentials. If your benefit is $300 per week and your fixed expenses consume most of it, adding a loan payment may create a shortfall that forces you to borrow again. Lenders see this pattern too, and a request that looks unaffordable relative to your benefit is likely to be declined or offered at a smaller amount.
Where to Look for a Short Term Loan While on Benefits
Traditional banks and credit unions are often the hardest places to qualify while unemployed, though a credit union where you have a long relationship may be more flexible. The more practical route for many borrowers is an online loan-connection service that works with a network of third-party lenders. These services let you submit one request and receive offers from lenders who are willing to consider unemployment income, often with funding available as soon as the next business day.
One option in this space is StartPaydayLoan, a free online connection service that helps U.S. consumers find short term and payday loan options. Visitors complete a single request form and may be matched with third-party lenders in the network. It is important to understand that such services are not lenders and do not make credit decisions; any loan terms come directly from the lender. The site also publishes plain-language guides on borrowing, budgeting, and repayment, which can be useful when you are weighing an offer against your benefit income.
Before you accept any offer, compare the annual percentage rate, the repayment schedule, and the total cost of the loan. A short term loan can be a reasonable bridge when the fee is transparent and the repayment fits your benefit cycle. It becomes dangerous when the cost is unclear or the payment leaves no room for essentials. Take the time to read the lender's terms in full, and do not feel pressured to accept the first offer you see. You are never obligated to take a loan just because you submitted a request.
Other Options to Explore While Benefits Continue
A short term loan is not the only path, and it is worth reviewing alternatives before you commit to borrowing. Some options are cheaper, some are slower, and some are better suited to a temporary income gap. Consider the following before you apply:
- Contact your creditors and ask about hardship programs, deferments, or modified payment plans. Many utilities, landlords, and card issuers have options for customers facing temporary income loss.
- Check whether you qualify for state or federal assistance programs, such as SNAP, LIHEAP, or emergency rental assistance, which do not require repayment.
- Ask family or friends for a short term loan with a written agreement, which avoids interest and fees entirely.
- Look into nonprofit credit counseling, which can help you negotiate debts and build a budget on your benefit income.
- Explore a small credit union personal loan or a secured loan against a savings account, which may have lower costs than a payday-style product.
Each of these options has tradeoffs. Assistance programs can take time to process, and family loans can strain relationships if repayment is unclear. Credit counseling is free or low cost in many areas and can provide a realistic plan. The right choice depends on how quickly you need funds, how much you need, and how confident you are in your ability to repay. If you do decide to borrow, choose the smallest amount and shortest term that solves the immediate problem, and confirm that the payment fits within your weekly benefit.
Planning Repayment on a Fixed, Temporary Income
Repaying a loan while on unemployment requires more discipline than repaying one from a paycheck, because your income is fixed and time limited. Start by building a simple monthly budget based on your benefit amount. List your essential expenses first, then set aside the loan payment before discretionary spending. If the numbers do not work, the loan is too large, and it is better to reduce the request or choose a different option than to fall behind.
Align your payment due dates with your benefit deposit schedule. If your benefits arrive on Wednesdays, a payment due on Thursday is easier to manage than one due on Monday, when your account may be low. Set a reminder or automatic transfer for the day after your deposit so the payment is covered before other spending begins. Keep a small buffer in your account if possible, even $50, to absorb timing differences between deposits and due dates.
Have a plan for the end of your benefit period. If your claim will expire before the loan is repaid, identify how you will cover the remaining payments, whether through new employment, a part-time job, or a household contribution. Lenders appreciate borrowers who can explain this plan, and it protects you from a late payment that could damage your credit score. If your situation changes, contact the lender before a payment is missed. Many lenders offer hardship options, and early communication is far better than silence.
Finally, treat the loan as a one-time bridge, not a recurring solution. Borrowing again to cover a previous loan is a sign that the payment does not fit your budget. If you find yourself in that cycle, pause and seek credit counseling or a nonprofit debt management plan. Unemployment is temporary, and the goal is to get through it without adding long term financial strain.
Can you get a short term loan on unemployment benefits? Yes, but the strongest applications come from borrowers who understand how lenders view benefit income, provide clear proof of their deposits, request an amount that fits their weekly check, and plan repayment around their deposit schedule. Whether you use a connection service, a credit union, or a community resource, the same principles apply: borrow only what you need, read every term, and keep the payment small enough that your benefits still cover the essentials.